|
시장보고서
상품코드
2122038
푸드서비스 포장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Food Service Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
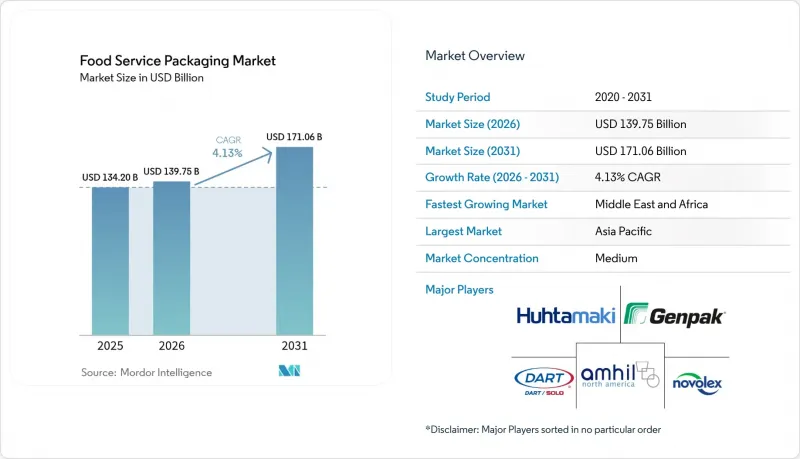
에 의하면, 외식산업용 포장 시장 규모는 2025년 1,342억 달러에서 2026년에는 1,397억 5,000만 달러에 이르고, 2026-2031년 CAGR 4.13%로 성장을 지속하여 2031년에는 1,710억 6,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 소재(종이 및 판지, 플라스틱, 기타), 포장 유형(클램쉘, 컵·용기, 기타), 최종 사용자 산업(QSR, FSR, 기관용 케이터링, 기타),지속가능성 프로파일(기존, 지속 가능형), 지역(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 푸드서비스용 포장 시장 동향 및 인사이트
도시 지역에서 ‘테이크아웃용’이자 ‘분량이 조절된’ 식사에 대한 수요 증가
도시 지역에 거주하는 젊은 소비자들이 짧은 출퇴근 시간 동안 다 먹을 수 있는 편리한 1인분 크기의 식사를 선호하게 되면서, 1인분 단위 포장이 대량 포장 형태를 앞지르는 추세를 보이고 있습니다. 브랜드 소유주들은 현재 자판기 및 마이크로 풀필먼트 사물함에 대응하고, 칼로리 아이콘과 스캔 가능한 QR 영양 태그가 통합된, 쌓을 수 있는 트레이를 지정하고 있습니다. 독일에서 맥도날드가 실시한 종이 햄버거 포장지 시범 도입은 다국적 QSR 체인이 편의성과 지속가능성을 융합하여 도시권 고객을 만족시키고 있음을 보여줍니다. 기관 구매자들도 이러한 추세를 뒷받침하고 있습니다. 영국 국민보건서비스(NHS)가 수립한 급식용 소모품 프레임워크에서는 분량의 표준화가 도모되는 동시에 알레르기 유발 물질 대응 라벨 표기가 의무화되어 있습니다. 그 결과, 모듈식 다이 커팅 및 가변 데이터 라벨링에 정통한 변환 업체들은 복잡한 도시 지역의 서비스 요건을 충족하면서 비용 면에서 우위를 점하고 있습니다.
전자상거래의 밀키트 붐이 2차 및 3차 포장 수요를 가속화하고 있습니다.
밀키트 사업자들은 생단백질을 보호하고, 냄새 이전을 방지하며, 2일간의 택배 배송 주기를 견딜 수 있는 다층 구조의 솔루션을 필요로 합니다. 이러한 수요를 배경으로, 냉매 사용량과 운송 중량을 줄이도록 설계된 맞춤형 배리어 파우치, 골판지 쿨러 박스, 성형 섬유 인서트에 대한 투자가 활발해지고 있습니다. 각 공급업체들은 변조나 온도 편차를 감지하기 위해 외부 포장 상자에 NFC 신선도 태그를 탑재하는 사례가 늘고 있습니다. 이는 2024년 테트라팩이 실시한, 소비자에게 직접 배송되는 유제품용 센서 탑재 시범 프로젝트를 반영한 것입니다. 공급 리스크를 완화하기 위해 미국과 독일에서는 국내 성형 섬유 생산 라인이 신설되고 있으며, 아시아태평양의 제조업체들은 밀키트용 오븐 및 전자레인지에 대응하는 수성 잉크 시스템을 공급할 수 있도록 설비 현대화를 추진하고 있습니다.
60개국 이상에서 일회용 EPS 및 PVC에 대한 규제에 따른 단계적 폐지가 진행되고 있습니다.
금지 조치가 가속화됨에 따라 전환 기간이 12-18개월로 단축되어 대체 소재 공급업체공급 능력에 부담이 가중되고 있습니다. 프랑스의 AGEC법에 따라 맥도날드는 2024년에 재사용 가능한 폴리프로필렌 트레이 도입이 의무화됨에 따라 매장 내 업무 워크플로우를 재검토하고, 매장 내 식사 주문을 위한 실리콘 고무 용기의 시범 도입을 진행하고 있습니다. 소규모 사업자들은 주방 식기 세척 및 보증금 물류 시스템을 개선하기 위한 설비 투자 자금이 부족하여, 이로 인해 제3자 풀 서비스로의 전환이 촉진되고 있으며, 자금력이 있는 체인점으로의 통합이 더욱 가속화되고 있습니다.
부문 분석
2025년, 플라스틱은 외식 산업용 포장 시장에서 41.98%라는 최대 점유율을 유지했습니다. 이는 비용 효율성이 뛰어나고, 높은 투명성으로 인해 상품을 잘 볼 수 있으며, 음료용 뚜껑이나 고온 충전 수프 용기에 여전히 필수적인 밀폐성이라는 장점 덕분입니다. 그럼에도 불구하고 생분해성 및 특수 기질은 연평균 성장률(CAGR) 5.42%를 나타낼 것으로 예측되며, 이는 친환경 라벨에 대한 수요 증가와 북유럽 도시 지역의 퇴비화 인프라 확충을 반영한 것입니다. 생분해성 필름을 사용한 외식 산업용 포장 시장 규모는 2031년까지 263억 6,000만 달러에 달할 것으로 예측되며, 이는 현재 100℃에서 전자레인지로 재가열해도 뒤틀림이 발생하지 않는 전분 혼합 소재의 보급에 힘입은 것입니다. 기존 플라스틱 분야에서는 PFAS 제거 및 화학적 재활용 기술이 연구개발 예산의 대부분을 차지하고 있으며, 맥도날드가 2024년에 불소화 화합물의 99.5%를 단계적으로 폐지하겠다는 목표를 달성한 것이 그 증거입니다.
종이 및 판지는 계속해서 고급 시장으로 전환되고 있으며, 수성 분산 코팅은 현재 8시간의 내열성 및 내유지성을 실현하여 햄버거용 클램쉘 용기나 면류용 그릇에 섬유 소재를 적용할 수 있게 되었습니다. 알루미늄 캔과 트레이는 항공기 기내식이나 고산성 식품 성분과 같은 틈새 수요를 유지하고 있지만, 경량 복합 카톤과의 경쟁에서 고전하고 있습니다. 유리의 경우, 배송 플랫폼이 무게와 파손 위험을 불리하게 평가하고 있어 시장 침투율은 극히 미미합니다. 수지 가격 변동이 지속되는 가운데, 가공업체들은 보온성을 유지하면서 폴리머 사용량을 50% 줄이는 PP와 펄프의 하이브리드 솔루션으로 위험을 헤지하고 있으며, 이를 통해 생분해성 소재가 외식 산업용 포장 시장에서 주요 혁신 분야로서의 입지를 강화하고 있습니다.
컵과 용기는 범용 음료 및 수프 용도로의 활용과 단가를 낮추기 위해 대량 주문을 하는 QSR(퀵 서비스 레스토랑)에 힘입어 2025년에도 매출에서 37.89%의 선두를 유지했습니다. 그럼에도 불구하고, 배달 중심의 메뉴 설계에 힘입어 트레이와 용기는 연평균 성장률(CAGR) 5.11%로 급성장하고 있습니다. 고스트 키친이 스냅핏식 뚜껑과 김서림 방지 창을 갖춘, 액체 누출 방지 및 전자레인지 사용이 가능한 디자인을 선호함에 따라, 트레이의 푸드서비스 포장 시장 규모는 2031년까지 473억 달러에 달할 가능성이 있습니다. 위변조 방지 밴드와 박리형 신선도 유지 씰은 의약품 분야에서 식품 분야로 전환되고 있어, 열성형 업체들에게 새로운 금형 수요를 창출하고 있습니다.
한때 발포 스티로폼(EPS)의 대명사였던 클램쉘 용기는 규제를 준수하기 위해 성형 섬유나 사용 후 PET 재활용 소재로 전환되고 있습니다. 한편, 소포장 봉지와 파우치는 정량 조절된 조미료의 틈새 시장을 채우고 있습니다. 2024년에 도입된 사바트(Sabart)사의 ‘Tray2Go’ 펄프 제품 라인은 퇴비화 가능성과 선반 적재 강도를 겸비하고 있어, 항공사 및 병원 케이터링 업체에 PP 트레이를 대체할 수 있는 비용 부담이 없는 대안을 제공합니다. 전반적으로, 포장 형태의 다양화는 다양한 형태의 제품 포트폴리오를 제공하는 공급업체가 외식 산업용 포장 시장에서 높은 가격으로 수주를 확보할 수 있음을 시사합니다.
지역별 분석
아시아태평양은 중국, 인도, 동남아시아 국가들의 도시 지역 소비 확대에 힘입어 40.32%의 점유율로 푸드서비스용 포장 시장을 주도하고 있습니다. 오프라인 매장과 온라인을 융합한 식품 애그리게이터의 규모가 확대됨에 따라, 각 포장 변환 업체들은 리드 타임을 단축하고 SKU를 현지 기호에 맞추기 위해 압출 성형 및 인쇄 설비를 대도시권 근처로 이전하고 있습니다. 베트남의 EPR 법안(생산자 책임 연장 제도) 초안은 재생 소재 함유율 의무화를 향한 전환이 임박했음을 보여주고 있으며, 이에 따라 RPET 플레이크 수출업체들은 국내에 세척 라인을 건설하도록 촉구하고 있습니다. 그러나 지자체 차원의 수거 체계 미비로 인해 병을 식품 용기로 전환하는 시험은 지연되고 있으며, 고온 조리용 면류 용도에서는 버진 수지 수요가 견조한 추세를 보이고 있습니다.
북미에서는 시장이 성숙해졌음에도 불구하고 혁신 주도적인 동향이 나타나고 있습니다. 주 차원의 PFAS 금지 조치가 섬유 재질 뚜껑으로의 급속한 전환을 촉진하고 있으며, 대형 수지 제조업체와 포장 가공업체 간의 화학 재활용 합작 사업을 뒷받침하고 있습니다. 뉴욕주 총무국은 현재 기준을 준수하는 섬유 용기 및 포장재에 관한 연례 조달 명세서를 공표하고 있으며, 공공 부문 구매자에게 심사를 거친 지속 가능한 SKU 목록을 제공합니다. 미국 브랜드 기업들은 경기장 매점에서 재사용 시범 사업을 선도적으로 전개하고 있으며, 세척 주기에서의 내구성과 소비자 수용도에 관한 데이터를 수집하여 2030년 제로 웨이스트 목표 수립에 활용하고 있습니다.
유럽에서는 ‘일회용 플라스틱 지침’을 통해 규제의 조화를 도모하고 있습니다. 독일과 북유럽 국가들의 보증금 환불 제도로 인해 PET 회수율이 높아지고, RPET 펠릿의 비용이 낮아지고 있습니다. 지자체 음식물 쓰레기 처리 시스템과 연계된 퇴비화 인프라에 힘입어, 섬유 코팅이 된 피자용 디스크와 성형 음료 홀더가 점차 보급되고 있습니다. 그러나 공급은 셀룰로오스 펄프의 확보 가능성에 제약을 받고 있어, 지속 가능한 임업 및 농업 폐기물을 활용한 섬유 펄프 생산에 대한 투자가 촉진되고 있습니다.
중동 및 아프리카는 현재 매출의 불과 6%에 불과하지만, 연평균 성장률(CAGR) 5.98%의 상승이 예상됩니다. KFC나 버거킹과 같은 패스트푸드 프랜차이즈 업체들은 걸프 지역 및 북아프리카에서의 매장 급속한 확장을 지원하기 위해 표준화된 포장 키트를 도입하고 있습니다. UFlex사의 2억 달러 규모 이집트 공장은 아프리카의 성장 시장과 유럽에 대한 인근 조달을 모두 대응할 수 있는 체제를 갖추고 있어, 리드 타임 단축과 홍해 항로의 운송 리스크 헤지를 실현하고 있습니다. 폐기물 처리 인프라는 여전히 발전 단계에 있기 때문에 수거 시스템이 확대될 경우 다운스트림 공정에서 기계적 재활용을 용이하게 하는 단일 소재 PP 용기에 대한 관심이 높아지고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.10According to Mordor Intelligence, the food service packaging market size is expected to grow from USD 134.20 billion in 2025 to USD 139.75 billion in 2026 and is forecast to reach USD 171.06 billion by 2031 at 4.13% CAGR over 2026-2031.
This report is Segmented by Material (Paper and Paperboard, Plastics, and More), Packaging Type (Clamshells, Cups and Tubs, and More), End-User Industry (QSR, FSR, Institutional Catering, and More), Sustainability Profile (Conventional, Sustainable), and Geography (North America, South America, Europe, Asia-Pacific, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Food Service Packaging Market Trends and Insights
Growing Demand for On-the-Go, Portion-Controlled Meals in Urban Centers
Portion-specific packs have outpaced bulk formats as younger, city-dwelling consumers favor convenient single-serve meals they can finish during short commutes. Brand owners now specify stackable trays with integrated calorie icons and scannable QR nutrition tags that fit automated vending and micro-fulfillment lockers. McDonald's pilot of grass-paper burger wraps in Germany illustrates how multinational QSR chains marry convenience with sustainability to satisfy urban diners. Institutional buyers reinforce the trend; the United Kingdom's National Health Service framework for catering consumables standardizes portion sizes while mandating allergen-compliant labels. As a result, converters that master modular die-cutting and variable-data labeling gain a cost edge while meeting complex urban service requirements.
E-commerce Meal-Kit Boom Accelerating Secondary and Tertiary Packaging Volumes
Meal-kit operators require multi-layered solutions that shield raw proteins, prevent odor transfer, and withstand two-day courier cycles. Demand has spurred investment in customized barrier pouches, corrugated coolers, and molded-fiber inserts designed to curb refrigerant use and shipping weight. Providers increasingly embed NFC freshness tags in outer cartons to signal tamper events and temperature excursions, mirroring Tetra Pak's sensor-equipped pilot for direct-to-consumer dairy in 2024. Domestic fiber molding lines have been added in the United States and Germany to curb supply risk, and Asia-Pacific manufacturers are retooling to supply water-based ink systems compatible with meal-kit ovens and microwaves.
Regulatory Phase-Outs of Single-Use EPS and PVC in More Than 60 Countries
Fast-tracked bans compress transition windows to 12-18 months, straining the capacity of alternative substrate suppliers. France's AGEC law obliged McDonald's to roll out reusable polypropylene trays in 2024, rewiring front-of-house workflows and piloting silicone-rubber containers for eat-in orders. Small operators lack the capex to overhaul back-of-house dishwashing or deposit logistics, nudging them to third-party pooling services and reinforcing consolidation toward well-capitalized chains.
Other drivers and restraints analyzed in the detailed report include:
- Quick-Service Restaurants' Shift to Fiber-Based Serviceware Amid PFAS Bans
- Recycled PET Capacity Expansions Lowering Price Premium vs. Virgin Resin
- Volatility in Virgin Polymer Prices Squeezing Converter Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics kept the largest 41.98% food service packaging market share in 2025, leveraged by cost efficiency, high-clarity display, and seal integrity that remain critical for beverage lids and hot-fill soup tubs. Still, biodegradable and specialty substrates are slated for a 5.42% CAGR, reflecting stronger eco-labeling pull and expanding compost infrastructure in urban Northern Europe. The food service packaging market size for biodegradable films is forecast to reach USD 26.36 billion by 2031, buoyed by starch blends that now tolerate microwave reheating at 100 °C without warpage. In conventional plastics, PFAS removal and chemical-recycle pathways dominate R&D budgets, evidenced by McDonald's 99.5% fluorinated-compound phase-out milestone in 2024.
Paper and paperboard continue to migrate up-market; aqueous dispersion coatings now achieve 8-hour hot-grease resistance, opening burger clam shells and noodle bowls to fiber conversion. Aluminum cans and trays preserve niche demand for airline catering and high-acid meal components but struggle against lightweight composite cartons. Glass sees negligible penetration because delivery platforms penalize weight and breakage risk. As resin volatility persists, converters hedge with hybrid PP-pulp solutions that trim polymer usage by 50% while safeguarding heat retention, reinforcing biodegradable materials as the prime innovation arena within the food service packaging market.
Cups and tubs retained a 37.89% revenue lead in 2025, anchored by universal beverage and soup applications and mega-volume QSR procurement that lowers unit costs. Nonetheless, trays and containers surge ahead at a 5.11% CAGR, supported by courier-centric menu designs. The food service packaging market size for trays could hit USD 47.30 billion by 2031 as ghost kitchens favor leak-proof, microwavable designs with snap-fit lids and anti-fog windows. Tamper bands and peel-away freshness seals migrate from pharma to food, creating incremental tooling demand for thermoformers.
Clamshells, once synonymous with EPS, reposition toward molded-fiber and post-consumer recycled PET formats to meet bans, while sachets and pouches fill portion-controlled condiment niches. Sabert's Tray2Go pulp line, introduced in 2024, pairs compostability with shelf stacking strength, giving airlines and hospital caterers a cost-neutral swap from PP trays. Overall, packaging-type diversification indicates that suppliers offering multi-format portfolios will command premium bids in the food service packaging market.
Complete Report Scope:
- By Material
- Paper and Paperboard
- Plastics
- Polyethylene Terephthalate (PET)
- Polypropylene (PP)
- Polystyrene (PS) and Expanded Polystyrene (EPS)
- Other Plastics
- Aluminum
- Glass
- Biodegradable and specialty materials
- By Packaging Type
- Clamshells
- Cups and Tubs
- Trays and Containers
- Sachets and Pouches
- Other Packaging Types
- By End-user Industry
- Quick-Service Restaurants (QSR)
- Full-Service Restaurants (FSR)
- Institutional Catering
- Hospitality and Cafes
- Other End-user Industries
- By Sustainability Profile
- Conventional Type
- Sustainable Packaging
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Vietnam
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific commands the food service packaging market with 40.32% share, fueled by expanding urban consumption in China, India, and Southeast Asian economies. As bricks-and-clicks food aggregators scale, packaging converters relocate extrusion and printing assets closer to megacities to shrink lead times and tailor SKUs to local taste profiles. Vietnam's draft EPR law signals an impending shift toward mandatory recycled-content quotas, prompting RPET flake exporters to build domestic washing lines. Yet inconsistent municipal collection slows bottle-to-food trials, keeping virgin resin demand resilient across high-temperature noodle applications.
North America displays mature yet innovation-led dynamics. State-level PFAS prohibitions catalyze rapid fiber-lid conversions and push chemical-recycling joint ventures between resin majors and packaging converters. The New York Office of General Services now publishes an annual purchasing specification for compliant fiber containers and wraps, giving public-sector buyers a vetted list of sustainable SKUs. U.S. brands pioneer pilot reuse schemes in stadium concessions, collecting data on wash-cycle durability and consumer acceptance to inform 2030 zero-waste targets.
Europe follows a harmonized regulatory path via the Single-Use Plastics Directive. Deposit-return systems in Germany and the Nordics deliver high PET collection rates, lowering RPET pellet costs. Fiber-coated pizza discs and molded drink carriers gain traction, supported by compost infrastructure integrated with municipal bio-waste streams. Supply, however, is constrained by cellulose pulp availability, spurring investments in sustainable forestry and agricultural-waste fiber pulping.
The Middle East and Africa, though only 6 % of current revenue, present a 5.98% CAGR upside. Fast-food franchisors such as KFC and Burger King deploy standardized packaging kits to support rapid outlet roll-outs in the Gulf and North Africa. UFlex's USD 200 million Egypt plant positions the firm to serve both African growth markets and European proximity sourcing, shortening lead times and hedging Red Sea shipping risks. Waste infrastructure remains nascent, prompting interest in mono-material PP tubs that facilitate downstream mechanical recycling once collection systems scale.
- Pactiv Evergreen Inc.
- Dart Container Corporation
- Amhil North America
- Genpak LLC
- Huhtamaki Oyj
- Novolex Holdings LLC
- Sabert Corporation
- Silgan Holdings Inc.
- B & R Plastics Inc.
- Graphic Packaging Holding Company
- Amcor plc
- Sonoco Products Company
- Anchor Packaging LLC
- Smurfit WestRock
- Georgia-Pacific LLC
- Coveris Holdings S.A.
- Reynolds Group Holdings Ltd.
- International Paper Company
- Vegware Ltd.
- BioPak Pty Ltd.
- Fabri-Kal Corporation
- Eco-Products LLC
- Sealed Air Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand for on-the-go, portion-controlled meals in urban centres
- 4.2.2 E-commerce meal-kit boom accelerating secondary and tertiary packaging volumes
- 4.2.3 Quick-service restaurants' shift to fiber-based serviceware amid PFAS bans
- 4.2.4 Recycled PET capacity expansions lowering price premium vs. virgin resin
- 4.2.5 Sensor-enabled "smart lids" improving delivery food safety and brand differentiation
- 4.2.6 Surge in ghost-kitchen franchising requiring lightweight, tamper-evident packs
- 4.3 Market Restraints
- 4.3.1 Regulatory phase-outs of single-use EPS and PVC in >60 countries
- 4.3.2 Volatility in virgin polymer prices squeezing converter margins
- 4.3.3 Insufficient post-consumer collection infrastructure in emerging Asia
- 4.3.4 High upfront capex for reusable food-service systems in stadiums and campuses
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS(VALUE)
- 5.1 By Material
- 5.1.1 Paper and Paperboard
- 5.1.2 Plastics
- 5.1.2.1 Polyethylene Terephthalate (PET)
- 5.1.2.2 Polypropylene (PP)
- 5.1.2.3 Polystyrene (PS) and Expanded Polystyrene (EPS)
- 5.1.2.4 Other Plastics
- 5.1.3 Aluminum
- 5.1.4 Glass
- 5.1.5 Biodegradable and specialty materials
- 5.2 By Packaging Type
- 5.2.1 Clamshells
- 5.2.2 Cups and Tubs
- 5.2.3 Trays and Containers
- 5.2.4 Sachets and Pouches
- 5.2.5 Other Packaging Types
- 5.3 By End-user Industry
- 5.3.1 Quick-Service Restaurants (QSR)
- 5.3.2 Full-Service Restaurants (FSR)
- 5.3.3 Institutional Catering
- 5.3.4 Hospitality and Cafes
- 5.3.5 Other End-user Industries
- 5.4 By Sustainability Profile
- 5.4.1 Conventional Type
- 5.4.2 Sustainable Packaging
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Vietnam
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Pactiv Evergreen Inc.
- 6.4.2 Dart Container Corporation
- 6.4.3 Amhil North America
- 6.4.4 Genpak LLC
- 6.4.5 Huhtamaki Oyj
- 6.4.6 Novolex Holdings LLC
- 6.4.7 Sabert Corporation
- 6.4.8 Silgan Holdings Inc.
- 6.4.9 B & R Plastics Inc.
- 6.4.10 Graphic Packaging Holding Company
- 6.4.11 Amcor plc
- 6.4.12 Sonoco Products Company
- 6.4.13 Anchor Packaging LLC
- 6.4.14 Smurfit WestRock
- 6.4.15 Georgia-Pacific LLC
- 6.4.16 Coveris Holdings S.A.
- 6.4.17 Reynolds Group Holdings Ltd.
- 6.4.18 International Paper Company
- 6.4.19 Vegware Ltd.
- 6.4.20 BioPak Pty Ltd.
- 6.4.21 Fabri-Kal Corporation
- 6.4.22 Eco-Products LLC
- 6.4.23 Sealed Air Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment