|
시장보고서
상품코드
2122177
인도의 의약품 포장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)India Pharmaceutical Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
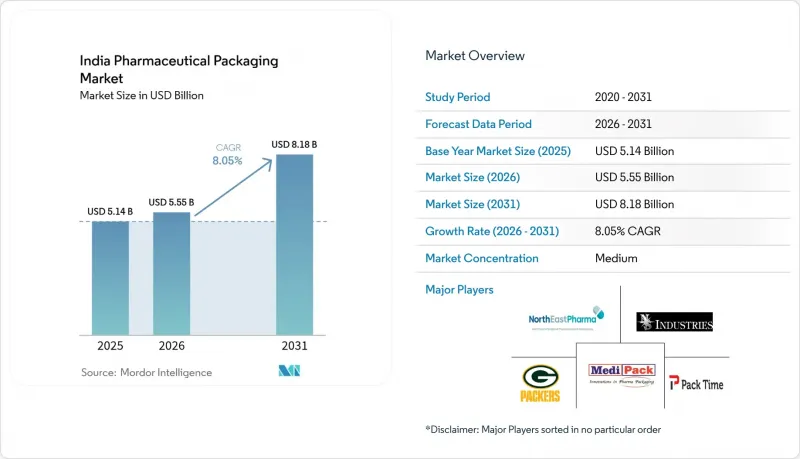
에 따르면 인도의 의약품 포장 시장 규모는 2025년에 51억 4,000만 달러로 평가되며, 2026년 55억 5,000만 달러에서 2031년까지 81억 8,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 8.05%에 달할 전망입니다.
이 보고서는 소재 유형(플라스틱, 유리, 금속 등), 제품 유형(병, 바이알 및 앰플, 블리스터 팩 등), 포장 단계(1차, 2차, 3차), 최종사용자 산업(제약 제조사, 수탁 포장 업체 등)별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
인도 의약품 포장 시장의 동향 및 인사이트
인도의 백신 및 바이오의약품 충전·마무리 능력 확대
인도가 세계적인 바이오의약품 허브가 되겠다는 야망이 특수 용기 및 포장재에 대한 수요를 견인하고 있습니다. 론자(Lonza)가 레와리(Rewari)에 건설 중인 젤라틴 캡슐 생산 라인을 비롯한 지속적인 투자에는 멸균을 견디고 장거리 물류 체인을 통해 영하의 온도에서도 안정성을 유지할 수 있는 고차단 필름이 요구됩니다. 온도 표시기가 내장된 콜드 체인 포장의 성장으로 인해 제조 공장에서 환자에 이르기까지 제품의 무결성이 끊김 없이 유지되고 있습니다. 또한 바이오의약품 개발 기업은 공급망의 가시화를 위해 무단 개봉 방지 실 및 단위별 일련번호 부여를 중시하고 있으며, 이에 따라 각 컨버터 기업은 ISO-8 클린룸에서의 생산 규모를 확대하도록 촉진되고 있습니다.
수출 지향형 제약 업계를 위한 정부의 PLI 및 GMP 업그레이드
생산 연계형 인센티브(PLI) 제도에서는 2025-26 회계연도에 2,444.93 카롤 인도 루피(2억 9,300만 달러)가 배정되어, 포장 인프라의 체계적인 업그레이드를 추진함과 동시에,FDA 21 CFR 211.132 및 EU의 FMD 일련번호 부여 요건에 대한 동시 준수를 지원하고 있습니다. 보조금 신청자는 야심찬 수출 목표를 달성해야 합니다. 이를 통해 고급 라미네이트 호일, 위조 방지 캡, 클라우드 연결형 외관 검사 장비에 대한 수주로 이어질 것입니다. 2025년 12월 GMP 개보수 마감 기한에 따라 각 시설은 ISO-8 규격에 부합하는 생산 라인을 도입할 수밖에 없게 되었으며, 검증 완료된 1차 포장재 및 클린룸용 소모품에 대한 지속적인 수요가 증가하고 있습니다.
의료용 등급 폴리머 및 유리 원료 비용 변동
2025년, 폴리프로필렌 가격은 CFR 인도 기준 1미터톤당 970-990달러 사이에서 변동하여, 컨버터의 이익률을 압박하는 동시에 계약 가격 책정을 복잡하게 만들었습니다. 유리 용기 제조업체들은 에너지 요금 급등과 규사 부족에 직면해 있으며, 고부가가치 바이알에 대한 원가 전가가 증가하고 있습니다. 연포장 부문의 2024-25 회계연도 EBITDA 마진은 수지 공급 과잉과 수출 수요 부진으로 인해 8%까지 하락했습니다. 이러한 요인으로 인해 포장 제조업체들은 수익성을 유지하기 위해 원자재 헤지 및 배합 최적화를 불가피하게 추진하고 있습니다.
부문별 분석
2025년에는 플라스틱이 매출의 40.85%를 차지하며 1위를 유지했으나, 복합 소재 및 바이오 기반 수지는 연평균 성장률(CAGR) 9.65%로 급증하며 모든 소재 중 가장 높은 성장률을 보였습니다. 엄격한 확대 생산자 책임(EPR) 기준에 따라 재활용 PET 인서트 및 사탕수수 유래 HDPE 제품 라인의 시범 도입이 촉진되고 있습니다. 제약 기업의 구매 담당자들은 추출물 및 용출물에 대한 완전한 검증을 요구하고 있으며, 이에 따라 각 컨버터 기업은 애플리케이션 연구소를 구축하고 규제 대응 마스터 파일 확보를 추진하고 있습니다. 인도의 의약품 포장 시장에서 바이오 기반 소재 시장 규모는 수탁 포장 업체들이 다국적 스폰서 기업에게 친환경 노력을 어필함에 따라 급속히 확대될 전망입니다. 또한 효소를 이용한 박리 기술에 대한 병행 투자를 통해 무균 카톤에서 알루미늄 층을 회수할 수 있을 것으로 예상되며, 이는 혁신의 깊이를 보여줍니다. 향후 성장은 고순도 재생 원료를 공급하는 견고한 공급망과 각국에서 통일된 시험 기준에 달려 있습니다.
지속가능성이라는 주제는 유리 및 금속 수요에도 변화를 가져오고 있습니다. 붕규산 유리 바이알은 비활성 특성으로 인해 바이오의약품 분야에서 여전히 중요성을 유지하고 있지만, 경량 코팅 유리 바이알은 용융시 에너지 절감을 목적으로 합니다. 알루미늄 접이식 튜브는 용출 제로의 차단성과 재활용 가능성이라는 두 가지 장점 덕분에 외용제 제제에 사용되고 있습니다. 수성 코팅이 95%의 내습성을 실현함에 따라 2차 포장용 골판지가 다시 주목받고 있으며, 이는 환자 안전을 확보하는 동시에 섬유 회수도 가능하게 하고 있습니다. 이러한 변화는 전반적으로 인도 의약품 포장 시장 전체에서 소재 관리에 대한 인식이 높아지고 있음을 반영합니다.
2025년 매출에서 병이 차지하는 비중은 21.05%였으나, 파우치와 백은 연평균 성장률(CAGR) 9.1%를 기록하며 모든 카테고리 중 가장 빠른 성장률을 보였습니다. 이는 온라인 약국의 소포 배송 확대가 지원하고 있습니다. 인도 의약품 포장 시장에서 프리필드 주사기의 점유율은 바이오의약품의 보급에 따라 상승하고 있으며, 실리콘 오일이 포함되지 않은 플런저와 엄격한 입자 관리가 요구되고 있습니다. 한편, 블리스터 팩의 개선에서는 어린이가 열기 어려운 푸시스루식 뚜껑과, 환자를 처방전 재충전 포털로 연결해 주는 NFC 태그에 초점이 맞춰지고 있습니다. 스마트 기능은 플렉서블 파우치에도 도입되어, 재택 복용 준수 상황을 모니터링하기 위한 습도 센서가 내장되어 있습니다.
하류 시장에서는 신속 검사용 면봉 키트 및 비강 스프레이의 수요 확대에 따라 스냅핏식 캡, 일체형 드롭퍼, 데드 볼륨이 적은 밸브에 대한 수요가 증가하고 있습니다. 턴키 성형과 펄스 광살균을 함께 제공하는 컨버터는 린(Lean) 공급망이 극히 중요한 프로젝트에서 수주를 확보하고 있습니다. 인도 의약품 포장 시장에서 적응형 캡 시장 규모는 맞춤형 치료용 포장 및 마이크로 도징 기기의 증가에 따라 확대될 것으로 예측됩니다. 그 결과 발생하는 SKU의 복잡화는 소량 디지털 인쇄 및 신속한 생산 전환이 가능한 기업에 유리하게 작용합니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, the India pharmaceutical packaging market size was valued at USD 5.14 billion in 2025 and estimated to grow from USD 5.55 billion in 2026 to reach USD 8.18 billion by 2031, at a CAGR of 8.05% during the forecast period (2026-2031).
This report is Segmented by Material Type (Plastic, Glass, Metal, and More), Product Type (Bottles, Vials and Ampoules, Blister Packs and More), Packaging Level (Primary, Secondary, and Tertiary), End-User Industry (Pharmaceutical Manufacturing Companies, Contract Packaging Organizations, and More). The Market Forecasts are Provided in Terms of Value (USD).
India Pharmaceutical Packaging Market Trends and Insights
Expansion of India's Vaccine and Biologics Fill-Finish Capacity
India's ambition to become a global biologics hub is fueling specialized containment demand. Ongoing investments, including Lonza's gelatin capsule line in Rewari, require high-barrier films that withstand sterilization and maintain sub-zero stability across extended logistics chains. Growth in cold-chain packaging with integrated temperature indicators is enabling uninterrupted product integrity from plant to patient. Biologic developers also favor tamper-evident seals and unit-level serialization for supply chain visibility, encouraging converters to scale ISO-8 clean-room production.
Government PLI and GMP Upgrades for Export-Oriented Pharma
The Production-Linked Incentive scheme earmarked INR 2,444.93 crore (USD 293 million) for FY 2025-26, driving systematic upgrades in packaging infrastructure and supporting simultaneous compliance with FDA 21 CFR 211.132 and EU FMD serialisation requirements. Subsidy applicants must meet ambitious export targets, which translate into orders for premium laminated foils, tamper-proof closures, and cloud-connected vision inspection units. The December 2025 GMP upgrade deadline compels facilities to install ISO-8 compatible lines, raising recurring demand for validated primary packs and cleanroom consumables.
Volatility in Medical-Grade Polymer and Glass Input Costs
Polypropylene fluctuated between USD 970-990 per metric ton CFR India in 2025, eroding converter margins and complicating contract pricing. Glass container makers face rising energy tariffs and silica sand shortages, adding pass-through costs for high-value vials. Overall EBITDA margins for flexible packaging dipped to 8% in FY 2024-25 amid resin oversupply and lukewarm export demand. These factors force packaging firms to hedge raw materials and optimize formulations to cushion profitability.
Other drivers and restraints analyzed in the detailed report include:
- E-Pharmacy Boom Driving Tamper-Evident, Home-Delivery Packs
- Sustainability Mandates Pushing rPET and PCR Rigid Plastics
- Single-Use-Plastic EPR and Recycling Logistics Gaps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, plastics led with 40.85% revenue, yet composites and bio-based resins surged at a 9.65% CAGR, the highest among all materials. Stringent Extended Producer Responsibility norms are spurring trials of recycled PET inserts and sugarcane-based HDPE lines. Pharmaceutical buyers insist on full extractable-leachable validation, prompting converters to build application labs and secure regulatory master files. India's pharmaceutical packaging market size for bio-based materials is set to expand quickly as contract packers market greener credentials to multinational sponsors. Parallel investments in enzymatic delamination promise recovery of aluminum layers from aseptic cartons, illustrating innovation depth. Future growth depends on a robust supply chain for high-purity recycled feedstock and harmonized national testing standards.
Sustainability themes also reshape glass and metal demand. Borosilicate vials retain relevance for biologics owing to inertness, yet lightweight coated glass variants target energy reductions during melt. Aluminum collapsible tubes find use in topical formulations where zero-leach barriers and recyclability offer dual appeal. Paperboard is regaining favor for secondary cartons as water-based coatings achieve 95% humidity resistance, satisfying patient safety while enabling fiber recovery. Collectively these shifts reflect heightened material stewardship across the India pharmaceutical packaging market.
Bottles commanded 21.05% of 2025 revenue, yet pouches and bags logged a 9.1% CAGR, the fastest among all categories, fueled by e-pharmacy parcel shipping. India's pharmaceutical packaging market share for prefilled syringes is climbing as biologic therapies proliferate, demanding silicon-oil-free plungers and tight particulate controls. Meanwhile, blister-pack upgrades focus on child-resistant push-through lidding and NFC tags that connect patients to refill portals. Smart features migrate into flexible sachets, embedding humidity sensors for at-home adherence monitoring.
Downstream, rapid swab kits and nasal sprays push demand for snap-fit caps, integrated droppers, and low-dead-volume valves. Converters offering turnkey molding plus pulsed-light sterilization win contracts where lean supply chains are pivotal. India pharmaceutical packaging market size for adaptive closures is projected to widen as personalized therapy packs and micro-dosing devices multiply. The resulting SKU complexity rewards firms capable of short-run digital printing and agile changeovers.
Complete Report Scope:
- By Material Type
- Plastic
- High-Density Polyethylene (HDPE)
- Low-Density Polyethylene (LDPE)
- Polyethylene Terephthalate (PET)
- Other Plastics
- Glass
- Metal
- Paper and Paperboard
- Composites/ Bio-based Materials
- Plastic
- By Product Type
- Bottles
- Vials and Ampoules
- Blister Packs
- Prefilled Syringes and Cartridges
- Tubes
- Caps and Closures
- Pouches and Bags
- Labels
- Other Product Types
- By Packaging Level
- Primary
- Secondary
- Tertiary
- By End-user Industry
- Pharmaceutical Manufacturing Companies
- Contract Packaging Organizations
- Retail and Institutional Pharmacies
- Hospitals and Clinics
- Other End-user Industries
List of Companies Covered in this Report:
- Amcor plc
- West Pharmaceutical Services Inc.
- Huhtamaki Oyj ( Huhtamaki India Ltd )
- Uflex Limited
- Gerresheimer AG
- Schott AG ( Schott Glass India Pvt Ltd )
- SGD S.A. ( SGD Pharma India Ltd )
- EPL Limited ( Essel Propack Ltd )
- Parekhplast India Ltd
- Hoffmann Neopac AG
- Medipack Innovations Pvt Ltd
- Packtime Innovations Pvt Ltd
- Manjushree Technopack Ltd
- Graham Blow Pack Pvt Ltd
- Regent Plast Pvt Ltd
- North East Pharmapack Pvt Ltd
- TPAC Packaging India Pvt Ltd
- JK Print Packs
- N S Industries
- A S Packers
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated shift to pre-fillable formats post-COVID-19
- 4.2.2 Expansion of India's vaccine and biologics fill-finish capacity
- 4.2.3 Government PLI and GMP upgrades for export-oriented pharma
- 4.2.4 E-pharmacy boom driving tamper-evident, home-delivery packs
- 4.2.5 Sustainability mandates pushing rPET and PCR rigid plastics
- 4.3 Market Restraints
- 4.3.1 Volatility in medical-grade polymer and glass input costs
- 4.3.2 Single-use-plastic EPR and recycling logistics gaps
- 4.3.3 High cap-ex for ISO-8 clean-room packaging lines
- 4.3.4 Fragmented downstream distribution inflating unit pack costs
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
- 4.6 The Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Plastic
- 5.1.1.1 High-Density Polyethylene (HDPE)
- 5.1.1.2 Low-Density Polyethylene (LDPE)
- 5.1.1.3 Polyethylene Terephthalate (PET)
- 5.1.1.4 Other Plastics
- 5.1.2 Glass
- 5.1.3 Metal
- 5.1.4 Paper and Paperboard
- 5.1.5 Composites/ Bio-based Materials
- 5.1.1 Plastic
- 5.2 By Product Type
- 5.2.1 Bottles
- 5.2.2 Vials and Ampoules
- 5.2.3 Blister Packs
- 5.2.4 Prefilled Syringes and Cartridges
- 5.2.5 Tubes
- 5.2.6 Caps and Closures
- 5.2.7 Pouches and Bags
- 5.2.8 Labels
- 5.2.9 Other Product Types
- 5.3 By Packaging Level
- 5.3.1 Primary
- 5.3.2 Secondary
- 5.3.3 Tertiary
- 5.4 By End-user Industry
- 5.4.1 Pharmaceutical Manufacturing Companies
- 5.4.2 Contract Packaging Organizations
- 5.4.3 Retail and Institutional Pharmacies
- 5.4.4 Hospitals and Clinics
- 5.4.5 Other End-user Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 West Pharmaceutical Services Inc.
- 6.4.3 Huhtamaki Oyj ( Huhtamaki India Ltd )
- 6.4.4 Uflex Limited
- 6.4.5 Gerresheimer AG
- 6.4.6 Schott AG ( Schott Glass India Pvt Ltd )
- 6.4.7 SGD S.A. ( SGD Pharma India Ltd )
- 6.4.8 EPL Limited ( Essel Propack Ltd )
- 6.4.9 Parekhplast India Ltd
- 6.4.10 Hoffmann Neopac AG
- 6.4.11 Medipack Innovations Pvt Ltd
- 6.4.12 Packtime Innovations Pvt Ltd
- 6.4.13 Manjushree Technopack Ltd
- 6.4.14 Graham Blow Pack Pvt Ltd
- 6.4.15 Regent Plast Pvt Ltd
- 6.4.16 North East Pharmapack Pvt Ltd
- 6.4.17 TPAC Packaging India Pvt Ltd
- 6.4.18 JK Print Packs
- 6.4.19 N S Industries
- 6.4.20 A S Packers
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment