|
시장보고서
상품코드
2122225
첨단 인증 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Advanced Authentication - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 따르면 첨단 인증 시장 규모는 2025년 177억 1,000만 달러에서 2026년에는 205억 6,000만 달러로 확대하며, 2031년까지 382억 3,000만 달러에 달할 것으로 예상되고 있으며, 2026-2031년에 CAGR 13.21%로 성장할 것으로 전망되고 있습니다.
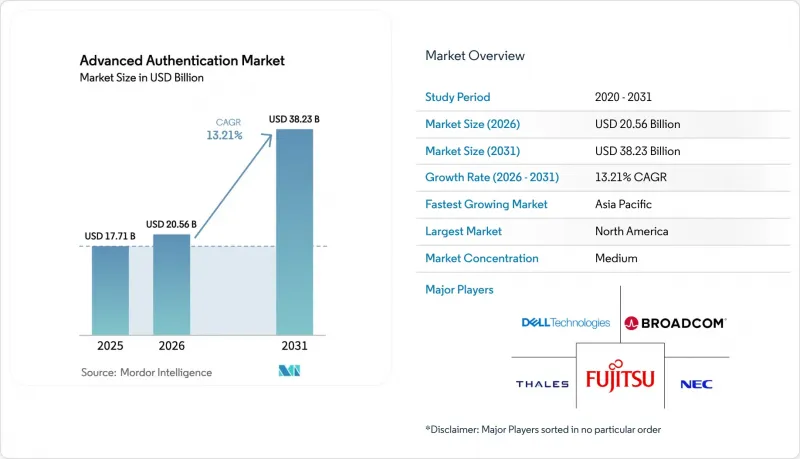
이 보고서는 구성 요소(하드웨어, 소프트웨어, 서비스), 인증 방식(스마트 카드, 생체 인증 등), 인증 모델(2단계 인증(2FA), 위험 기반 인증 등), 배포 모드(온프레미스, 클라우드), 최종사용자 산업(정부(민간), 국방 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
글로벌 고도 인증 시장의 동향 및 인사이트
클라우드 배포의 급증으로 제로 트러스트 아키텍처가 가속화
퍼블릭 클라우드로 워크로드를 이전하는 기업은 기존의 네트워크 경계 방어가 더 이상 통하지 않는다는 사실을 깨닫게 되었고, 그 결과 신원 확인이 주요 통제 지점이 되었습니다. 미국 사이버보안 및 인프라 보안국(CISA)은 2024년에 제로 트러스트 성숙도 모델을 발표하고, 피싱 공격에 내성이 있는 인증 정보와 지속적인 검증을 그 기반으로 삼았습니다. 클라우드 제공업체는 기밀 리소스에 대한 액세스 요청이 있을 때마다 단계별 인증 요청을 트리거하는 게이트웨이를 통해 인증 기능을 제공하고 있으며, 마이크로소프트의 ‘2025년 디지털 방어 보고서’에 따르면 이를 통해 침해시 횡방향 이동을 70% 감소시켰습니다. 다중 테넌트형 SaaS(Software-as-a-Service) 애플리케이션은 각 테넌트가 별도의 설정이 필요 없이 정책에 기반한 세밀한 인증을 필요로 하므로 수요가 더욱 확대되고 있습니다. 인증 플랫폼과 클라우드 액세스 보안 브로커(CASB)의 통합이 주류를 이루고 있으며, ID 계층과 네트워크 계층에 걸친 사용자 컨텍스트에 대한 통합적인 관점이 형성되고 있습니다. 그 결과, 구매 결정시 개별 온프레미스형 게이트웨이에 의존하기보다는 위험 신호를 클라우드 애플리케이션의 워크플로우에 직접 통합할 수 있는 벤더가 점점 더 많이 선택되고 있습니다.
증가하는 보안 침해 비용과 사이버 보험료
2024년 데이터 침해로 인한 평균 비용은 488만 달러에 달했으며, 사고의 16%에서 인증 정보 유출이 관련되어 있었습니다. 이에 대응하여 사이버 보험 인수사는 보험 계약 발급 및 갱신에 앞서 특권 계정 및 원격 계정에 대한 다단계 인증을 의무화함으로써, 인증은 단순한 선택적 기능 강화에서 보상을 받기 위한 필수 요건으로 변모했습니다. 기업은 현재 인증에 대한 투자와 잠재적인 보험료 인상, 규제 당국의 과징금을 저울질하며 검토하고 있습니다. 후자의 경우, 2024년 일반 데이터 보호 규정(GDPR)에 따라 총 16억 유로(17억 달러)에 달했습니다. 재정적 계산은 명백합니다. 인증 현대화를 소홀히 하면 정보 유출 위험이 높아질 뿐만 아니라 직접적인 비용 증가도 초래하게 됩니다. 그 결과, 과거에는 예산 제약으로 인해 업그레이드를 미루던 중견 기업도 보험 가입 자격과 규정 준수를 유지하기 위해 도입을 가속화하고 있습니다.
고액의 업그레이드 및 토큰 교체 비용
기존의 일회용 비밀번호(OTP) 토큰을 최신 인증 방식으로 교체할 경우, 조달, 등록, 지원 비용을 포함하면 사용자 1인당 50-100달러의 비용이 발생할 수 있습니다. 이전에는 대개 컨설팅 계약이 필요하며, 중규모 도입의 경우에도 그 비용이 약 20만 달러에 달하므로 비용에 민감한 업계에서는 예산에 부담이 가중됩니다. Identity Defined Security Alliance의 조사 데이터에 따르면 기업의 38%가 정보 유출 위험을 인식하고 있음에도 불구하고 도입의 주요 장벽으로 비용을 꼽고 있습니다. 구독형 클라우드 서비스는 설비 투자의 일부를 상쇄해 주지만, 초기 마이그레이션 비용은 여전히 단기 예산에 부담이 되며, 특히 IT 지출이 엄격하게 제한되는 신흥 국가에서는 그 영향이 두드러집니다.
부문 분석
고급 인증 시장의 서비스 매출은 2031년까지 연평균 13.83%의 성장률을 보일 것으로 예측됩니다. 이는 구매자들이 사내 팀이 복잡한 업무에서 해방될 수 있도록 정책 설계, 통합 및 연중무휴 24시간 모니터링을 외부에 위탁하는 것을 선호하는 경향을 반영한 것입니다. 클라우드 ID 제품군에는 인증, 거버넌스 및 분석 기능이 단일 콘솔에 통합되어 있으므로 2025년 매출의 47.89%는 여전히 소프트웨어가 차지할 것으로 보입니다. 스마트 카드 리더기나 생체인식 스캐너와 같은 하드웨어는 에어 갭 방어 및 중요 인프라에 여전히 필수적이지만, 비밀번호가 필요 없는 모바일 인증 정보가 보급됨에 따라 그 성장세는 둔화되고 있습니다. 병원들은 이러한 서비스로의 전환을 여실히 보여주고 있습니다. 컨설턴트가 복잡한 임상 업무를 최소 권한 접근 규칙에 매핑하고, 감사 대응이 가능한 보고서를 보장하는 관리형 운영을 시행하고 있습니다. 기업이 성숙해짐에 따라 초기 기술 라이선스보다 지속적인 최적화에서 부가가치를 발견하고, 지출 비중을 관리형 보안 서비스 제공업체로 전환하고 있습니다.
이러한 추세는 고도 인증 시장에서 부가가치 서비스의 점유율이 앞으로도 계속 확대될 것임을 시사합니다. 클라우드 벤더는 지원 시간, 규정 준수 템플릿, 오케스트레이션 플레이북을 묶은 모듈형 구독 서비스를 제공함으로써 이러한 전환을 지원하고 있으며, 제품과 서비스의 경계를 모호하게 만들고 있습니다. 시스템 통합사업자 또한 인증을 보다 광범위한 제로 트러스트 도입과 패키지로 묶어 서비스에 대한 수요를 더욱 가속화하고 있습니다. 반면, 하드웨어 업데이트는 주기적이며 그 범위도 제한적이기 때문에 총 지출에서 차지하는 비중은 유지될 뿐, 확대되지는 않고 있습니다. 따라서 경쟁 우위는 개별 기능이 아니라 전문 지식과 성과 기반 계약에 있습니다.
2025년 매출 중 생체 인증이 55.72%를 차지했으나, 지역별 개인정보 보호 규제와 시장 포화로 인해 신규 도입이 억제되면서 성장이 둔화되고 있습니다. 반면, 행동 분석은 기세를 더해 14.47%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 이는 키 입력, 마우스 움직임, 내비게이션 분석과 같은 수동적인 기법을 통해 워크플로우를 중단하지 않고도 사용자를 지속적으로 인증할 수 있기 때문입니다. 은행들은 행동 위험 점수를 부정 탐지 엔진에 통합하여 실시간으로 계정 탈취를 방지하는 동시에 고객 유지율 향상을 도모하고 있습니다. 지문 센서는 스마트폰에서는 여전히 널리 보급되어 있지만, 산업용이나 의료 현장에서는 장갑 착용, 습기, 주변 조명으로 인해 정확도가 떨어지기 때문에 멀티모달 인증이나 행동 인증에 대한 관심이 높아지고 있습니다. 얼굴 인증에 대해서는 시장에 따라 반응이 엇갈리고 있는데, 아시아태평양 일부에서는 규제 측면에서 우대 조치를 받고 있는 반면, 유럽의 일반 데이터 보호 규정(GDPR) 하에서는 저항에 직면하고 있습니다.
그 결과, 기업이 헬프데스크 문의를 최소화하는 ‘마찰 없는’ 보안을 추구하는 가운데, 행동 분석은 고도화된 인증 시장에서 점유율을 확대하고 있습니다. 각 벤더는 독자적인 기계학습 모델을 통해 차별화를 꾀하고 있으며, 이를 통해 기준선을 신속하게 개인화하고 사용자의 미세한 변화에 적응함으로써 보안과 사용자 경험 모두를 향상시키고 있습니다. 도입이 진행됨에 따라 범용 생체 인증 하드웨어에 대한 가격 압박이 커지고 있으며, 공급업체들은 분석 및 오케스트레이션 서비스를 번들로 제공하도록 유도되고 있습니다. 장기적인 추세로는 생체 인증이 높은 신뢰성이 요구되는 사용 사례를 지원하고, 행동 분석이 지속적인 검증의 공백을 메우는 공생 관계가 시사되고 있습니다.
지역별 분석
북미는 연방 정부 기관에서 민간 기업으로 확산된 초기 제로 트러스트 구상에 힘입어 2025년 매출의 38.91%를 차지했습니다. 행정관리예산국(OMB)의 각서 M-22-09에서는 정부 기관에 피싱 공격에 내성이 있는 인증 도입을 의무화했으며, 주 및 지방 정부도 곧 연방 정부의 조달 관행을 따랐습니다. 캐나다는 2024년에 개인정보 보호법을 개정하여 데이터 침해에 대한 징벌적 벌금을 도입함으로써, 기업의 다단계 인증 및 비밀번호 없는 솔루션에 대한 투자를 촉진했습니다. 멕시코에서는 핀테크 규제로 인해 은행 업계에서의 도입이 가속화되었으나, 예산 제약으로 인해 데이터 침해 건수가 증가하고 있음에도 불구하고 다른 부문에서의 확산은 주춤했습니다.
유럽에서는 일반 데이터 보호 규정(GDPR)의 설명 책임 원칙에 따라 입증 가능한 기술적 조치의 이동이 의무화되어 있을 뿐만 아니라, 디지털 운영 복원력법(DORA)이 금융 서비스를 대상으로 적응형 인증을 명시적으로 규정하고 있으며, 여전히 중요한 존재감을 유지하고 있습니다. 독일의 중요 인프라에 관한 기술 지침과 영국의 비밀번호 없는 인증 추진도 수요를 더욱 지원하고 있습니다. 러시아에서는 인증 정보의 저장을 로컬 서버에 의무화하고 있으며, 다국적 기업의 클라우드 배포을 복잡하게 만들고 있습니다.
아시아태평양은 2031년까지 연평균 14.24%의 성장이 예상되며, 이는 지역별로는 가장 높은 성장률입니다. 중국의 ‘사이버 보안법’ 개정에 따라 중요 정보 인프라 운영 사업자에게 다중 요소 인증이 의무화되었습니다. 한편, 인도의 ‘아드하르(Aadhaar)’ 프로그램에서는 매달 20억 건 이상의 생체 인증 처리가 이루어지고 있으며, 공공 부문 및 민간 부문 전반에 걸쳐 비밀번호 없는 로그인이 정착되고 있습니다. 일본의 개인정보보호법 개정과 한국의 금융 가이드라인에 따라 현지 규정 준수 요건이 강화되면서, 기업은 상황에 맞는 솔루션 도입을 서두르고 있습니다. 호주의 ‘에센셜 에이트(Essential Eight)’ 프레임워크에서는 다중 인증이 ‘권장’에서 ‘의무’로 격상되어, 정부 및 중요 인프라 분야의 지출에 영향을 미치고 있습니다.
중동 및 아프리카에서는 도입 현황에 편차가 나타납니다. 아랍에미리트(UAE)는 정부 포털 사이트에 인증 기준을 적용하고 있는 반면, 사우디아라비아의 ‘필수 사이버 보안 대책(Essential Cybersecurity Controls)’에서는 중요 부문에서 다중 인증이 의무화되어 있습니다. 남아프리카공화국은 ‘개인정보보호법’에 따라 합리적인 보안 조치의 이동을 의무화하고 있으나, 그 이동 상황은 산업 분야별로 차이가 있습니다. 남미에서는 브라질이 중심이 되고 있으며, 해당 국가의 오픈 뱅킹 규제에서는 강력한 고객 인증이 의무화되어 있지만, 다른 경제권에서는 재정적 역풍으로 인해 도입이 지연되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, the advanced authentication market size is expected to increase from USD 17.71 billion in 2025 to USD 20.56 billion in 2026 and reach USD 38.23 billion by 2031, growing at a CAGR of 13.21% over 2026-2031.
This report is Segmented by Component (Hardware, Software, Services), Authentication Method (Smart Cards, Biometrics, and More), Authentication Model (Two-Factor Authentication (2FA), Risk-Based Authentication, and More), Deployment Mode (On-Premise, and Cloud), End-User Industry (Government (Civil), Defense, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Advanced Authentication Market Trends and Insights
Surging Cloud Adoption Driving Zero-Trust Architectures
Enterprises shifting workloads into public clouds discovered that traditional network perimeter defenses no longer apply, so identity verification became the primary control point. The U.S. Cybersecurity and Infrastructure Security Agency issued a zero-trust maturity model in 2024, positioning phishing-resistant credentials and continuous validation as foundational pillars. Cloud providers expose authentication through gateways that trigger step-up challenges whenever sensitive resources are requested, trimming lateral movement in breaches by 70% according to Microsoft's 2025 Digital Defense Report. Multi-tenant software-as-a-service applications further amplify demand, as each tenant requires granular, policy-driven authentication without bespoke configuration. Integration between authentication platforms and cloud access security brokers is becoming mainstream, creating a unified view of user context across identity and network layers. As a result, purchase decisions increasingly favor vendors that can embed risk signals directly into cloud application workflows rather than rely on separate on-premise gateways.
Rising Security Breach Costs and Cyber-Insurance Premiums
The average data breach cost hit USD 4.88 million in 2024, with compromised credentials implicated in 16% of incidents. Cyber-insurance underwriters reacted by mandating multi-factor authentication on privileged and remote accounts before issuing or renewing policies, transforming authentication from an optional enhancement into a prerequisite for coverage. Enterprises now weigh authentication investments against potential premium surcharges and regulatory fines, the latter totaling EUR 1.6 billion (USD 1.7 billion) under the General Data Protection Regulation in 2024. The financial calculus is clear: failing to modernize authentication not only elevates breach risk but also drives direct cost increases. Consequently, mid-market organizations that once delayed upgrades due to budget limitations are accelerating adoption to maintain insurability and compliance.
High Upgrade and Token Replacement Costs
Replacing legacy one-time-password tokens with modern credentials can cost USD 50-100 per user when procurement, enrollment, and support are factored in. Migration often requires consulting engagements priced at around USD 200,000 for mid-sized deployments, putting pressure on budgets in cost-sensitive sectors. Survey data from the Identity Defined Security Alliance showed that 38% of enterprises cited cost as the main barrier to adoption, despite recognizing breach risks. Subscription cloud services offset some capital outlay, yet the initial transition still weighs on short-term budgets, particularly in emerging economies where IT spend is tightly constrained.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated Remote Workforce After 2025
- Mandatory Multi-Factor Authentication Compliance in Regulated Sectors
- Interoperability Gaps Across Legacy Infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services revenue within the advanced authentication market is projected to expand at 13.83% annually through 2031, reflecting buyers' preference for outsourced policy design, integration, and 24/7 monitoring that relieve internal teams of the complexity. Software still accounted for 47.89% of 2025 revenue because cloud identity suites embed authentication, governance, and analytics into a single console. Hardware, including smart-card readers and biometric scanners, remains essential for air-gapped defense and critical infrastructure, yet its growth lags as passwordless mobile credentials proliferate. Hospitals illustrate the pivot toward services: consultants map intricate clinical roles to least-privilege access rules, then run managed operations that guarantee audit-ready reporting. As enterprises mature, they see incremental value in continuous optimization rather than in the initial technology license, shifting wallet share to managed security service providers.
This tilt underscores how the advanced authentication market share for value-added services will keep widening. Cloud vendors encourage the shift by offering modular subscriptions that bundle support hours, compliance templates, and orchestration playbooks, blurring the line between product and service. Systems integrators also package authentication with broader zero-trust rollouts, further accelerating demand for services. Meanwhile, hardware refreshes stay cyclical and narrowly scoped, sustaining but not expanding their portion of total spend. The competitive edge, therefore, lies in domain expertise and outcome-based contracts rather than point features.
Biometrics accounted for 55.72% of 2025 revenue, yet growth is decelerating as regional privacy constraints and market saturation curb new deployments. Behavioral analytics adds momentum, recording the fastest 14.47% CAGR, as passive keystroke, mouse movement, and navigation analysis authenticate users continuously without interrupting workflow. Banks integrate behavioral risk scores into fraud engines, preventing account takeover in real time and improving customer retention. Fingerprint sensors remain ubiquitous on smartphones, but gloves, moisture, and ambient light reduce accuracy in industrial and healthcare settings, prompting interest in multimodal or behavioral options. Facial recognition divides markets, enjoying favorable regulation in parts of the Asia-Pacific while meeting resistance under Europe's General Data Protection Regulation.
Behavioral analytics, therefore, captures a growing share of the advanced authentication market as enterprises seek frictionless security that minimizes helpdesk calls. Vendors differentiate through proprietary machine-learning models that quickly personalize baselines and adapt to subtle user shifts, enhancing both security and the user experience. As adoption climbs, pricing pressure on commodity biometric hardware intensifies, nudging suppliers to bundle analytics and orchestration services. The long-term trajectory suggests coexistence, with biometrics anchoring high-assurance use cases and behavior filling continuous verification gaps.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Authentication Method
- Smart Cards
- Biometrics
- Fingerprint Recognition
- Iris and Retina Recognition
- Facial Recognition
- Voice Recognition
- Mobile Smart Credentials
- Tokens
- User-based Public Key Infrastructure
- Behavioral Analytics
- By Authentication Model
- Two-Factor Authentication (2FA)
- Multi-Factor Authentication (MFA)
- Continuous and Adaptive Authentication
- Risk-Based Authentication
- By Deployment Mode
- On-Premise
- Cloud
- By End-user Industry
- Banking, Financial Services and Insurance (BFSI)
- Healthcare and Life Sciences
- Government (Civil)
- Defense
- IT and Telecom
- Retail and eCommerce
- Energy and Utilities
- Transportation and Logistics
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 38.91% of 2025 revenue as early zero-trust initiatives rippled from federal agencies to commercial enterprises. The Office of Management and Budget memorandum M-22-09 required government entities to deploy phishing-resistant authentication, and state and local administrations soon mirrored federal procurement practices. Canada updated its privacy law in 2024, introducing punitive breach fines that boosted enterprise investment in multi-factor and passwordless solutions. Although Mexico's fintech regulations accelerated adoption in banking, budget constraints slowed rollouts in other sectors despite rising breach activity.
Europe maintains a meaningful presence as the General Data Protection Regulation's accountability principle obliges the implementation of demonstrable technical controls, and the Digital Operational Resilience Act explicitly prescribes adaptive authentication for financial services. Germany's technical guidelines for critical infrastructure and the United Kingdom's push toward passwordless verification further anchor demand. Russia enforces local-server requirements for credential storage, complicating multinationals' cloud adoption.
Asia-Pacific is projected to grow at 14.24% through 2031, the highest regional rate. China's Cybersecurity Law amendments mandate multi-factor authentication for critical information infrastructure operators, while India's Aadhaar program processes over 2 billion biometric verifications monthly, normalizing passwordless login across public and private sectors. Japan's privacy amendments and South Korea's financial guidelines intensify local compliance requirements, driving enterprises toward adaptive solutions. Australia's Essential Eight framework upgraded multi-factor authentication from recommended to mandatory, influencing government and critical-infrastructure spending.
The Middle East and Africa show uneven adoption. The United Arab Emirates imposed authentication standards for government portals, while Saudi Arabia's Essential Cybersecurity Controls require multi-factor authentication in critical sectors. South Africa enforces reasonable security measures under the Protection of Personal Information Act, yet implementation varies across industries. South America centers on Brazil, where open banking regulations mandate strong customer authentication, while other economies lag due to fiscal headwinds.
- Thales S.A.
- NEC Corporation
- Broadcom Inc.
- Fujitsu Limited
- Dell Technologies Inc.
- Cisco Systems, Inc.
- Microsoft Corporation
- Google LLC
- Okta, Inc.
- Ping Identity Holding Corp.
- OneSpan Inc.
- Yubico AB
- IDEMIA Identity & Security France SAS
- HID Global Corporation
- Entrust Corporation
- ForgeRock, Inc.
- SecureAuth Corporation
- CyberArk Software Ltd.
- ValidSoft (Ireland) Limited
- SecurEnvoy Limited
- PistolStar, Inc.
- BioCatch Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Cloud Adoption Driving Zero-Trust Architectures
- 4.2.2 Rising Security Breach Costs and Cyber-Insurance Premiums
- 4.2.3 Accelerated Remote Workforce After 2025
- 4.2.4 Mandatory Multi-Factor Authentication Compliance in Regulated Sectors
- 4.2.5 Device-Embedded Hardware Roots of Trust in Consumer Electronics
- 4.2.6 Quantum-Resistant Cryptography Investments by Governments
- 4.3 Market Restraints
- 4.3.1 High Upgrade and Token Replacement Costs
- 4.3.2 Interoperability Gaps Across Legacy Infrastructure
- 4.3.3 User Friction Leading to Authentication Fatigue
- 4.3.4 Shortage of Skilled IAM Professionals
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Authentication Method
- 5.2.1 Smart Cards
- 5.2.2 Biometrics
- 5.2.2.1 Fingerprint Recognition
- 5.2.2.2 Iris and Retina Recognition
- 5.2.2.3 Facial Recognition
- 5.2.2.4 Voice Recognition
- 5.2.3 Mobile Smart Credentials
- 5.2.4 Tokens
- 5.2.5 User-based Public Key Infrastructure
- 5.2.6 Behavioral Analytics
- 5.3 By Authentication Model
- 5.3.1 Two-Factor Authentication (2FA)
- 5.3.2 Multi-Factor Authentication (MFA)
- 5.3.3 Continuous and Adaptive Authentication
- 5.3.4 Risk-Based Authentication
- 5.4 By Deployment Mode
- 5.4.1 On-Premise
- 5.4.2 Cloud
- 5.5 By End-user Industry
- 5.5.1 Banking, Financial Services and Insurance (BFSI)
- 5.5.2 Healthcare and Life Sciences
- 5.5.3 Government (Civil)
- 5.5.4 Defense
- 5.5.5 IT and Telecom
- 5.5.6 Retail and eCommerce
- 5.5.7 Energy and Utilities
- 5.5.8 Transportation and Logistics
- 5.5.9 Other End-user Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Russia
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 Middle East
- 5.6.4.1.1 Saudi Arabia
- 5.6.4.1.2 United Arab Emirates
- 5.6.4.1.3 Rest of Middle East
- 5.6.4.2 Africa
- 5.6.4.2.1 South Africa
- 5.6.4.2.2 Egypt
- 5.6.4.2.3 Rest of Africa
- 5.6.4.1 Middle East
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Thales S.A.
- 6.4.2 NEC Corporation
- 6.4.3 Broadcom Inc.
- 6.4.4 Fujitsu Limited
- 6.4.5 Dell Technologies Inc.
- 6.4.6 Cisco Systems, Inc.
- 6.4.7 Microsoft Corporation
- 6.4.8 Google LLC
- 6.4.9 Okta, Inc.
- 6.4.10 Ping Identity Holding Corp.
- 6.4.11 OneSpan Inc.
- 6.4.12 Yubico AB
- 6.4.13 IDEMIA Identity & Security France SAS
- 6.4.14 HID Global Corporation
- 6.4.15 Entrust Corporation
- 6.4.16 ForgeRock, Inc.
- 6.4.17 SecureAuth Corporation
- 6.4.18 CyberArk Software Ltd.
- 6.4.19 ValidSoft (Ireland) Limited
- 6.4.20 SecurEnvoy Limited
- 6.4.21 PistolStar, Inc.
- 6.4.22 BioCatch Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment