|
시장보고서
상품코드
2122295
아날로그 및 혼합 신호 IP 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Analog And Mixed Signal IP - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
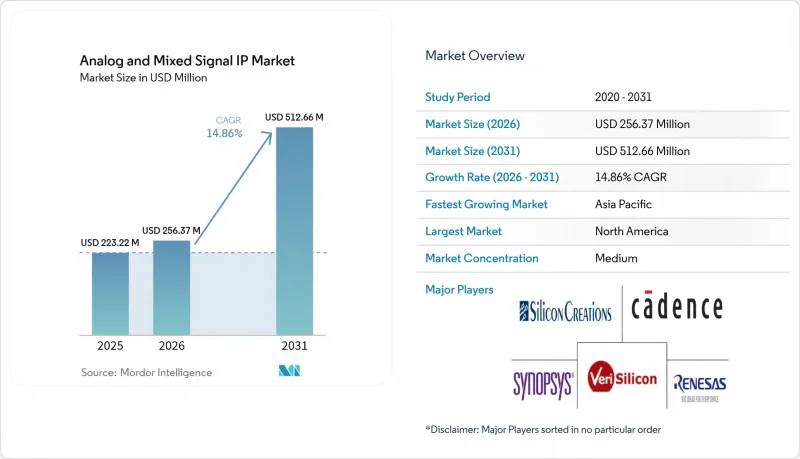
에 의하면, 아날로그 및 혼합 신호 IP시장 규모는 2025년에 2억 2,322만 달러로 평가되었고, 2026년 2억 5,637만 달러에서 2031년까지 5억 1,266만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 14.86%를 나타낼 전망입니다.
본 보고서는 설계별(펌웨어/소프트 IP, 하드 IP), 제품별(A2D 및 D2A 컨버터, 전력 관리 모듈, RF 등), 최종 사용자 산업별(소비자 가전, 통신, 기타), 공정 노드별(7nm 이하, 8nm-16nm, 20nm-45nm, 65nm 이상), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 아날로그 및 혼합 신호 IP 시장 동향과 인사이트
저전력 커넥티드 기기에 대한 수요 증가
IoT 엔드포인트 및 웨어러블 센서에는 배터리 수명을 10년으로 연장하기 위해 1밀리와트 미만으로 작동하는 아날로그 프론트엔드가 필요하지만, 이 목표는 디스크리트 부품으로는 달성하기 어렵습니다. 현재, 질화갈륨(GaN) 및 실리콘카바이드(SiC) IP는 100나노암페어 미만의 정지 전류를 실현하여, 코인형 배터리가 필요 없는 산업용 모니터링 노드를 가능하게 하고 있습니다. 유럽의 ‘지속 가능한 제품을 위한 에코디자인 규정’에서는 에너지 효율 라벨 표시가 의무화되어 있어, 이로 인해 소비자용 및 산업용 제품 전반에 걸쳐 초저전력 아날로그 IP의 채택이 가속화되고 있습니다. 스마트폰 설계자들은 유휴 상태의 아날로그 경로를 차단하는 파워 게이팅 IP를 라이선싱하여 대기 시 전력 소비를 40-60% 절감하고 있습니다. 수요가 가장 높은 지역은 아시아태평양이며, 비용에 민감한 웨어러블 기기 제조업체들은 순수한 처리량보다 배터리 수명을 더 중요하게 여기고 있습니다. 그 결과, 아날로그 및 혼합 신호 IP 시장에서 초저 누설 전류 라이브러리는 엣지 디바이스를 위한 기본 옵션으로 점점 더 자리 잡고 있습니다.
엣지 AI 추론 워크로드의 급속한 확산
네트워크 에지에서의 머신 러닝 추론에는 실시간 분류를 위해 70데시벨 이상의 신호 대 잡음비(SNR)를 유지하면서 1기가샘플/초 이상의 샘플링을 수행하는 아날로그-디지털 변환기(ADC)가 필요합니다. 자동차용 레이더 시스템은 AEC-Q100 규격을 준수하는 고정밀 델타-시그마 변환기에 의존하고 있으며, 이것이 자동차 등급 블록용 IP 계약의 새로운 수요를 견인하고 있습니다. 휴대폰 기지국에 추론 가속기를 배치하는 하이퍼스케일 클라우드 제공업체는 지연 시간을 줄이기 위해 아날로그 프론트엔드를 5나노미터 ASIC에 직접 통합하고 있으며, 이로 인해 독립적인 아날로그 칩공급망이 축소되고 있습니다. 스마트 카메라 및 산업용 비전 시스템에서는 순차 근사형 ADC에 비해 초당 1,000만 샘플의 속도로 16비트 분해능이 요구되며, 이 사양을 확실하게 충족할 수 있는 것은 FinFET 노드에 최적화된 하드 IP뿐입니다. 이러한 수요로 인해 설계 주기가 단축되면서, 북미의 엣지 AI 스타트업들 사이에서 아날로그 및 혼합 신호 IP 시장의 성장세가 더욱 가속화되고 있습니다.
AMS 공동 시뮬레이션에서의 검증 병목 현상
아날로그 블록에는 디지털 로직에서 사용되는 이산 이벤트 가속화의 이점을 누릴 수 없는 연속 시간 시뮬레이션 엔진이 필요하기 때문에 이로 인해 검증 주기가 3배에서 5배까지 길어지고 있습니다. 2024년에는 기생 커패시턴스와 기판 결합이 기존 SPICE 모델을 저해함에 따라, 7나노미터 노드에서 첫 실리콘 성공률이 62%까지 떨어졌습니다. Cadence사는 머신 러닝을 활용한 기생 요소 추출 기술을 도입했으나, 그 도입은 전문 팀에 자금을 투입할 수 있는 Tier 1 기업으로 제한되어 있습니다. 전원 관리 IP와 디지털 코어의 공동 시뮬레이션에는 1회 반복당 최대 50,000 CPU 시간이 소요되며, 테이프아웃이 최대 12개월 지연될 가능성이 있습니다. 소규모 팹리스 기업들은 첫 수율을 확보하기 위해 마진을 과도하게 설계하여 전력 효율을 희생하고 있기 때문에 단기적인 아날로그 및 혼합 신호 IP 시장의 성장이 둔화되고 있습니다.
부문 분석
하드 IP는 2024년에 소수 점유율에 그쳤지만, 칩렛 기반 아키텍처가 성숙해짐에 따라 2031년까지 연평균 성장률(CAGR) 16.78%를 나타낼 것으로 예측됩니다. 인텔의 ‘Meteor Lake’ 프로세서는 사전 특성 평가가 완료된 전압 조정기 및 클럭 분배용 하드 IP가 동등한 소프트 IP에 비해 전력 소비를 20% 절감할 수 있음을 입증했습니다. 2024년에 승인된 ‘Universal Chiplet Interconnect Express(UCI-Express)’는 다이 간 아날로그 신호 전송을 표준화하여, 벤더가 공정 노드에 관계없이 성능을 보장하는 플러그 앤 플레이 방식의 타일을 출하할 수 있게 합니다. 아날로그 및 혼합 신호 IP 시장에서는 이러한 하드웨어화된 블록에 대해 50만 달러에서 200만 달러의 선불 요금에 더해 1-3%의 로열티라는 프리미엄 요금이 점점 더 일반화되고 있으며, 이는 대량 생산을 하는 스마트폰 및 자동차 부품 공급업체에게 수용 가능한 가격입니다.
2025년 아날로그 및 혼합 신호 IP 시장 점유율의 54.19%를 차지한 펌 IP와 소프트 IP는 파운드리 간 이식성이 최우선으로 고려되는 비용 중심의 소비자 가전 및 IoT 기기에서 여전히 필수적인 존재입니다. 레지스터 전송 레벨(RTL) 코드로 제공되는 소프트 IP는 아날로그 토폴로지의 맞춤 설정을 가능하게 하지만, 대규모 재검증을 불가피하게 하여 시장 출시까지의 기간을 최대 9개월까지 연장하게 됩니다. 현재 파운드리 각사는 3나노미터 게이트 올 어라운드(GaA) 공정을 위한 하드 IP 사전 인증을 진행하고 있으며, 고객이 첨단 노드 프로젝트에서 리스크를 완화할 수 있도록 지원하고 있습니다. 치플렛(chiplet) 생태계가 확대됨에 따라 하드 IP의 아날로그 및 혼합 신호 IP 시장 규모는 비약적으로 확대될 것으로 예상되지만, 소프트 IP의 경우 그 유연성이 성능 측면의 단점을 상쇄하기 때문에 레거시 노드에서는 계속해서 사용될 것입니다.
2025년에는 파워 매니지먼트 모듈이 매출의 36.25%를 차지했으며, 웨어러블에서 전기자동차에 이르기까지 모든 반도체 카테고리에 널리 보급되어 있음을 알 수 있습니다. 90% 이상의 효율을 유지하면서 0.5볼트에서 48볼트까지 작동이 가능한 전압 조정기 IP는 존 컨트롤러 및 고대역폭 메모리 스택에 필수적입니다. 한편, RF IP는 mm파 5G의 전개와 저궤도 위성 단말기를 배경으로 연평균 성장률(CAGR) 16.26%를 나타낼 것으로 예측됩니다. 24 기가헤르츠 이상의 용도를 지원하는 RF 블록용 아날로그 및 혼합 신호 IP 시장 규모는 휴대폰 제조업체들이 노이즈 피겨 3데시벨 미만의 저잡음 증폭기나 25데시벨·밀리와트의 출력을 제공하는 파워 앰프를 필요로 하고 있기 때문에 확대되고 있습니다.
112기가비트/초 속도에 대응하는 고속 SerDes 및 클럭·데이터 복구 IP는 현재 리타이머를 사용하지 않고도 2미터의 구리 배선에 도달하여, 데이터센터 스위치에서 포트당 50-100달러의 비용 절감을 실현하고 있습니다. 컨버터 IP는 산업용 자동화 및 의료용 영상 진단 분야에서 여전히 필수적인 반면, 온도 센서와 발진기는 항공우주 분야의 틈새 수요를 충족시키고 있습니다. 아날로그 및 혼합 신호 IP 시장에서는 성숙한 전원 관리 제품과 높은 성장이 예상되는 RF 분야의 성장 기회가 전략적으로 균형을 이루고 있어, 각 벤더가 전원, RF, 데이터 변환 제품 라인 전반에 걸쳐 다양한 포트폴리오를 유지할 수 있게 되었습니다.
지역별 분석
아시아태평양은 2025년에 아날로그 및 혼합 신호 IP 시장 점유율의 40.65%를 차지하며 1위를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 15.65%로 성장할 것으로 전망됩니다. 중국의 ‘국가 집적회로 기금’은 미국의 수출 규제 하에서 자급자족을 실현하기 위해 2024년에 국내 아날로그 IP 프로그램에 470억 달러를 투입했습니다. 일본은 대만 반도체 제조 회사(TSMC)와 체결한 파운드리 제휴를 통해 2나노미터 프로토타입 생산 능력을 확보하여, 국내 자동차 및 산업 분야 고객을 지원하고 있습니다. 한국은 AI 서버용 고대역폭 메모리 및 칩렛 상호 연결 IP 라이선싱을 진행하고 있으며, 한편 인도의 2만 5,000명에 달하는 아날로그 엔지니어링 인력이 북미 및 유럽으로부터의 IP 개발 수탁 계약을 담당하여 전 세계 고객의 설계 비용을 절감하고 있습니다.
북미는 하이퍼스케일 데이터센터 사업자와 자동차 OEM 제조업체에 힘입어 2025년에는 28.12%의 점유율을 차지했습니다. ‘CHIPS and Science Act’에서는 첨단 패키징 및 치플릿에 110억 달러가 배정되어, 다이 간 아날로그 IP에 대한 현지 수요를 촉진하고 있습니다. 인텔의 200억 달러 규모 애리조나주 확장 계획에는 아날로그 인증 실험실이 포함되어 있으며, 제3자 IP 파트너를 초청하여 18A 노드에서 검증을 진행하고 있습니다. 캐나다공급업체인 마그나(Magna)는 인증된 아날로그 IP를 존 컨트롤러에 통합하고 있는 반면, 멕시코의 과달라하라 클러스터는 자동차 및 산업 분야의 니어쇼어 설계 허브로 부상하고 있습니다.
유럽은 약 22.28%의 점유율을 차지하고 있으며, 독일, 프랑스, 이탈리아가 선두를 달리고 있습니다. 유럽의 ‘유럽 칩 법(European Chips Act)’은 2030년까지 지역 내 반도체 점유율을 두 배로 늘리기 위해 430억 유로(470억 달러)를 투자하며, 전기차 및 재생 에너지 시스템을 위한 아날로그 및 전원 관리 IP를 우선 과제로 삼고 있습니다. 인피니온은 자동차 등급 IP를 강화하기 위해 케이던스 및 ARM과 제휴했으며, ST마이크로일렉트로닉스는 충전기 효율 95%를 목표로 한 질화갈륨(GaN) 파워 IP를 공동 개발하고 있습니다. 영국의 알파웨이브 IP는 SerDes 및 칩렛 포트폴리오를 확대하기 위해 4억 5,000만 파운드(5억 7,500만 달러)를 조달하여 고속 연결 분야에서 유럽의 입지를 강화하고 있습니다. 남미, 중동 및 아프리카의 합산 점유율은 9% 미만이지만, 브라질의 전기차 프로그램과 사우디아라비아의 스마트 시티 프로젝트가 틈새 시장 기회를 창출하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the analog and mixed signal IP market size was valued at USD 223.22 million in 2025 and estimated to grow from USD 256.37 million in 2026 to reach USD 512.66 million by 2031, at a CAGR of 14.86% during the forecast period (2026-2031).

This report is Segmented by Design (Firm/Soft IP, and Hard IP), Product (A2D and D2A Converters, Power Management Modules, RF, and More), End-User Industry (Consumer Electronics, Telecommunication, and More), Process Node (7 Nm and Below, 8 Nm To 16 Nm, 20 Nm To 45 Nm, and 65 Nm and Above), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Analog And Mixed Signal IP Market Trends and Insights
Growing Demand for Low-Power Connected Devices
Internet-of-Things endpoints and wearable sensors need analog front ends operating below 1 milliwatt so their batteries last a decade, a target that discrete components struggle to meet. Gallium-nitride and silicon-carbide IP now deliver sub-100-nanoampere quiescent currents, enabling coin-cell-free industrial monitoring nodes. The European Ecodesign for Sustainable Products Regulation mandates energy-efficiency labels, accelerating uptake of ultra-low-power analog IP across consumer and industrial products. Smartphone designers are licensing power-gating IP that shuts down idle analog paths, trimming standby drain by 40-60%. Demand is most intense in Asia-Pacific, where cost-sensitive wearables makers prize battery life over raw throughput. Consequently, the analog and mixed signal IP market increasingly positions ultra-low-leakage libraries as a default option for edge devices.
Rapid Proliferation of Edge AI Inference Workloads
Machine-learning inference at the network edge requires analog-to-digital converters sampling above 1 giga sample per second while sustaining more than 70 decibels of signal-to-noise ratio for real-time classification. Automotive radar systems rely on precision delta-sigma converters qualified to AEC-Q100 standards, driving fresh IP contracts for automotive-grade blocks. Hyperscale cloud providers deploying inference accelerators at cell towers embed analog front ends directly onto 5-nanometer ASICs to cut latency, compressing the standalone analog-chip supply chain. Smart cameras and industrial vision systems are pushing successive-approximation ADCs toward 16-bit resolution at 10 mega samples per second, a specification reliably met only by hard IP optimized for FinFET nodes. These needs shorten design cycles, reinforcing the analog and mixed signal IP market momentum among North American edge-AI startups.
Verification Bottlenecks for AMS Co-Simulation
Analog blocks need continuous-time simulation engines that cannot benefit from the discrete-event acceleration used for digital logic, stretching verification cycles by three-to-five times. First-time silicon success at 7-nanometer nodes fell to 62% in 2024 because parasitic capacitance and substrate coupling undermine traditional SPICE models. Cadence introduced machine-learning-assisted parasitic extraction, yet uptake remains limited to tier-one firms able to fund specialized teams. Co-simulating power-management IP with digital cores can consume up to 50,000 CPU-hours per iteration, pushing tape-out by as much as 12 months. Smaller fabless houses over-design margins, compromising power efficiency to secure first-pass yields, which tempers near-term analog and mixed signal IP market growth.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of 5G-Enabled RF Front ends in Smartphones
- Automotive OEM Pivot to Zonal Architectures
- Scarcity of Analog Design Talent in Sub-10 nm Nodes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hard IP captured a minority share in 2024, yet it is projected to grow at 16.78% CAGR through 2031 as chiplet-based architectures mature. Intel's Meteor Lake processor demonstrated that pre-characterized voltage-regulator and clock-distribution hard IP can trim power by 20% relative to soft equivalents. Universal Chiplet Interconnect Express, ratified in 2024, formalizes die-to-die analog signalling, allowing vendors to ship plug-and-play tiles that guarantee performance across process nodes. The analog and mixed signal IP market increasingly sees premium fees USD 500,000 to USD 2 million up front plus 1-3% royalties for these hardened blocks, a price acceptable to high-volume smartphone and automotive suppliers.
Firm and soft IP, which held 54.19% of analog and mixed signal IP market share in 2025, remains vital in cost-sensitive consumer and Internet-of-Things devices where portability across foundries is paramount. Soft IP delivered as register-transfer-level code allows tailoring of analog topologies but forces extensive re-verification, stretching time-to-market by up to nine months. Foundries now pre-qualify hard IP for 3-nanometer gate-all-around processes, helping customers de-risk advanced-node projects. As chiplet ecosystems widen, the analog and mixed signal IP market size for hard IP is set to leap, though soft IP will persist in legacy nodes because its flexibility outweighs performance trade-offs.
Power-management modules captured 36.25% revenue in 2025, underscoring their ubiquity across every semiconductor category from wearables to electric vehicles. Voltage-regulator IP capable of 0.5-volt to 48-volt operation while sustaining more than 90% efficiency is indispensable in zonal controllers and high-bandwidth-memory stacks. Yet RF IP is forecast to grow at a 16.26% CAGR on the back of millimeter-wave 5G rollouts and low-Earth-orbit satellite terminals. The analog and mixed signal IP market size for RF blocks serving 24-plus-gigahertz applications is swelling as handset makers need low-noise amplifiers with noise figures below 3 decibels and power amplifiers delivering 25 decibel-milliwatts.
High-speed SerDes and clock-data-recovery IP at 112-gigabit-per-second rates now reach 2-meter copper traces without retimers, saving USD 50-100 per port in data-center switches. Converter IP remains essential in industrial automation and medical imaging, while temperature sensors and oscillators address niche aerospace needs. The analog and mixed signal IP market strategically balances mature power-management products with high-growth RF opportunities, ensuring that vendors maintain diversified portfolios across power, RF, and data-conversion lines.
Complete Report Scope:
- By Design
- Firm/Soft IP
- Hard IP
- By Product
- A2D and D2A Converters
- Power Management Modules
- RF
- Other Products
- By End-User Industry
- Consumer Electronics
- Telecommunication
- Automotive
- Industrial
- Other End-User Industries
- By Process Node
- 7 nm and Below
- 8 nm - 16 nm
- 20 nm - 45 nm
- 65 nm and Above
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific led with 40.65% analog and mixed signal IP market share in 2025 and is forecast to grow at 15.65% CAGR through 2031. China's National Integrated Circuit Fund directed USD 47 billion into domestic analog IP programs in 2024 to reach self-sufficiency amid U.S. export controls. Japan's foundry alliances with Taiwan Semiconductor Manufacturing Company secure capacity for 2-nanometer prototypes, supporting local automotive and industrial clients. South Korea licenses high-bandwidth-memory and chiplet interconnect IP for AI servers, while India's 25,000-strong analog-engineering workforce handles outsourced IP development contracts from North America and Europe, lowering design costs for global customers.
North America held 28.12% share in 2025, driven by hyperscale data-center operators and vehicle OEMs. The CHIPS and Science Act earmarked USD 11 billion for advanced packaging and chiplets, stimulating local demand for die-to-die analog IP. Intel's USD 20 billion Arizona expansion includes analog qualification labs, inviting third-party IP partners to validate on the 18A node. Canadian supplier Magna integrates certified analog IP into zonal controllers, while Mexico's Guadalajara cluster emerges as a near-shore design hub for automotive and industrial segments.
Europe commanded about 22.28% share, with Germany, France, and Italy at the forefront. The European Chips Act commits EUR 43 billion (USD 47 billion) toward doubling regional semiconductor share by 2030 and prioritizes analog and power-management IP for electric-vehicle and renewable-energy systems. Infineon partnered with Cadence and ARM to enrich its automotive-grade IP, and STMicroelectronics co-develops gallium-nitride power IP targeting 95% charger efficiency. The United Kingdom's Alphawave IP raised GBP 450 million (USD 575 million) to scale its SerDes and chiplet portfolios, strengthening Europe's role in high-speed connectivity. South America, the Middle East and Africa collectively contribute under 9%, though Brazil's electric-vehicle programs and Saudi Arabia's smart-city projects produce niche opportunities.
- Cadence Design Systems Inc.
- Synopsys Inc.
- ARM Ltd.
- VeriSilicon Holdings Co. Ltd.
- Silicon Creations LLC
- Renesas Electronics Corporation
- Advanced Micro Devices Inc. (Xilinx)
- Intel Corporation
- Analog Devices Inc.
- Texas Instruments Incorporated
- Rambus Inc.
- Faraday Technology Corporation
- GlobalFoundries Inc.
- Ceva Inc.
- MACOM Technology Solutions Holdings Inc.
- Infineon Technologies AG
- Microchip Technology Inc.
- Marvell Technology Inc.
- SemiFive Inc.
- Alphawave IP Group plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Demand for Low-Power Connected Devices
- 4.2.2 Rapid Proliferation of Edge AI Inference Workloads
- 4.2.3 Expansion of 5G-Enabled RF Front-Ends in Smartphones
- 4.2.4 Automotive OEM Pivot to Zonal Architectures
- 4.2.5 Adoption of Chiplet-Based Heterogeneous Integration
- 4.2.6 Heightened Focus on Security-Centric Analog IP (Physically Unclonable Functions)
- 4.3 Market Restraints
- 4.3.1 Verification Bottlenecks for AMS Co-Simulation
- 4.3.2 Scarcity of Analog Design Talent in Sub-10 nm Nodes
- 4.3.3 Licensing Complexity in Multi-Die Systems
- 4.3.4 Geopolitical Export Controls on EDA/IP to China
- 4.4 Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Design
- 5.1.1 Firm/Soft IP
- 5.1.2 Hard IP
- 5.2 By Product
- 5.2.1 A2D and D2A Converters
- 5.2.2 Power Management Modules
- 5.2.3 RF
- 5.2.4 Other Products
- 5.3 By End-User Industry
- 5.3.1 Consumer Electronics
- 5.3.2 Telecommunication
- 5.3.3 Automotive
- 5.3.4 Industrial
- 5.3.5 Other End-User Industries
- 5.4 By Process Node
- 5.4.1 7 nm and Below
- 5.4.2 8 nm - 16 nm
- 5.4.3 20 nm - 45 nm
- 5.4.4 65 nm and Above
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Rest of Asia Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Cadence Design Systems Inc.
- 6.4.2 Synopsys Inc.
- 6.4.3 ARM Ltd.
- 6.4.4 VeriSilicon Holdings Co. Ltd.
- 6.4.5 Silicon Creations LLC
- 6.4.6 Renesas Electronics Corporation
- 6.4.7 Advanced Micro Devices Inc. (Xilinx)
- 6.4.8 Intel Corporation
- 6.4.9 Analog Devices Inc.
- 6.4.10 Texas Instruments Incorporated
- 6.4.11 Rambus Inc.
- 6.4.12 Faraday Technology Corporation
- 6.4.13 GlobalFoundries Inc.
- 6.4.14 Ceva Inc.
- 6.4.15 MACOM Technology Solutions Holdings Inc.
- 6.4.16 Infineon Technologies AG
- 6.4.17 Microchip Technology Inc.
- 6.4.18 Marvell Technology Inc.
- 6.4.19 SemiFive Inc.
- 6.4.20 Alphawave IP Group plc
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment