

|
시장보고서
상품코드
2122301
네트워크 대역폭 관리 소프트웨어 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Network Bandwidth Management Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 네트워크 대역폭 관리 소프트웨어 시장 규모는 2025년 32억 1,000만 달러로 평가되었고, 2026년에는 34억 1,000만 달러로 추정되고, 2026-2031년 CAGR 6.29%로 성장을 지속할 전망이며, 2031년까지 46억 3,000만 달러에 이를 것으로 예측됩니다.
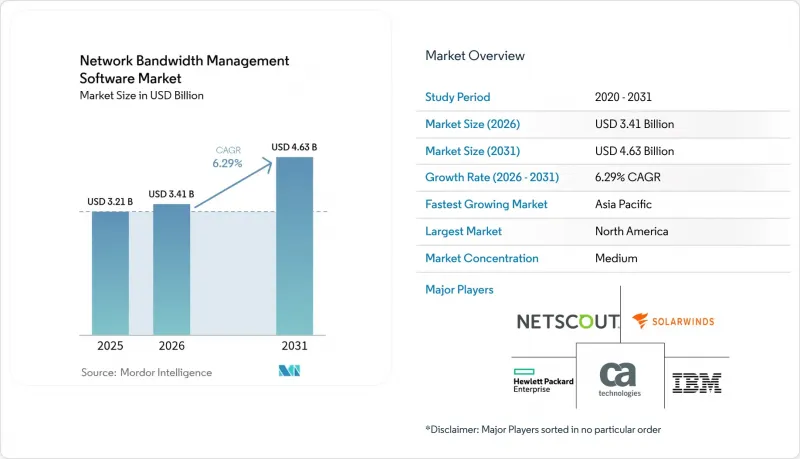
본 보고서는 도입 모델별(온프레미스, 클라우드), 기업 규모별(중소기업, 대기업), 솔루션 유형별(대역폭 모니터링·보고서 작성 등), 최종 사용자 업종별(통신 및 IT, BFSI 등), 네트워크 유형별(유선 네트워크 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 네트워크 대역폭 관리 소프트웨어 시장 동향 및 인사이트
IoT 엔드포인트 및 프라이빗 5G 엔터프라이즈 네트워크의 폭발적인 증가
기업 내 IoT 도입으로 인해 공장, 사무실, 물류 거점에 수천 개의 센서가 추가되면서, 기존의 베스트 에포트(best-effort)형 라우팅으로는 대응할 수 없는 예측 불가능한 트래픽이 발생하고 있습니다. 프라이빗 5G는 초저지연 용도이 엄격한 대역폭 보장을 필요로 하기 때문에 이 과제를 더욱 심각하게 만들고 있습니다. 전문적인 서비스를 제공하는 4만 명의 긴급 대응 요원을 지원하는 실제 운영 사례는 미션 크리티컬한 사용자가 세밀한 대역폭 제어에 얼마나 의존하고 있는지를 보여줍니다. 따라서 기업에서는 트래픽을 분류하고, 소비량을 예측하며, 이종 링크 간에 리소스를 실시간으로 재분배하는 AI 기반 도구를 선택하고 있습니다.
고속 인터넷 및 SD-WAN 도입에 대한 수요 증가
SD-WAN은 MPLS, 광대역, 5G에 걸친 용도 인식 라우팅을 도입하여, 대역폭 관리를 단순한 보고 업무에서 비즈니스 가치를 창출하는 수단으로 변화시킵니다. SD-WAN을 도입한 조직에서는 단일 정책 엔진 하에서 전송 링크를 통합함으로써 하드웨어 비용을 70% 절감하고 운영 효율을 74% 향상시켰습니다. 그 결과, 대역폭 관리 소프트웨어는 단순한 처리량이 아닌 사용자 경험과 비즈니스 우선순위에 맞추어 최적화되어야 하며, 수익을 창출하는 용도를 보호하기 위한 분석 기능을 통합해야 합니다.
프리미엄/오픈소스 트래픽 관리 도구가 진입 장벽을 낮춥니다.
Zabbix나 LibreQoS와 같은 견고한 무료 도구는 라이선스 비용 없이 기업에 기본적인 가시성을 제공하기 때문에 상용 플랫폼으로의 전환이 지연되고 있습니다. 이에 대응하여 각 벤더는 핵심 센서가 무료로 포함된 스타터 플랜을 제공하며, AI 기반 인사이트, 정책 자동화, 프리미엄 지원 등의 측면에서 차별화를 꾀하고 있습니다. 이로 인해 모니터링 기능은 상품화되는 반면, 오케스트레이션 기능에 대한 요구 수준은 높아지고 있습니다.
부문 분석
2025년에는 클라우드 옵션이 총 지출의 51.35%를 차지한 것으로 평가되었고, 조직이 어디서나 액세스할 수 있는 확장 가능한 제어 플레인을 선호하는 경향이 분명해졌습니다. 이 부문은 2031년까지 연평균 성장률(CAGR) 8.14%를 나타낼 것으로 예측되며, 이는 온프레미스 배포를 훨씬 능가하는 속도입니다. 기업 측은 하드웨어 업데이트가 불필요해지고 패치 적용 일정이 간소화됨에 따라 총 소유 비용(TCO)이 40% 절감된다고 지적하고 있습니다. 주권이나 초저지연 처리의 관점에서 로컬 제어가 필요한 상황에서는 온프레미스 시스템이 계속해서 채택되고 있습니다. 하이브리드 아키텍처에서는 기밀 데이터용 엣지 게이트웨이와 광범위한 가시성을 실현하는 클라우드 분석 허브를 결합하고 있습니다.
관리 오버헤드 절감은 마이그레이션의 경제성을 좌우하는 핵심 요소입니다. 관리자는 출장 없이도 수백 곳에 달하는 거점에 걸쳐 정책 변경을 배포할 수 있으며, 멀티테넌트 인스턴스를 통해 MSP는 사내에 전문 지식이 없는 중소기업에도 서비스를 제공할 수 있게 됩니다. 따라서 네트워크 대역폭 관리 소프트웨어 시장은 꾸준히 SaaS 모델로 전환되고 있지만, 벤더들은 여전히 에어 갭 환경을 위한 어플라이언스 이미지를 제공합니다. 이러한 이중 제공 전략은 기존 수익을 보호하는 동시에 구독 기반의 성장 경로를 마련하고 있습니다.
대기업은 복잡한 토폴로지와 규정 준수 요건으로 인해 고급 제품군에 대한 투자가 정당화되었기 때문에 2025년 매출의 63.05%를 차지했습니다. 반면, 클라우드 네이티브 가격 책정이 운영 예산과 조화를 이루면서 중소기업은 2031년까지 연평균 성장률(CAGR) 6.48%로 성장할 전망입니다. 매니지드 서비스 번들을 통해 중소기업은 모니터링, 보고, 정책 적용을 외부에 위탁할 수 있게 되어 인력을 증원하지 않고도 도입을 가속화할 수 있습니다.
중소기업의 이용 규모가 확대됨에 따라, 각 벤더는 자동 감지, 템플릿 기반 정책, 안내형 시정 조치를 통해 온보딩 효율화를 추진하고 있습니다. 한편, 대기업은 계속해서 ITSM 및 SIEM 스택과 통합 가능한 맞춤형 모듈을 요구하고 있습니다. 이러한 양극화된 로드맵이 네트워크 대역폭 관리 소프트웨어 시장의 기반을 형성하고 있으며, 공급업체에게는 명확한 고객 세분화를 유지하면서 여러 가지 성장 경로가 제공되고 있습니다.
지역별 분석
북미는 성숙한 IT 예산, 엄격한 규정 준수 체계, 그리고 AI 지원 데이터센터에 대한 지속적인 투자에 힘입어 2025년 매출의 34.05%를 차지했습니다. 하이퍼스케일러에 의한 수십억 달러 규모의 인프라 구축은 트래픽 가시화, 용량 계획 및 SLA 보장에 대한 지속적인 수요로 이어지고 있습니다. 지역별 의료 및 금융 규제 역시 지속적인 모니터링과 세분화된 아키텍처를 의무화하고 있어 시장의 성장세를 뒷받침하고 있습니다. 이러한 요인들이 결합되어 북미는 네트워크 대역폭 관리 소프트웨어 시장에서 가장 큰 점유율을 차지하는 입지를 공고히 하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 7.05%로 가장 빠른 성장이 예상됩니다. 각국 정부가 디지털 인프라를 우선시하고 5G 도입이 가속화되는 가운데, 기업들은 클라우드와 SD-WAN을 동시에 도입함으로써 기존의 회선 모델을 획기적으로 뛰어넘고 있습니다. 네트워크 성숙도에 큰 차이가 있기 때문에 신흥국을 대상으로 한 ‘성장에 따른 과금(pay-as-you-grow)’형 SKU부터 일본 및 한국 등의 선진 시장을 대상으로 한 풀스택 제품군에 이르기까지 유연한 라이선싱 체계가 요구되고 있습니다. 언어 지원 및 규정 준수 템플릿을 현지 언어로 제공하는 벤더는 매우 큰 시장 점유율을 확보할 것으로 전망됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the network bandwidth management software market size is expected to grow from USD 3.21 billion in 2025 to USD 3.41 billion in 2026 and is forecast to reach USD 4.63 billion by 2031 at 6.29% CAGR over 2026-2031.
This report is Segmented by Deployment Model (On-Premise, Cloud), Enterprise Size (Small and Medium Enterprises, Large Enterprises), Solution Type (Bandwidth Monitoring and Reporting, and More), End-User Vertical (Telecommunication and IT, BFSI, and More), Network Type (Wired Networks, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Network Bandwidth Management Software Market Trends and Insights
Explosion of IoT Endpoints and Private 5G Enterprise Networks
Enterprise IoT rollouts add thousands of sensors across factories, offices, and logistics hubs, generating unpredictable traffic that legacy best-effort routing cannot handle. Private 5G further intensifies the challenge because ultra-low-latency applications require strict bandwidth guarantees. A live deployment supporting 40,000 first responders for specialized services illustrates how mission-critical users depend on granular bandwidth control. Enterprises, therefore, select AI-driven tools that classify traffic, forecast consumption, and reallocate resources across heterogeneous links in real time.
Growing Need for High-Speed Internet and SD-WAN Adoption
SD-WAN introduces application-aware routing that spans MPLS, broadband, and 5G, turning bandwidth management from a reporting task into a business value lever. Organizations adopting SD-WAN have recorded 70% lower hardware spend and 74% higher operational efficiency by unifying transport links under a single policy engine. As a result, bandwidth software must optimize for user experience and business priority rather than raw throughput, embedding analytics to safeguard revenue-generating applications.
Freemium/Open-Source Traffic Tools Lower Entry Barriers
Robust free tools such as Zabbix and LibreQoS give firms basic visibility without license fees, delaying conversions to commercial platforms. Vendors counter by offering starter tiers that include core sensors at no cost, pushing differentiation toward AI insights, policy automation, and premium support. This commoditizes monitoring while raising the bar for orchestration features.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of Data-Rich Apps (4K/8K Video, AR/VR, AI Analytics)
- Edge AI Workloads Requiring Deterministic Bandwidth
- Integration Complexity with Legacy On-Premise Infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud options commanded 51.35% of total spending in 2025, illustrating how organizations favor scalable control planes accessed from anywhere. The segment is forecast to grow at 8.14% CAGR to 2031, far faster than on-premise deployments. Enterprises cite 40% lower total ownership through the elimination of hardware refreshes and simplified patching schedules. On-premise systems remain in place where sovereignty or ultra-low-latency processing dictates local control. Hybrid architectures combine edge gateways for sensitive data with cloud analytics hubs for broad visibility.
Lower management overhead sits at the heart of migration economics. Administrators can roll out policy changes across hundreds of sites without traveling, while multi-tenant instances enable MSPs to serve SMEs lacking in-house expertise. The Network Bandwidth Management Software market, therefore, tilts steadily toward SaaS models, although vendors still offer appliance images for air-gapped environments. This dual delivery strategy protects existing revenue while paving a path to subscription growth.
Large enterprises controlled 63.05% of 2025 revenue because complex topologies and compliance demands justified investment in advanced suites. Yet SMEs are on track for a 6.48% CAGR through 2031 as cloud-native pricing aligns with operating budgets. Managed services bundles allow smaller firms to outsource monitoring, reporting, and policy enforcement, accelerating adoption without adding headcount.
Volume growth among SMEs pushes vendors to streamline onboarding through auto-discovery, template-based policies, and guided remediation. At the same time, large enterprises continue to seek customizable modules that integrate with ITSM and SIEM stacks. This bifurcated roadmap anchors the Network Bandwidth Management Software market, giving suppliers multiple paths to expansion while maintaining clear account segmentation.
Complete Report Scope:
- By Deployment Model
- On-Premise
- Cloud
- By Enterprise Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By Solution Type
- Bandwidth Monitoring and Reporting
- Traffic Shaping / QoS Control
- WAN / Internet Link Optimization
- SD-WAN Bandwidth Management
- Others (Policy-based, DPI, etc.)
- By End-User Vertical
- Telecommunication and IT
- BFSI
- Healthcare
- Retail and E-commerce
- Education
- Government and Defense
- Manufacturing
- Others
- By Network Type
- Wired Networks
- Wireless and Wi-Fi Networks
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Netherlands
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Israel
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 34.05% of 2025 revenue, buoyed by mature IT budgets, tight compliance regimes, and ongoing investment in AI-enabled data centers. Hyperscalers' multibillion-dollar builds translate into sustained demand for traffic visibility, capacity planning, and SLA assurance. Regional healthcare and finance regulations add momentum because they mandate continuous monitoring and segmented architectures. Collectively, these forces cement North America as the largest slice of the Network Bandwidth Management Software market.
Asia-Pacific is poised for the fastest expansion with a 7.05% CAGR to 2031. Governments prioritize digital infrastructure, 5G rollouts advance quickly, and enterprises leapfrog legacy circuit models by adopting cloud and SD-WAN concurrently. Wide variance in network maturity encourages flexible licensing ranging from pay-as-you-grow SKUs for emerging economies to full-stack suites for advanced markets such as Japan and South Korea. Vendors that localize language support and compliance templates stand to capture outsized share.
- Cisco Systems Inc.
- IBM Corporation
- NetScout Systems Inc.
- SolarWinds Corporation
- Broadcom Inc. (CA Technologies)
- Hewlett Packard Enterprise Company
- Juniper Networks Inc.
- InfoVista SA
- BMC Software Inc.
- Alcatel-Lucent Enterprise Holding
- GFI Software SA
- Axence Software Inc.
- Zoho Corporation Pvt. Ltd.
- Riverbed Technology LLC
- Paessler AG
- ManageEngine (Zoho Corp.)
- Auvik Networks Inc.
- Fortinet Inc.
- Huawei Technologies Co., Ltd.
- Extreme Networks Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Explosion of IoT endpoints and private 5G enterprise networks
- 4.2.2 Growing need for high-speed internet and SD-WAN adoption
- 4.2.3 Proliferation of data-rich apps (4K/8K video, AR/VR, AI analytics)
- 4.2.4 Edge AI workloads requiring deterministic bandwidth (under-the-radar)
- 4.2.5 5G network-slicing unlocking per-slice bandwidth orchestration (under-the-radar)
- 4.2.6 Shift toward AIOps demanding embedded bandwidth analytics (under-the-radar)
- 4.3 Market Restraints
- 4.3.1 Freemium/open-source traffic tools lower entry barriers
- 4.3.2 Integration complexity with legacy on-prem infrastructure
- 4.3.3 Privacy regulations curb deep-packet inspection capability (under-the-radar)
- 4.3.4 Zero-trust focus diverts budgets from bandwidth tools (under-the-radar)
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Model
- 5.1.1 On-Premise
- 5.1.2 Cloud
- 5.2 By Enterprise Size
- 5.2.1 Small and Medium Enterprises (SMEs)
- 5.2.2 Large Enterprises
- 5.3 By Solution Type
- 5.3.1 Bandwidth Monitoring and Reporting
- 5.3.2 Traffic Shaping / QoS Control
- 5.3.3 WAN / Internet Link Optimization
- 5.3.4 SD-WAN Bandwidth Management
- 5.3.5 Others (Policy-based, DPI, etc.)
- 5.4 By End-User Vertical
- 5.4.1 Telecommunication and IT
- 5.4.2 BFSI
- 5.4.3 Healthcare
- 5.4.4 Retail and E-commerce
- 5.4.5 Education
- 5.4.6 Government and Defense
- 5.4.7 Manufacturing
- 5.4.8 Others
- 5.5 By Network Type
- 5.5.1 Wired Networks
- 5.5.2 Wireless and Wi-Fi Networks
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Netherlands
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia and New Zealand
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Israel
- 5.6.5.1.5 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Kenya
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Cisco Systems Inc.
- 6.4.2 IBM Corporation
- 6.4.3 NetScout Systems Inc.
- 6.4.4 SolarWinds Corporation
- 6.4.5 Broadcom Inc. (CA Technologies)
- 6.4.6 Hewlett Packard Enterprise Company
- 6.4.7 Juniper Networks Inc.
- 6.4.8 InfoVista SA
- 6.4.9 BMC Software Inc.
- 6.4.10 Alcatel-Lucent Enterprise Holding
- 6.4.11 GFI Software SA
- 6.4.12 Axence Software Inc.
- 6.4.13 Zoho Corporation Pvt. Ltd.
- 6.4.14 Riverbed Technology LLC
- 6.4.15 Paessler AG
- 6.4.16 ManageEngine (Zoho Corp.)
- 6.4.17 Auvik Networks Inc.
- 6.4.18 Fortinet Inc.
- 6.4.19 Huawei Technologies Co., Ltd.
- 6.4.20 Extreme Networks Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


