|
시장보고서
상품코드
2122367
디젤 발전 엔진 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Diesel Power Engine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
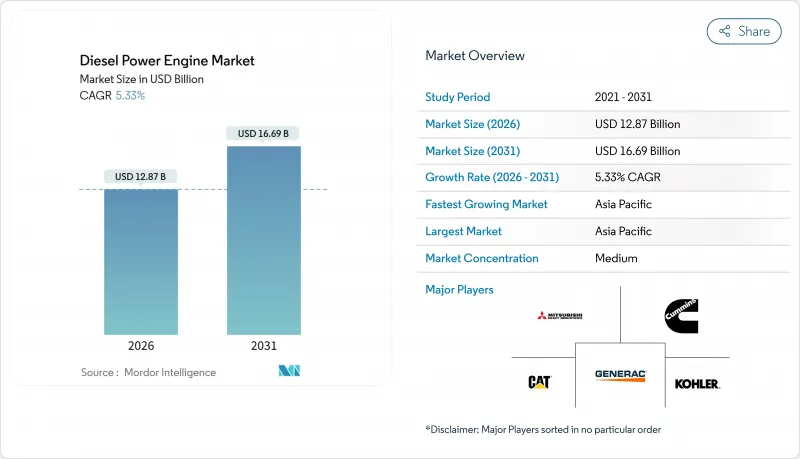
에 의하면, 디젤 발전 엔진 시장 규모는 2026년에 128억 7,000만 달러로 추정되며, 예측 기간(2026-2031년)에 CAGR 5.33%로 성장을 지속하여 2031년까지 166억 9,000만 달러에 이를 전망입니다.
본 보고서는 출력 범위별(75kVA 이하, 75-375kVA, 375-750kVA, 750-2,000kVA, 2,000kVA 이상),용도별(예비 전원, 주 전원·연속 운전, 피크 부하 완화), 최종 사용자별(산업용, 상업용, 주거용), 지역별(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 규모와 전망은 금액(달러)으로 표시되어 있습니다.
세계 디젤 발전 엔진 시장 동향 및 인사이트
신흥 시장의 송전망 강화 투자
사하라 이남 아프리카와 남아시아의 전력 사업자들은 장거리 송전선로와 변전소가 전기화 목표를 따라잡을 때까지의 과도기적 해결책으로 디젤 및 태양광 발전 기반의 미니 그리드를 도입하고 있습니다. 2025년, 세계은행은 50-150kW 엔진과 태양광 발전 어레이를 결합한 농촌 프로젝트에 23억 달러를 배정하여, 아프리카 18개국에서 전력 공급 비용을 1kWh당 0.18-0.25 달러로 낮췄습니다. 인도의 ‘사우바그야(Saubhagya)’ 프로그램에서는 각 가구에 대한 연결은 완료되었으나, 농촌 지역의 40%에서 일일 전력 공급 신뢰성이 12시간 이하에 그치고 있어, 이에 따라 각 주 전력 사업자들은 작년에 1만 5,000대의 예비 발전기를 발주했습니다. 이러한 발전기는 하루 6-10시간 가동되는 경우가 많아, 그 결과 마모가 가속화되고 교체 주기도 짧아지고 있습니다. 아프리카개발은행도 유사한 경제성을 확인했으며, 케냐, 탄자니아, 나이지리아에서는 직접적인 보조금 없이도 미니 그리드가 규제 요금을 밑돌 수 있다고 지적하고 있습니다.
아시아 전역의 데이터센터 건설 급증
하이퍼스케일 사업자들은 2025년 아시아태평양에서 1.2GW의 신규 디젤 비연속 발전 용량을 도입했으며, 그 총 도입량의 68%를 인도와 중국이 차지했습니다. 마이크로소프트와 AWS는 72시간 가동에는 N+1 디젤 중복성이 필요한 하이데라바드 캠퍼스에 65억 달러를 투자했습니다. 한편, 중국 공업정보화부는 모든 신규 Tier-3 사이트에 대해 부지 내에 3일 분량의 연료를 비축할 것을 의무화하고 있습니다. NREL의 최신 밀도 모델에 따르면, 수 메가와트 규모에서 배터리 시스템이 디젤의 에너지 저장 효율에 필적하게 되는 것은 2029년 이후가 될 것으로 시사되고 있습니다.
축전지의 LCOE 급격한 하락
리튬 이온 배터리 팩 가격은 2024년에 1kWh당 139달러까지 하락하여, 2023년 대비 14% 감소했습니다. 이에 따라 기존에는 디젤에 의존하던 상업용 건물에서도 4시간 동안의 전력 저장이 현실적인 선택지가 되었습니다. 캘리포니아주의 ‘자가 발전 장려 프로그램’은 2025년에 3억 2,000만 달러를 배정하여, 병원이나 데이터센터가 단시간 정전 대책으로 배터리 시스템을 도입할 수 있게 했습니다. 라자드(Lazard)사의 2025년 분석에 따르면, 1MW·4시간 용량의 배터리 시스템은 15년 동안 1kWh당 0.18달러의 비용으로 백업 전력을 제공할 수 있는 반면, 연간 50시간 가동되는 디젤 발전 세트의 경우 0.22달러가 소요됩니다. 그러나 5MW 부하에 대해 72시간의 자율 공급을 실현하려면 여전히 약 5,000만 달러의 비용이 드는 360MWh 규모의 배터리 시스템이 필요합니다. 이에 비해 디젤 발전 설비와 연료 비용은 300만 달러입니다.
부문 분석
375-750kVA급 디젤 발전 엔진 시장 규모는 2026년부터 2031년까지 연평균 7.5%의 성장률을 기록하고 있으며, 병원, 통신 허브, 공장 등이 더 높은 신뢰성 사양으로 업그레이드를 추진함에 따라 다른 모든 대역보다 높은 성장률을 보이고 있습니다. 75kVA 이하 유닛은 주택 및 소규모 상업시설의 부하를 감당함으로써 2025년 디젤 발전 엔진 시장 점유율 43.3%를 유지했으나, 부유층 소비자들이 태양광 배터리 솔루션으로 전환함에 따라 성장률은 4.8%로 둔화되고 있습니다. 중출력 75-375kVA 엔진은 소매 센터 및 식품 가공 시설에 도입되고 있으며, 이러한 시설에서는 10초 이내의 자동 전환이 현재 입찰의 표준 요건으로 자리 잡고 있습니다. 500-750kVA급에서는 캐터필러(Caterpillar)의 C18과 롤스로이스(Rolls-Royce)의 mtu 12V 2000이,가변 기하학 터보차저를 탑재해 연료 소비량을 6% 줄임으로써 의료 및 통신 부문에서 수주를 확보하고 있습니다. 2,000kVA를 초과하는 유닛은 계속해서 하이퍼스케일 캠퍼스용으로 공급되고 있지만, 사업자 측은 현재 단일 4MW 블록보다 중복성을 확보하기 위한 여러 개의 1,500-2,000kVA 모듈을 선호하는 경향에 있어, 이로 인해 조달 주기는 둔화되고 있으나 수요가 사라진 것은 아닙니다.
인도와 인도네시아의 통신 사업자들은 4G보다 40% 더 많은 전력을 소비하는 5G 무선 장비에 전력을 공급하기 위해 250kVA 발전기를 500-600kVA 모델로 교체하고 있습니다. PwC의 2025년 통신 에너지 감사에 따르면, 600kVA 장비는 효율 향상으로 가동 시간을 단축함으로써 가입자 1인당 탄소 집약도를 12% 감소시키는 것으로 나타났습니다. 마찬가지로, 병원 관리자들도 확장된 중환자실(ICU) 및 영상 진단 부서의 부하를 감당하기 위해 600-750kVA 발전기 어레이를 지정하고 있으며, 이러한 주문에는 보험 인증을 확보하기 위한 8시간 부하 테스트가 포함되어 있습니다. 75kVA 이하의 소형 발전기는 5년에 걸쳐 결제를 분할하는 소액 금융 프로그램의 지원에 힘입어, 아프리카와 남아시아의 농촌 지역에서 계속해서 보급될 것으로 보입니다.
지역별 분석
아시아태평양은 2025년 매출의 38.1%를 차지하며, 연평균 성장률(CAGR) 6.6%를 기록할 전망입니다. 이는 중국이 모든 신규 Tier-3 데이터센터에 대해 72시간의 예비 전력 확보를 의무화하고 있으며, 인도의 1조 3,000억 달러 규모의 인프라 정비 계획에 힘입은 결과입니다. 전력 공급이 불안정한 상황에서 아세안(ASEAN)에서 통신 타워 건설 붐이 일고 있는 데 발맞추어, 양마(Yanmar)는 2025년에 인도와 인도네시아의 농촌 지역에 2,500대의 발전기를 설치했습니다. 중동 및 아프리카는 6.4%의 견조한 연평균 성장률(CAGR)을 기록하고 있습니다. 사우디아라비아의 NEOM은 발츠일라 31 엔진을 탑재한 400MW의 예비 전원을 발주했으며, 케냐, 탄자니아, 나이지리아에서는 세계은행의 지원을 받아 미니 그리드 사업 확장이 진행되고 있습니다. 북미는 4.1%라는 성숙한 성장 궤도를 보이고 있으며, 배터리 인센티브 및 배출 규제 강화로 인해 성장이 제한되는 한편, 군사 계약 및 반도체 국내 복귀(리쇼어링)에 의해 지지를 받고 있습니다. 유럽의 3.8%라는 성장률은 특히 1MW를 초과하는 엔진에 대해 실시간 배출량 원격 측정(텔레메트리)을 의무화할 가능성이 있는 ‘산업 배출 지침’의 시행이 임박한 점 등 유사한 압박에 기인합니다.
디젤 발전 엔진 시장 전체에서는 아시아태평양의 지속적인 투자 파이프라인과 비교적 완화된 배출 규제가 선진국의 역풍을 상쇄하고 있습니다. 중동에서는 석유 자금을 통한 메가 프로젝트를 활용하여 가스 터빈 도입 확대의 영향을 상쇄하고 있는 반면, 사하라 이남 아프리카에서는 2035년까지의 전기화 격차를 해소하기 위해 디젤과 태양광 발전을 결합한 하이브리드형 미니 그리드에 의존하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.04According to Mordor Intelligence, the diesel power engine market size is estimated at USD 12.87 billion in 2026, and is expected to reach USD 16.69 billion by 2031, at a CAGR of 5.33% during the forecast period (2026-2031).
This report is Segmented by Capacity Range (Up To 75 KVA, 75 To 375 KVA, 375 To 750 KVA, 750 To 2, 000 KVA, and Above 2, 000 KVA), Application (Stand-By, Prime/Continuous, and Peak-Shaving), End User (Industrial, Commercial, and Residential), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Diesel Power Engine Market Trends and Insights
Grid-Hardening Investments in Emerging Markets
Utilities in Sub-Saharan Africa and South Asia are adopting diesel-solar mini-grids as an interim solution while long-distance transmission lines and substations catch up with electrification targets. In 2025, the World Bank allocated USD 2.3 billion for rural projects pairing 50-150 kW engines with photovoltaic arrays, lowering delivered power costs to USD 0.18-0.25 per kWh in 18 African nations. India's Saubhagya program completed household connections yet still recorded sub-12-hour daily reliability in 40% of rural districts, prompting state utilities to order 15,000 standby gensets last year. These sets often run 6-10 hours per day, driving faster wear and replacement cycles. The African Development Bank confirms similar economics, noting that mini-grids can undercut regulated tariffs without direct subsidies in Kenya, Tanzania, and Nigeria.
Boom in Data-Center Construction Across Asia
Hyperscale operators installed 1.2 GW of new diesel standby capacity in Asia-Pacific during 2025, with India and China representing 68% of the total build-out. Microsoft and AWS committed USD 6.5 billion to campuses in Hyderabad requiring N+1 diesel redundancy for 72-hour operation, while China's Ministry of Industry and Information Technology obliges all new Tier-3 sites to store three days of fuel on-site. NREL's latest density models suggest battery systems will not match diesel's energy storage efficiency at the multi-megawatt scale until after 2029.
Rapid Fall in Battery-Storage LCOE
Lithium-ion battery pack prices fell to USD 139 per kWh in 2024, a 14% drop from 2023, making four-hour storage viable for commercial buildings previously reliant on diesel. California's Self-Generation Incentive Program distributed USD 320 million in 2025, allowing hospitals and data centers to substitute battery systems for short-duration outages. Lazard's 2025 analysis shows a 1 MW/4 h battery delivers backup at USD 0.18 per kWh over 15 years, versus USD 0.22 for a diesel set running 50 hours per year. Yet providing 72-hour autonomy for a 5 MW load still requires a 360 MWh battery system costing about USD 50 million, compared to USD 3 million for diesel hardware and fuel.
Other drivers and restraints analyzed in the detailed report include:
- Industrial Automation Demand for Mission-Critical Backup
- Military Mobile-Power Modernization Programs
- Tighter NOx & Particulate Limits in OECD Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The diesel power engine market size for 375-750 kVA units is expanding at 7.5% per year during 2026-2031, outpacing every other band as hospitals, telecom hubs, and factories upgrade to higher reliability specifications. Sets up to 75 kVA retained 43.3% of the diesel power engine market share in 2025 by serving residential and small-commercial loads, yet growth moderates to 4.8% as affluent consumers migrate toward solar-battery solutions. Mid-range 75-375 kVA engines equip retail centers and food-processing sites where automatic transfer within 10 seconds is now a standard bid requirement. At 500-750 kVA, Caterpillar's C18 and Rolls-Royce's mtu 12V 2000 capture healthcare and telecom orders by coupling variable-geometry turbochargers with 6% lower fuel burn. Units above 2,000 kVA continue to serve hyperscale campuses, though operators now favor multiple 1,500-2,000 kVA modules for redundancy rather than single 4 MW blocks, tempering procurement cycles but not eliminating demand.
Telecom carriers in India and Indonesia are retiring 250 kVA gensets in favor of 500-600 kVA models to feed 5G radio units that consume 40% more power than 4G. PwC's 2025 telecom-energy audit found that 600 kVA machines cut carbon intensity 12% on a per-subscriber basis by reducing runtime through improved efficiency. Hospital administrators similarly specify 600-750 kVA arrays to cover expanded ICU and imaging loads, and these orders are bundled with eight-hour load-bank tests to secure insurance certification. Small sets under 75 kVA will still permeate rural Africa and South Asia, aided by micro-financing programs that spread payments over five years.
Complete Report Scope:
- By Capacity Range
- Up to 75 kVA
- 75 to 375 kVA
- 375 to 750 kVA
- 750 to 2,000 kVA
- Above 2,000 kVA
- By Application
- Stand-by
- Prime/Continuous
- Peak-shaving
- By End User
- Industrial
- Commercial
- Residential
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Spain
- NORDIC Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Australia and New Zealand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific booked 38.1% of 2025 turnover and is set to deliver a 6.6% CAGR, backed by China's mandate for 72-hour reserves at all new Tier-3 data centers and India's USD 1.3 trillion infrastructure roadmap. ASEAN's telecom tower boom under unreliable grids spurred Yanmar to place 2,500 gensets in rural India and Indonesia during 2025. Middle-East-Africa clocks a robust 6.4% CAGR: Saudi Arabia's NEOM ordered 400 MW of standby power using Wartsila 31 engines, and Kenya, Tanzania, and Nigeria scale mini-grid programs with World Bank backing. North America posts a mature 4.1% trajectory, limited by battery incentives and stricter emissions but buoyed by military contracts and semiconductor reshoring. Europe's 3.8% clip reflects parallel pressures, especially with the pending Industrial Emissions Directive that may require live emissions telemetry on engines over 1 MW.
Across the diesel power engine market, Asia-Pacific's sustained investment pipeline and looser emissions rules offset headwinds in developed economies. The Middle East leverages petro-financed megaprojects to offset rising gas-turbine adoption, while Sub-Saharan Africa relies on hybrid diesel-solar mini-grids to bridge electrification gaps through 2035.
- Caterpillar Inc.
- Cummins Inc.
- Generac Holdings Inc.
- Kohler Co.
- Mitsubishi Heavy Industries Ltd.
- Volvo Penta (AB Volvo)
- Wartsila Oyj Abp
- Rolls-Royce plc (mtu)
- MAN Energy Solutions SE
- Yanmar Holdings Co. Ltd.
- Hyundai Doosan Infracore
- Atlas Copco AB
- FG Wilson (Caterpillar)
- Perkins Engines Co. Ltd.
- Himoinsa S.L.
- Kirloskar Oil Engines Ltd.
- Guangxi Yuchai Machinery Group
- Mahindra Powerol
- Stamford-AvK (Cummins Generator Technologies)
- SDMO Industries (Kohler)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Grid-hardening investments in emerging markets
- 4.2.2 Boom in data-centre construction across Asia
- 4.2.3 Industrial automation demand for mission-critical backup
- 4.2.4 Military mobile power modernisation programmes
- 4.2.5 Micro-utility growth in rural Africa (mini-grids)
- 4.2.6 Maritime IMO III retrofit wave (aux. engines)
- 4.3 Market Restraints
- 4.3.1 Rapid fall in battery-storage LCOE
- 4.3.2 Tighter NOx & particulate limits in OECD markets
- 4.3.3 LNG-to-power small-scale deployments
- 4.3.4 OEM supply-chain exposure to Tier-1 chip shortages
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products & Services
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Capacity Range
- 5.1.1 Up to 75 kVA
- 5.1.2 75 to 375 kVA
- 5.1.3 375 to 750 kVA
- 5.1.4 750 to 2,000 kVA
- 5.1.5 Above 2,000 kVA
- 5.2 By Application
- 5.2.1 Stand-by
- 5.2.2 Prime/Continuous
- 5.2.3 Peak-shaving
- 5.3 By End User
- 5.3.1 Industrial
- 5.3.2 Commercial
- 5.3.3 Residential
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 United Kingdom
- 5.4.2.2 Germany
- 5.4.2.3 France
- 5.4.2.4 Spain
- 5.4.2.5 NORDIC Countries
- 5.4.2.6 Russia
- 5.4.2.7 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 ASEAN Countries
- 5.4.3.6 Australia and New Zealand
- 5.4.3.7 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 South Africa
- 5.4.5.4 Egypt
- 5.4.5.5 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 Cummins Inc.
- 6.4.3 Generac Holdings Inc.
- 6.4.4 Kohler Co.
- 6.4.5 Mitsubishi Heavy Industries Ltd.
- 6.4.6 Volvo Penta (AB Volvo)
- 6.4.7 Wartsila Oyj Abp
- 6.4.8 Rolls-Royce plc (mtu)
- 6.4.9 MAN Energy Solutions SE
- 6.4.10 Yanmar Holdings Co. Ltd.
- 6.4.11 Hyundai Doosan Infracore
- 6.4.12 Atlas Copco AB
- 6.4.13 FG Wilson (Caterpillar)
- 6.4.14 Perkins Engines Co. Ltd.
- 6.4.15 Himoinsa S.L.
- 6.4.16 Kirloskar Oil Engines Ltd.
- 6.4.17 Guangxi Yuchai Machinery Group
- 6.4.18 Mahindra Powerol
- 6.4.19 Stamford-AvK (Cummins Generator Technologies)
- 6.4.20 SDMO Industries (Kohler)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment