

|
시장보고서
상품코드
2122432
냉매 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Refrigerants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
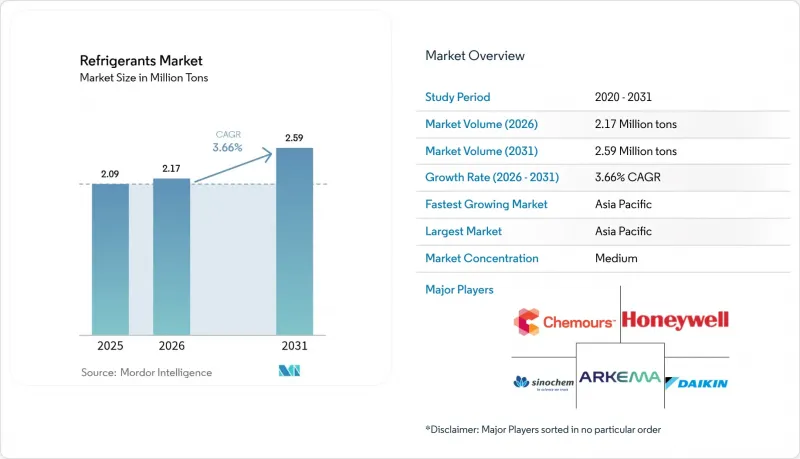
에 의하면, 냉매 시장 규모는 2025년 209만 톤으로 평가되었습니다. 2026년에는 217만 톤으로 확대되어 2026-2031년에 걸쳐 CAGR 3.66%로 성장을 지속하여, 2031년에는 259만 톤에 이를 것으로 예측됩니다.

본 보고서는 유형별(플루오로카본, 무기계, 탄화수소, 기타), 용도별(냉동, 공조, 기타 용도), 최종 사용자 산업별(주택 및 상업용 건물,식품 및 음료 가공, 의약품 및 헬스케어, 자동차·e-모빌리티, 기타), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다.
세계의 냉매 시장 동향 및 인사이트
아시아 신흥국에서의 실내 에어컨 및 차량용 에어컨 수요 증가
급속한 도시화로 인해 2급 및 3급 도시의 가정에서도 주거용 냉방 수요가 확대되고 있는 반면, 자동차 산업에서는 내연기관에서 전기 구동 시스템으로의 전환이 진행되고 있습니다. 중국의 히트펌프 출하 대수는 2030년까지 연간 5,000만 대에 달할 것으로 예측되며, 인도의 가정용 에어컨 보급률은 여전히 10% 미만에 머물러 있어 큰 잠재 수요가 있음을 보여주고 있습니다. 일본의 개정 프레온법과 한국의 효율 관리 프로그램에서는 GWP 상한선이 설정되어 있으며, 이에 따라 프로판, R-32, 선정된 HFO 혼합 가스의 조달이 진행되고 있습니다. 이 지역의 자동차 제조업체들은 차량 실내 및 배터리 루프용으로 R-1234yf를 표준화하고 있으며, 아시아태평양 전역에서 냉매 전환량이 가속화되고 있습니다. 주거 부문에서의 보급과 e-모빌리티 도입이 맞물려, 예측 기간 동안 냉매 시장에서 절대 톤수 기준으로 가장 큰 증가 요인이 되고 있습니다.
전기 차량의 열 관리 요건
전기자동차(EV) 배터리의 화학적 구성은 수명과 충전 속도를 보장하기 위해 좁은 온도 범위를 필요로 합니다. R-1234yf는 미국의 신형 소형 승용차에서 95%의 보급률을 자랑하며, 현재 전 세계 2억 2,000만 대의 차량에 탑재되어 있습니다. 한편, 기존 차량군에서는 R-134a를 동일 분자로 대체하는 개조 키트가 채택되고 있습니다. 차내 난방과 배터리 냉각을 통합한 히트펌프 구조가 일반 시장 부문으로 확산되고 있으며, -30°C에서 +45°C의 효율 곡선에 최적화된 A2L 계열 혼합 냉매의 소비를 촉진하고 있습니다. 압축기 제조업체는 하우징과 인버터의 조정을 통해 스크롤 소음을 6dBA 저감하고 있으며, 이는 프리미엄 EV 모델에 있어 중요한 사양으로 자리 잡고 있습니다. 이러한 시너지 효과로 인해 2020년대 중반까지 모빌리티 용도용 냉매 시장 규모가 확대될 전망입니다.
전 세계 HFC 단계적 감축 규제의 강화(키갈리 협정, EU의 F-가스 규정)
EU 규정 2024/573에 따라 HFC 할당량은 2025년 기준 수준의 60%에서 2036년에는 15%로 감축되며, 2050년까지 완전한 단계적 폐지가 목표로 설정되어 있습니다. 키갈리 개정안에 따른 유사한 생산 동결 조치는 모든 생산자에게 동시에 압박을 가하여 냉매 시장 전체공급을 위축시키고 현물 가격을 상승시키고 있습니다. 신규 시스템을 도입하는 사업자는 용량이 500tCO2e를 초과하는 경우 자동 누출 감지 시스템 도입이 의무화되어 있으며, 이로 인해 규정 준수 예산이 증가하고 자본이 생산량 확대에서 전환될 것입니다. 그 결과 발생하는 불확실성으로 인해 대규모 설비 도입에 대한 의사결정 주기가 지연되며, 전환기 중반의 예상 연평균 성장률(CAGR)이 2% 가까이 하락하게 됩니다.
부문별 분석
탄화수소계 냉매는 여러 F-가스 규제의 적용 제외 조치와 매력적인 총 소유 비용(TCO)의 경제성 덕분에 2025년에는 냉매 시장 점유율의 49.02%를 차지했습니다. 시장을 선도하는 기업들은 주거용 히트 펌프 및 플러그인형 상업용 캐비닛의 출하량이 두 자릿수 성장을 보이고 있다고 보고하는 한편, MEPS(최저 에너지 성능 기준) 개정을 채택한 지역에서는 R-290 스플릿형 유닛의 전 세계적 확산이 가속화되고 있습니다. 하이드로플루오로올레핀은 GWP가 750을 초과하는 냉매에 대한 규제상 사용 금지 기한이 임박한 자동차 및 고정식 HVAC 부문에서의 도입에 힘입어 9.86%라는 가장 높은 CAGR을 기록하고 있습니다. 이 두 가지 저 GWP 부문은 불소계 냉매 취급량의 감소를 상쇄하며, 냉매 시장 전체의 성장을 뒷받침하고 있습니다.
하류 시장에서는 암모니아나 CO₂와 같은 무기계 냉매 시장 규모가 대규모 식품 가공 공장이나 대형 슈퍼마켓에서 계속 확대되고 있습니다. 엔지니어들은 효율 향상을 위해 저단 루프에는 CO2를, 고단 루프에는 합성 냉매를 조합하는 설계를 채택하고 있으며, 이 구성은 캐스케이드 방식의 다양한 조합에 대한 최근 COP(성능 계수) 비교를 통해 그 유효성이 입증되었습니다. 데이터센터의 침지 냉각 및 제약용 냉동고가 CO₂의 성장을 뒷받침하는 한편, 암모니아는 창고용 칠러 분야에서 여전히 확고한 입지를 다지고 있습니다. 천연 냉매를 대상으로 한 탄소 크레딧 제도는 비즈니스 사례를 더욱 매력적으로 만들고, 기존 HFC에서 시장 점유율을 지속적으로 전환하도록 촉진하고 있습니다.
지역별 분석
2025년에 아시아태평양이 냉매 시장 점유율의 50.10%를 차지한 것은 해당 지역의 거대한 제조거점, 도시 지역의 급격한 기온 상승, 그리고 지원적인 정책 체계를 반영한 것입니다. 중국의 실내 에어컨 수출은 국내 보급 확대에 따라 증가하고 있으며, 수직 통합된 공급망을 통해 R-32와 R-290의 대량 유통이 정착되고 있습니다. 인도의 백색가전용 ‘생산 연계형 인센티브(PLI)’ 제도에는 저GWP 냉매 연구 개발에 대한 보조금이 포함되어 있어, 현지 부품 생태계 구축을 가속화하고 있습니다. 일본과 한국은 A2L 혼합 첨단 소재 개발을 주도하며, 그 배합 노하우를 지역 전체에 수출하고 있습니다. 동남아시아 국가들도 콜드체인 인프라에 대한 자금 지원에 이어, 냉매 시장에서 아시아태평양의 확고한 리더십을 더욱 공고히 하고 있습니다.
북미는 균형 잡힌 경로를 따르고 있으며, 미국의 AIAM법이 HFC 소비량 상한의 단계적 감축을 의무화하는 한편, HVAC 개조 분야에서 HFO 수요를 급성장하고 있습니다. 케모어스(Chemours)는 코퍼스 크리스티 공장의 생산 능력 확대로 인해 2025년 1분기에 옵티온(Option)의 매출이 40% 급증했습니다. 캐나다의 탄소 가격 제도로 인해 식품 소매 산업의 장비 사양은 천연 냉매로의 전환이 더욱 가속화되고 있습니다. 한편, 멕시코의 산업 지역에서는 전환 기간 동안 GWP 상한선 범위 내에서 공정 냉각용 불소계 냉매에 대한 수요가 증가하고 있습니다.
유럽은 가장 엄격한 규제 체계 하에서 대응을 추진하고 있습니다. ‘F-Gas 2024’의 할당량과 에코디자인 규정에 따라 각 OEM 업체들은 R-290 히트펌프를 대규모로 도입해야 하는 상황에 놓여 있으며, 독일과 프랑스의 보조금 제도가 이를 뒷받침하고 있습니다. 고온 환경에 최적화된 포장 기술 덕분에 남부 기후대에서도 초임계 CO₂가 슈퍼마켓의 표준 사양으로 자리 잡고 있습니다. 영국은 독자적인 할당 제도를 유지하고 있지만, EU의 일정에 부합하고 있어 유럽 전역에서 냉매 시장 전망은 점차 수렴되고 있습니다.
남미, 중동 및 아프리카와 같은 신흥 지역은 냉매 시장의 롱테일을 구성하고 있습니다. 단계적 감축 일정의 지연으로 인해 HFC 수요는 장기화되고 있지만, 1인당 냉방 수요 증가는 향후 저GWP 냉매 도입 주기를 촉진하고 있습니다. 인프라 격차에 대해서는 콜드체인 물류와 농업 생산성 향상을 결합한 다자간 개발은행의 프로그램을 통해 대응이 진행되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the refrigerants market size is expected to grow from 2.09 million tons in 2025 to 2.17 million tons in 2026 and is forecast to reach 2.59 million tons by 2031 at 3.66% CAGR over 2026-2031.
This report is Segmented by Type (Fluorocarbons, Inorganics, Hydrocarbons, Other Types), Application (Refrigeration, Air-Conditioning, Other Applications), End-User Industry (Residential and Commercial Buildings, Food and Beverage Processing, Pharmaceuticals and Healthcare, Automotive and E-Mobility, and More), and Geography (Asia-Pacific, North America, Europe, South America, Middle-East and Africa).
Global Refrigerants Market Trends and Insights
High Demand for Room and Car Air-Conditioners in Emerging Asia
Rapid urbanization is pushing residential cooling deeper into tier-2 and tier-3 city households while the automotive sector simultaneously swaps internal-combustion platforms for electric drivetrains. China's heat-pump shipments are projected to hit 50 million units annually by 2030, and India's household air-conditioner penetration remains under 10%, underscoring significant latent demand. Japan's revised F-Gas Law and South Korea's efficiency management program impose GWP ceilings that funnel procurement toward propane, R-32, and shortlisted HFO blends. Vehicle OEMs in the region are standardizing R-1234yf for cabin and battery loops, accelerating molecule transition volumes throughout Asia-Pacific. Together, residential uptake and e-mobility adoption underpin the largest absolute tonnage additions in the refrigerant market during the forecast window.
Electrified-Vehicle Thermal-Management Requirements
Electric vehicle (EV) battery chemistries demand narrow temperature windows for longevity and charging speed. R-1234yf enjoys 95% penetration in new U.S. light-duty vehicles, with 220 million cars worldwide now equipped, while legacy fleets adopt retrofit kits that swap out R-134a for the same molecule. Heat-pump architectures unifying cabin heating and battery cooling are spreading into mass-market segments, spurring consumption of blended A2L fluids optimized for -30 °C to +45 °C efficiency curves. Compressor suppliers have cut scroll noise by 6 dBA through housing and inverter tuning, a key specification for premium EV models. The aggregate effect widens the addressable refrigerant market for mobility applications through mid-decade.
Stringent Global HFC Phase-Down (Kigali, EU F-Gas)
EU Regulation 2024/573 cuts HFC quotas from 60% of baseline levels in 2025 to 15% in 2036, with full phase-out targeted by 2050. Similar freezes under the Kigali Amendment pressure all producers simultaneously, tightening supply and elevating spot prices across the refrigerant market. Operators installing new systems must adopt automated leak detection above 500 tCO2e capacity, raising compliance budgets and reallocating capital away from volume growth. The resulting uncertainty slows decision cycles for large installations, shaving nearly two percentage points from projected CAGR during mid-transition years.
Other drivers and restraints analyzed in the detailed report include:
- Ultralow-Temperature Freezers for mRNA-Type Vaccines
- Carbon-Credit Monetization for Natural Refrigerants
- High First-Cost and Handling Risk of Flammable A3/A2L Gases
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hydrocarbons commanded 49.02% refrigerant market share in 2025 on the back of exemption status under multiple F-Gas schedules and compelling cost-of-ownership economics. Market leaders report double-digit shipment growth into residential heat-pumps and plug-in commercial cabinets, while global roll-outs of R-290 split units accelerate in regions adopting MEPS revisions. Hydrofluoro-olefins are delivering the fastest 9.86% CAGR, propelled by automotive and stationary HVAC debuts where regulatory cut-off dates for GWP greater than 750 fluids are imminent. Collectively, these two low-GWP segments offset contracting fluorocarbon tonnage, anchoring overall refrigerant market growth.
Downstream, the refrigerant market size for inorganic options such as ammonia and CO2 continues to expand in large food-processing plants and big-box supermarkets. Engineers pair CO2 in low-stage loops with synthetic high-stage fluids for efficiency gains, an architecture validated by recent COP comparisons across cascade permutations. Data-center immersion cooling and pharma freezers add pocket growth for CO2, while ammonia remains entrenched in warehouse chillers. Natural-refrigerant carbon-credit programs further sweeten the business case, ensuring sustained share migration away from legacy HFCs.
Complete Report Scope:
- By Type
- Fluorocarbons
- Hydrochlorofluorocarbons (HCFC)
- Hydrofluorocarbons (HFC)
- Inorganics
- Ammonia
- Carbon Dioxide
- Other Inorganics
- Hydrocarbons
- Isobutane
- Propane
- Other Hydrocarbons
- Other Types (Hydrofluoro-olefins (HFO))
- Fluorocarbons
- By Application
- Refrigeration
- Domestic
- Commercial
- Transportation
- Industrial
- Air-Conditioning
- Stationary Room/Packaged
- Chillers
- Mobile
- Other Applications
- Refrigeration
- By End-user Industry
- Residential and Commercial Buildings
- Food and Beverage Processing
- Pharmaceuticals and Healthcare
- Automotive and e-Mobility
- Chemicals and Petrochemicals
- Other Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific's 50.10% refrigerant market share in 2025 reflects the region's outsized manufacturing base, urban temperature spikes, and supportive policy frameworks. China's room-air-conditioner exports grow with domestic uptake, locking in bulk R-32 and R-290 flows through vertically integrated supply chains. India's Production Linked Incentive (PLI) scheme for white goods includes grants for low-GWP refrigerant R&D, expediting local component ecosystems. Japan and South Korea anchor advanced-material development for A2L blends, exporting formulation know-how across the region. Southeast Asian economies follow with cold-chain infrastructure funding, reinforcing Asia-Pacific's reinforced leadership of the refrigerant market.
North America tracks a balanced path as the U.S. AIM Act mandates an HFC consumption-cap glide path while simultaneously turbo-charging demand for HFOs in HVAC retrofits. Chemours logged a 40% surge in Opteon sales during Q1 2025, enabled by its Corpus Christi capacity expansion. Canada's carbon-pricing architecture further skews equipment specifications toward natural refrigerants in food retail, whereas Mexico's industrial corridor demands process-cooling fluorocarbons under transitional GWP ceilings.
Europe navigates the tightest regulatory straitjacket. F-Gas 2024 quotas and eco-design rules push OEMs to deploy R-290 heat-pumps at scale, supported by German and French subsidy pools. Transcritical CO2 has become the default supermarket specification even in southern climates thanks to high-ambient optimization packages. The United Kingdom maintains an independent quota system but mirrors EU timelines, keeping the refrigerant market outlook convergent across the continent.
Emerging regions across South America and Middle East & Africa constitute the long-tail of the refrigerant market. Delayed phase-down schedules prolong HFC demand, yet rising per-capita cooling expectations seed future low-GWP adoption cycles. Infrastructure gaps are being addressed through multilateral development-bank programs that bundle cold-chain logistics with agricultural productivity mandates.
- A-Gas International Ltd
- AGC Inc.
- Arkema
- Brothers Gas
- Daikin Industries, Ltd.
- Dongyue Group
- Gulfcryo.
- Harp International Ltd
- Honeywell International Inc
- Linde PLC
- Messer SE & Co. KGaA
- Navin Fluorine International Ltd
- Orbia
- Shandong Yuean Chemical Industry Co., Ltd
- Sinochem Holdings Corporation Ltd
- SRF Limited
- The Chemours Company
- Zhejiang Juhua Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 High demand for room and car air-conditioners in emerging Asia
- 4.2.2 Expansion of refrigerated warehousing and 3PL cold-chain nodes
- 4.2.3 Electrified-vehicle thermal-management requirements
- 4.2.4 Ultralow-temperature freezers for mRNA-type vaccines
- 4.2.5 Carbon-credit monetisation for natural refrigerants
- 4.3 Market Restraints
- 4.3.1 Stringent global HFC phase-down (Kigali, EU F-Gas)
- 4.3.2 High first-cost and handling risk of flammable A3/A2L gases
- 4.3.3 Boom-bust price swings for next-gen HFO molecules
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Type
- 5.1.1 Fluorocarbons
- 5.1.1.1 Hydrochlorofluorocarbons (HCFC)
- 5.1.1.2 Hydrofluorocarbons (HFC)
- 5.1.2 Inorganics
- 5.1.2.1 Ammonia
- 5.1.2.2 Carbon Dioxide
- 5.1.2.3 Other Inorganics
- 5.1.3 Hydrocarbons
- 5.1.3.1 Isobutane
- 5.1.3.2 Propane
- 5.1.3.3 Other Hydrocarbons
- 5.1.4 Other Types (Hydrofluoro-olefins (HFO))
- 5.1.1 Fluorocarbons
- 5.2 By Application
- 5.2.1 Refrigeration
- 5.2.1.1 Domestic
- 5.2.1.2 Commercial
- 5.2.1.3 Transportation
- 5.2.1.4 Industrial
- 5.2.2 Air-Conditioning
- 5.2.2.1 Stationary Room/Packaged
- 5.2.2.2 Chillers
- 5.2.2.3 Mobile
- 5.2.3 Other Applications
- 5.2.1 Refrigeration
- 5.3 By End-user Industry
- 5.3.1 Residential and Commercial Buildings
- 5.3.2 Food and Beverage Processing
- 5.3.3 Pharmaceuticals and Healthcare
- 5.3.4 Automotive and e-Mobility
- 5.3.5 Chemicals and Petrochemicals
- 5.3.6 Other Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 France
- 5.4.3.3 United Kingdom
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share**/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 A-Gas International Ltd
- 6.4.2 AGC Inc.
- 6.4.3 Arkema
- 6.4.4 Brothers Gas
- 6.4.5 Daikin Industries, Ltd.
- 6.4.6 Dongyue Group
- 6.4.7 Gulfcryo.
- 6.4.8 Harp International Ltd
- 6.4.9 Honeywell International Inc
- 6.4.10 Linde PLC
- 6.4.11 Messer SE & Co. KGaA
- 6.4.12 Navin Fluorine International Ltd
- 6.4.13 Orbia
- 6.4.14 Shandong Yuean Chemical Industry Co., Ltd
- 6.4.15 Sinochem Holdings Corporation Ltd
- 6.4.16 SRF Limited
- 6.4.17 The Chemours Company
- 6.4.18 Zhejiang Juhua Co. Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


