|
시장보고서
상품코드
2122587
실험실 정보 시스템 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Laboratory Information System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 실험실 정보 시스템 시장 규모는 2025년 23억 4,000만 달러로 평가되었습니다. 2026년 26억 5,000만 달러에서 2031년까지 49억 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 13.08%를 나타낼 것으로 예측됩니다.

본 보고서는 구성 요소(소프트웨어(독립형 LIS 등) 및 서비스(도입·통합 등)), 제공 형태(On-Premise 등), 실험실 유형(임상병리 실험실 등), 최종 사용자(병원 및 진료소 등), 지역(북미, 유럽, 아시아태평양, 기타)별로 분류되어 있습니다. 본 보고서에서는 상기 각 부문별 시장 규모(단위 : 백만 미 달러)를 제시하고 있습니다.
세계의 실험실 정보 시스템 시장 동향 및 인사이트
전 세계 진단 검사 건수 증가
고령화, 만성 질환 스크리닝, 공중보건상의 의무로 인해 수작업 워크플로우에 부담이 가중되는 가운데, 전 세계 검체 수는 연간 6-8%의 속도로 증가하고 있습니다. 유럽 최대의 체인인 SYNLAB은 2024년에 6억 건 이상의 검사를 처리했으며, LIS를 활용한 분류 자동화를 통해 전분석 단계의 오류를 18% 줄였습니다. 차세대 시퀀싱에서는 현재 환자 1명당 기가바이트 단위의 데이터가 생성되므로, 실험실은 바이오인포매틱스에 대응한 LIS 모듈의 도입을 피할 수 없게 되었습니다. 인도에서는 Dr. Lal PathLabs가 연간 12-15%의 처리량 증가에 대응하는 중앙 집중형 클라우드 LIS를 통해 2,500개의 실험실과 4,000개의 검체 채취 센터의 물류를 관리하고 있습니다. 처리 능력의 향상에 따라 AI를 활용한 자동 검증에 대한 수요도 증가하고 있으며, 이를 통해 일상적인 생화학 검사의 소요 시간을 최대 30% 단축할 수 있게 되었습니다.
바이오뱅크 네트워크의 급속한 확대
정밀 의학 노력에 힘입어, 장기적인 검체 추적, 동의 관리 및 멀티오믹스 연동이 필요한 국가 차원의 바이오뱅크가 잇달아 탄생하고 있습니다. UK 바이오뱅크는 2024년에 50만 명의 참가자에 대한 전체 유전체 시퀀싱을 완료했으며, 이 획기적인 성과는 페더레이티드 LIS의 쿼리 기능에 의해 뒷받침되고 있습니다. 유럽의 ‘Genome of Europe’ 프로젝트와 미국의 ‘All of Us’ 프로그램은 ISO 20387 표준을 준수하면서 GDPR(EU 개인정보보호규정)에 부합하는 가명화를 지원하는 클라우드 네이티브 LIS 레이어에 의존하고 있습니다. 따라서 사전에 검증된 보관 이력(체인 오브 커스터디) 모듈을 제공하는 SaaS형 LIS 벤더에는 학술 컨소시엄 및 지역 연구센터로부터 큰 관심이 쏠리고 있습니다.
높은 총 소유 비용
하루에 100-500건의 검체를 처리하는 중규모 실험실에서는 라이선싱, 인터페이스, IT 지원에 연간 15만-40만 달러를 지출하고 있습니다. 분석 기기 1대당 인터페이스 비용이 5,000-1만 5,000달러가 들기 때문에 이익률이 압박받는 한편, 클라우드 구독 비용은 데이터 보관 기간에 따라 증가합니다. FHIR 매핑 및 맞춤형 보고서에 대한 컨설팅 비용은 시간당 200달러를 초과할 수 있으며, 교육 비용은 현재 시스템 운영 예산의 20-25%를 차지하고 있습니다.
부문별 분석
2025년에는 서비스가 실험실 정보 시스템 시장의 60.05%를 차지했으며, 그 수익은 2031년까지 연평균 13.99%의 성장률을 보일 것으로 전망됩니다. 검사 기관이 FHIR 매핑, AI 검증 및 여러 거점에 걸친 클라우드 오케스트레이션을 필요로 함에 따라, 실험실 정보 시스템 시장 내 서비스 규모는 확대되고 있습니다. SaaS 플랫폼은 영구 라이선스형 소프트웨어의 판매를 잠식하고 있지만, 도입 주기가 장기화됨에 따라 컨설팅 및 관리형 서비스에 대한 수요가 증가하고 있습니다.
관리형 지원 계약에는 현재 보안 패치 적용, 재해 복구, 인증 보고가 패키지화되어 있어, 이전에는 선택적 지출이었던 항목이 정기적인 요금으로 전환되고 있습니다. 사전 검증된 템플릿을 제공하는 벤더는 계약을 신속하게 확보할 수 있는 반면, ISO 15189 감사에 부합하는 교육 계약을 통해 컨설팅 프로젝트 파이프라인은 항상 풍부하게 유지되고 있습니다.
2025년에는 클라우드 모델이 실험실 정보 시스템 시장의 54.32%를 차지했습니다. 탄력적인 인프라 덕분에 실험실은 하드웨어를 과도하게 조달하지 않고도 인플루엔자 검사 수요의 급증에 대응할 수 있으며, 내장된 FHIR 엔드포인트를 통해 규정 준수 대응이 간소화됩니다. 서버 교체 및 사이버 보안 비용 증가에 따라, On-Premise 도입에 의존하는 실험실 정보 시스템 시장 규모는 축소되고 있습니다.
데이터 현지화 법에 따라 국경을 넘는 데이터 전송이 제한되는 지역에서는 하이브리드 배포가 여전히 유효하며, 기밀성이 높은 유전체 데이터를 현지에서 보관하면서 관리 모듈을 클라우드에서 운영할 수 있습니다. 각 벤더는 HIPAA 비즈니스 어소시에이트 계약 및 각국 고유의 GDPR(EU 개인정보보호규정) 대응 호스팅 영역을 제공함으로써 경쟁 우위를 확보하고 있습니다.
지역별 분석
북미는 2025년 매출의 43.57%를 차지했으며, 이는 도입 기반의 성숙도가 높고 규제 도입이 조기에 시작된 것을 반영합니다. 검사 기관들이 2027년 1월 FHIR 의무화 시한을 맞추기 위해 급속도로 대응을 진행하는 가운데, 미국이 업그레이드를 주도하고 있는 반면, 캐나다 각 주 보건 당국은 검사 결과 공유를 통일하기 위해 통합 클라우드 도입에 자금을 지원하고 있습니다. 멕시코에서는 민간 진단 기업들이 지방 도시로 사업을 확장함에 따라 꾸준한 성장을 보이고 있지만, 환율 변동으로 인해 자본 예산은 억제되고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 14.42%를 나타낼 것으로 예측되며, 실험실 정보 시스템 시장에서 가장 빠른 지역적 확장이 예상됩니다. 인도의 ISO 15189 인증 추진과 중국의 ‘건강 중국 2030’ 프로그램에 힘입어 3차 의료 기관 실험실의 디지털화가 진행되고 있습니다. Dr. Lal PathLabs와 같은 진단 체인은 클라우드 기반 LIS를 활용하여 2,500곳의 실험실을 실시간으로 모니터링하고, 2급 및 3급 도시 전반에 걸쳐 표준화된 표준 작업 절차(SOP)를 추진하고 있습니다. 일본과 호주에서는 LIS 결과 피드를 통합한 전국적인 의료 정보 교환 시스템에 대한 투자가 진행되고 있습니다.
유럽에서는 ‘헬스 데이터 스페이스(Health Data Space)’ 규정에 따라 국경을 초월한 실험실 간 상호 운용성이 의무화됨에 따라 도입이 안정적으로 진행되고 있습니다. 1,800개 이상의 병원 실험실을 보유한 독일은 의료기기 규정(MDR)의 소프트웨어 조항을 준수하기 위해 클라우드 전환을 주도하고 있습니다. 영국에서는 병리 검사 서비스를 29개의 지역 네트워크로 통합하고, 통일된 LIS 입찰을 실시함으로써 비용 절감과 검사 결과 회신 시간 단축을 도모하고 있습니다. 프랑스, 이탈리아, 스페인도 유사한 디지털화 경로를 따르고 있으며, 2031년까지 단계적으로 도입될 EHDS(유럽 건강 데이터 시스템)의 일정에 발맞추고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the laboratory information system market size is projected to expand from USD 2.34 billion in 2025 and USD 2.65 billion in 2026 to USD 4.90 billion by 2031, registering a CAGR of 13.08% between 2026 to 2031.
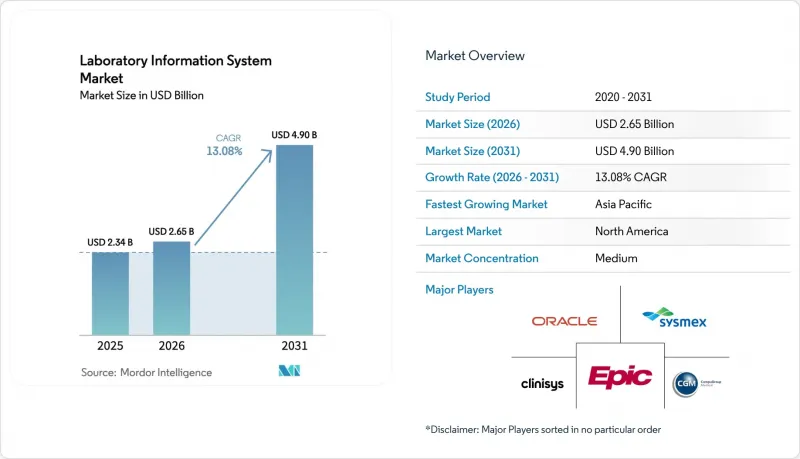
This report is Segmented by Component (Software [Stand-Alone LIS and More] and Service [Implementation & Integration and More]), Mode of Delivery (On-Premise, and More), Laboratory Type (Clinical Pathology Labs, and More), End User (Hospital and Clinics, and More), and Geography ( North America, Europe, Asia-Pacific, More). The Market Provides the Value (in USD Million) for the Above Segments.
Global Laboratory Information System Market Trends and Insights
Rising Global Diagnostic Testing Volumes
Worldwide specimen volumes are climbing 6-8% annually as aging populations, chronic disease screening, and public-health mandates stretch manual workflows. Europe's largest chain, SYNLAB, processed more than 600 million tests in 2024 and cut pre-analytical errors by 18% after automating triage through its LIS. Next-generation sequencing runs now generate gigabytes of data per patient, compelling laboratories to deploy bioinformatics-ready LIS modules. In India, Dr. Lal PathLabs manages logistics for 2,500 laboratories and 4,000 collection centers through a centralized cloud LIS that supports 12-15% annual volume growth. Rising throughput is also boosting demand for AI auto-verification that trims routine chemistry turnaround times by up to 30%.
Rapid Scale-Up of Biobank Networks
Precision-medicine initiatives are spawning national biobanks that require long-term specimen tracking, consent management, and multi-omics linkage. The UK Biobank finished whole-genome sequencing for 500,000 participants in 2024, a milestone that depends on federated LIS query capabilities . Europe's Genome of Europe project and the U.S. All of Us Program rely on cloud-native LIS layers that meet ISO 20387 standards while supporting GDPR-compliant pseudonymization. SaaS LIS vendors offering pre-validated chain-of-custody modules are therefore seeing strong inbound interest from academic consortia and regional research centers.
High Total Cost of Ownership
Mid-size laboratories with 100-500 daily accessions spend USD 150,000-400,000 per year on licenses, interfaces, and IT support. Per-analyzer interface fees of USD 5,000-15,000 erode margins, while cloud subscription costs scale with data retention. Consulting for FHIR mapping or custom reports can exceed USD 200 per hour, and training now represents 20-25% of go-live budgets.
Other drivers and restraints analyzed in the detailed report include:
- Cloud/SaaS LIS Lowering Capital Outlays
- AI-Powered Workflow Automation Modules
- Escalating Cybersecurity & HIPAA/GDPR Liabilities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services contributed 60.05% of the laboratory information system market in 2025, and their revenue is projected to rise 13.99% annually through 2031. The laboratory information system market size for services is growing because laboratories require FHIR mapping, AI validation, and multi-site cloud orchestration. SaaS platforms are eroding perpetual-license software sales, but longer implementation cycles push consulting and managed-services demand.
Managed support contracts now bundle security patching, disaster recovery, and accreditation reporting, converting previously discretionary spend into recurring fees. Vendors offering pre-validated templates win faster deals, while training engagements aligned with ISO 15189 audits keep consulting pipelines full.
Cloud models controlled 54.32% of the laboratory information system market share in 2025. Elastic infrastructure lets laboratories scale influenza testing surges without over-provisioning hardware, and built-in FHIR endpoints simplify compliance. The laboratory information system market size tied to on-premise installations is shrinking as server refresh and cybersecurity costs climb.
Hybrid deployments remain relevant where data-localization laws restrict cross-border transfer, allowing sensitive genomic data to stay on-site while administrative modules run in the cloud. Vendors secure a competitive advantage by offering HIPAA Business Associate Agreements and country-specific GDPR hosting zones.
Complete Report Scope:
- By Component
- Software
- Stand-alone LIS
- Integrated LIS / EHR-centric
- SaaS LIS Platforms
- Services
- Implementation & Integration
- Maintenance & Support
- Training & Consulting
- Software
- By Mode of Delivery
- On-Premise
- Cloud-Based
- Hybrid
- By Laboratory Type
- Clinical Pathology Labs
- Anatomic Pathology Labs
- Molecular Diagnostics Labs
- Blood Banks & Biobanks
- Other Specialized Labs
- By End User
- Hospitals & Clinics
- Laboratories
- Academic & Research Institutes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of APAC
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 43.57% of 2025 revenue, reflecting high installed-base maturity and early regulatory triggers. The United States leads upgrades as laboratories race to meet the January 2027 FHIR mandate, while Canada's provincial health authorities fund consolidated cloud rollouts to harmonize result sharing. Mexico shows steady gains as private diagnostic firms expand into secondary cities, though currency volatility tempers capital budgets.
Asia-Pacific is projected to post 14.42% CAGR, the fastest regional expansion in the laboratory information system market. India's ISO 15189 accreditation drive and China's Healthy China 2030 program are digitizing tertiary hospital labs . Diagnostic chains such as Dr. Lal PathLabs leverage cloud LIS to monitor 2,500 labs in real time, promoting standardized SOPs across tier-2 and tier-3 cities. Japan and Australia invest in national health information exchanges that embed LIS result feeds.
Europe enjoys stable uptake as the Health Data Space regulation mandates cross-border laboratory interoperability. Germany, with more than 1,800 hospital labs, leads cloud migration to comply with Medical Device Regulation software clauses. The United Kingdom consolidates pathology services into 29 regional networks that issue unified LIS tenders to cut costs and improve turnaround. France, Italy, and Spain follow similar digitization arcs, synchronized with phased EHDS deadlines through 2031.
- Aspyra, LLC
- Cirdan
- Clinisys, Inc.
- Comp Pro Med
- CompuGroup Medical
- Creliohealth
- Dedalus Global
- Dendi Software
- EasySolution
- Epic Systems Corporation.
- GPI Spa
- LigoLab Information Systems
- NovoPath
- Oracle
- Osplabs
- Prolis LIS
- Soft Computer Consultants.
- Sysmex
- Werfen, S.A.
- XiFin, Inc.
- eLabNext B.V.
- CGM SCHUYLAB
- SoftTech Health LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Diagnostic Testing Volumes
- 4.2.2 Rapid Scale-Up Of Biobank Networks
- 4.2.3 Cloud/SaaS LIS Lowering Capital Outlays
- 4.2.4 AI-Powered Workflow Automation Modules
- 4.2.5 Mandatory LIS-EHR Interoperability
- 4.2.6 Edge-LIS Micro-Appliances
- 4.3 Market Restraints
- 4.3.1 High Total Cost of Ownership
- 4.3.2 Escalating Cybersecurity Liabilities
- 4.3.3 Shortage Of LIS-Literate Informaticians
- 4.3.4 Volatile Open-API Standards
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD Million)
- 5.1 By Component
- 5.1.1 Software
- 5.1.1.1 Stand-alone LIS
- 5.1.1.2 Integrated LIS / EHR-centric
- 5.1.1.3 SaaS LIS Platforms
- 5.1.2 Services
- 5.1.2.1 Implementation & Integration
- 5.1.2.2 Maintenance & Support
- 5.1.2.3 Training & Consulting
- 5.1.1 Software
- 5.2 By Mode of Delivery
- 5.2.1 On-Premise
- 5.2.2 Cloud-Based
- 5.2.3 Hybrid
- 5.3 By Laboratory Type
- 5.3.1 Clinical Pathology Labs
- 5.3.2 Anatomic Pathology Labs
- 5.3.3 Molecular Diagnostics Labs
- 5.3.4 Blood Banks & Biobanks
- 5.3.5 Other Specialized Labs
- 5.4 By End User
- 5.4.1 Hospitals & Clinics
- 5.4.2 Laboratories
- 5.4.3 Academic & Research Institutes
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of APAC
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Aspyra, LLC
- 6.3.2 Cirdan
- 6.3.3 Clinisys, Inc.
- 6.3.4 Comp Pro Med
- 6.3.5 CompuGroup Medical
- 6.3.6 Creliohealth
- 6.3.7 Dedalus Global
- 6.3.8 Dendi Software
- 6.3.9 EasySolution
- 6.3.10 Epic Systems Corporation.
- 6.3.11 GPI Spa
- 6.3.12 LigoLab Information Systems
- 6.3.13 NovoPath
- 6.3.14 Oracle Corporation
- 6.3.15 Osplabs
- 6.3.16 Prolis LIS
- 6.3.17 Soft Computer Consultants.
- 6.3.18 Sysmex Corporation
- 6.3.19 Werfen, S.A.
- 6.3.20 XiFin, Inc.
- 6.3.21 eLabNext B.V.
- 6.3.22 CGM SCHUYLAB
- 6.3.23 SoftTech Health LLC
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment