

|
시장보고서
상품코드
2122650
자율주행 트럭 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Autonomous Truck - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 자율주행 트럭 시장 규모는 2026년에 426억 3,000만 달러로 추정되고, 2031년까지 742억 3,000만 달러에 이를 것으로 예측되며, CAGR은 11.73%로 성장이 전망됩니다.
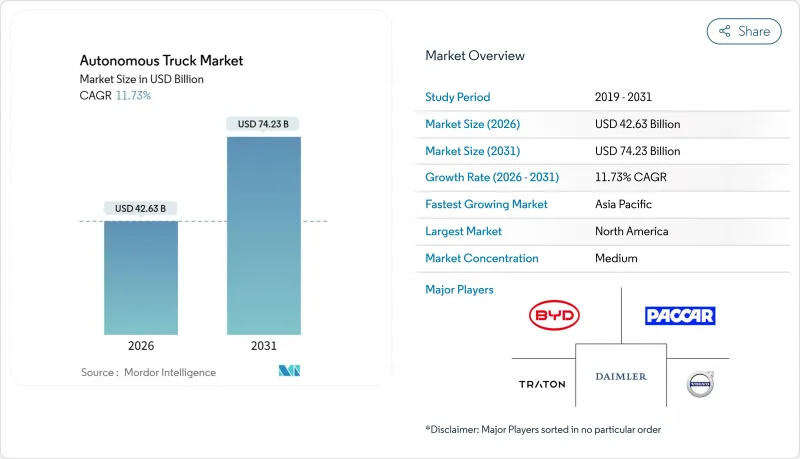
본 보고서는 트럭 유형별(소형 트럭 등), 자율주행 레벨별(SAE 레벨 1-2(운전 지원) 등), ADAS 기능별(어댑티브 크루즈 컨트롤, 차선 이탈 경고 등), 구성 요소별(라이더, 레이더, 카메라 등), 구동 방식별(내연 기관, 배터리식 전기차, 하이브리드, 기타), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 및 수량(대)으로 제시되어 있습니다.
세계의 자율주행 트럭 시장 동향 및 인사이트
운전기사 부족과 장거리 운송 인건비 상승
만성적인 운전기사 부족과 인건비 급등으로 인해 화물 운송의 경제성은 자동화된 장거리 운송 업무에 유리한 방향으로 재정의되고 있습니다. 미국 연방자동차운송안전국(FMCSA)은 인간 운전자의 경우 14시간 중 11시간으로 운전 시간을 제한하고 있으며, 이 규제로 인해 자산 이용률은 하루의 약 절반으로 제한되고 있습니다. 지도에 표시된 주간 고속도로를 주행하는 자율주행 트랙터는 주로 급유·충전, 점검 및 유지보수로 인한 제한을 받는 경우를 제외하고는 장시간 가동할 수 있습니다. ATA(전미 트럭 운송 협회)의 보고에 따르면, 대형 트럭(FTL) 운전자의 이직률은 시기에 따라 90% 전후 또는 그 이상의 수준에 달하고 있어, 예측 가능한 노선에서 레벨 4 트럭 도입에 대한 인센티브가 높아지고 있습니다. 유럽과 일본의 운송 회사들도 젊은 노동자들이 장거리 운송 직업을 기피하는 경향이 있어, 유사한 인구 통계학적 압박에 직면해 있습니다. 따라서 허브 간을 연결하는 자율 주행 셔틀을 통해 운송 사업자는 규제의 대상이 되는 ‘퍼스트 마일’ 및 ‘라스트 마일’ 노선에 제한된 수의 운전자를 재배치할 수 있게 됩니다.
연중무휴 24시간 허브 간 물류에 대한 수요
전자상거래의 성장과 적시 생산(JIT)으로 인해, 수동 운전으로는 운전 시간 규제 하에서 유지할 수 없는 끊김 없는 화물 유통에 대한 수요가 발생하고 있습니다. 고정 터미널 간을 주행하는 자율주행 트럭이라면, 휴식 시간 의무를 위반하지 않고 24시간 체제의 서비스를 제공할 수 있습니다. 화물 통합 사업자들은 이미 트랙터의 이용률을 대폭 개선하기 위한 야간 시범 노선(예: 댈러스-휴스턴)에 대한 실증 실험을 진행하고 있습니다. 중국의 국가 현대화 계획에서는 자율 주행 화물 운송을 위한 주요 제조 회랑이 지정되어 있으며, 평균 운송 시간을 대폭 단축하는 것이 목표로 설정되어 있습니다. 소매업체와 제3자 물류(3PL) 제공업체들은 특히 현물 운임이 3배로 치솟는 일이 드물지 않은 계절적 수요 급증기에 자율 주행을 통한 연속 운행을 운전자 확보의 불안정성에 대한 헤지 수단으로 간주하고 있습니다.
제각각인 국제 규제와 국경을 초월한 책임
법제도의 차이로 인해 자율주행 트럭 시장은 지역별로 분열되어 있습니다. 독일에서는 승인 및 감독을 조건으로, 특정 운행 구역 내 레벨 4 자율 주행을 위한 법적 체계가 확립되어 있습니다. 그러나 프랑스나 스페인에서는 여전히 안전 운전자의 동승이 의무화되어 있어, 국경을 넘는 물류를 방해하는 불연속성이 발생하고 있습니다. 미국에서는 자율주행에 관한 규제가 주로 주 차원에서 관리되고 있기 때문에 보험 및 데이터 공유에 관한 의무가 모자이크처럼 산재해 있습니다. OEM, 소프트웨어 제공업체, 그리고 차량 운영사 간의 과실 배분에 관한 책임 소재는 여전히 미해결 상태입니다. 이러한 불확실성으로 인해 보험료가 급등하고 있으며, 판례가 안정화될 때까지 중소규모 운송업체들이 투자를 주저하는 요인이 되고 있습니다. 규제 조화를 위한 노력은 계속되고 있지만, 그 일정은 현재 예측 기간을 초과하고 있어 결과적으로 성장이 억제되고 있습니다.
부문 분석
대형 트랙터는 인건비 절감과 높은 주행 거리로 인해 투자 회수가 극대화되는 장거리 운송 분야에서 압도적인 입지를 차지하고 있어, 2025년 매출의 46.57%를 차지했습니다. 반면, 소형 트럭은 적재량 상한이 낮아 고가의 센서 군이 갖는 경제적 이점이 희석되기 때문에 여전히 틈새 시장에 머물러 있습니다. 중형 플랫폼은 시장 규모는 작지만, 예측 가능한 교통 패턴이 나타나는 지오펜스 구역 내의 지역 운송 및 라스트 마일 경로에 힘입어 2026-2031년 연평균 성장률(CAGR) 13.34%로 성장할 전망입니다. 자율주행 트럭 시장은 레벨 4 시스템을 탑재한 전용 클래스 6 박스 트럭을 활용하여 소매업체들이 마이크로 풀필먼트 센터를 연결함으로써 혜택을 보고 있습니다.
중형 트럭의 자율주행 전환은 대도시권 내 전자상거래 밀도 증가와 일치하고 있습니다. 잦은 출발과 정지를 반복하는 주행 주기는 전동화에 적합하며, 전기 구동 시스템은 자율주행 제어 로직과 효율적으로 통합됩니다. 대형 트랙터는 계속해서 여러 주에 걸친 운송 노선에서 시험 운행을 진행하고 있지만, 규제상의 위험으로 인해 투자는 무인 주행이 법령에 명시적으로 허용된 지역에 집중되고 있습니다. 경트럭의 시험 운용은 속도 제한이 있는 캠퍼스 환경을 중심으로 진행되고 있으며, 적재량과 자율주행의 경제성이 동시에 개선되어야 비로소 더 대규모로 확대될 수 있을 것으로 시사되고 있습니다. 전반적으로 이러한 동향은 중형 트럭이 자율주행 트럭 시장에서 가장 빠르게 성장하고 있는 분야임을 뒷받침하고 있습니다.
SAE 레벨 1-2의 운전 지원 시스템은 2025년 자율주행 트럭 시장의 71.87%를 차지했으며, 이는 어댑티브 크루즈 컨트롤 및 차선 유지 기능의 도입 대수가 매우 많음을 반영합니다. 그러나 텍사스주, 애리조나주, 바이에른주에서 주 정부가 승인한 샌드박스에서 지도화된 고속도로에서의 완전 무인 주행이 허용되고 있기 때문에 레벨 4 플랫폼은 2031년까지 연평균 성장률(CAGR) 15.21%로 확대될 것으로 예측됩니다. 레벨 3 시스템의 자율주행 트럭 시장 규모는 운전자에게 운전권을 넘겨야 하는 요건이 법적 책임 위험을 초래하여 많은 운송 회사가 이를 회피하고 있기 때문에 여전히 소규모에 머물러 있습니다. 레벨 5 완전 자율주행의 경우, 센서 및 연산 능력의 제약으로 인해 현재 예측 기간 내 실현은 어려운 상황입니다.
상업용 시범 운영을 통해 레벨 4 고속도로 시범 노선이 지리적 완전 커버리지를 필요로 하지 않으면서도 경제적 이익의 상당 부분을 확보할 수 있음이 입증되었습니다. 원격 모니터링 센터가 여러 대의 트랙터를 모니터링함으로써 노동 생산성이 향상됩니다. 안전 규제 당국은 모든 장소에서의 이론적 완벽성보다는 정의된 운영 영역 내의 성능에 중점을 두고 있으며, 이로 인해 특정 노선에서의 도입을 위한 인증이 가속화되고 있습니다. 레벨 1-2 기능은 계속해서 필수 안전 기준으로 유지되겠지만, 총 시장 규모(TAM)에 대한 기여도는 시간이 지남에 따라 감소할 것입니다. 그 결과, 레벨 4 시스템이 자율주행 트럭 시장의 주요 수익원이 될 것입니다.
지역별 분석
북미는 2025년 매출의 37.46%를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 9.52%를 나타낼 것으로 전망됩니다. 여러 주에서 공공 도로에서의 무인 주행 시험을 승인하고 있어, 이 지역은 최대 규모의 상용 시험장이 되었습니다. 미국 교통부(DOT)가 지정한 10곳의 자율주행 차량 시험장이 시험 및 검증을 지원하고 있으며, 법규의 조화가 진전되면 멕시코와 캐나다로 향하는 국경을 넘는 운송 노선도 혜택을 볼 전망입니다. 밀집된 주간 화물 운송 네트워크와 친환경 운송에 대한 넉넉한 보조금이 장거리 운송, 냉장 운송, 소포 운송 각 부문의 지속적인 수요를 뒷받침하고 있습니다.
유럽 시장은 2031년까지 연평균 성장률(CAGR) 9.43%로 확대될 것으로 예측됩니다. EU의 신형 대형 차량에 대한 CO₂ 배출 기준은 2030년까지 약 45%, 2035년까지 65%, 2040년까지 90%(기준치 대비) 감축을 목표로 하고 있으며,차량 카테고리별로 구체적인 규정이 마련됨에 따라 전기차와 자율주행 기술의 결합에 대한 투자가 촉진되고 있습니다. 독일은 전용 아우토반 회랑을 구축하여 주도적인 역할을 수행하는 한편, 프랑스와 스페인은 안전 운전 관련 규정 덕분에 꾸준한 속도로 진전을 보이고 있습니다. 동유럽은 인프라와 자금 조달이 성숙해 가는 단계에 있으며, 여전히 초기 단계에 머물러 있습니다. 서아시아에서는 정부계 펀드가 24시간 가동되는 자율주행 컨테이너 셔틀을 통해 항만 물류의 현대화를 추진하고 있어 두 자릿수의 성장을 보이고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 13.33%로 가장 빠르게 성장할 것으로 전망되며, 이는 중국의 국가 차원 시험 구역과 일본 및 한국의 정부 지원 트럭 플래토닝 프로그램을 반영한 것입니다. 제조업 집적지가 밀집해 있고 노동력의 고령화가 도입을 가속화하고 있습니다. 중국의 광둥만 지역에서는 공장과 항만 터미널을 연결하는 전용 차로에서 세계 최대 규모의 무인 트럭 편대가 운영되고 있습니다. 한국은 커넥티드 오토노미에 특화된 5G 지원 고속도로에 막대한 투자를 하고 있습니다. 동남아시아 국가들은 센서 비용이 하락하고 자금 조달 메커니즘이 현지 상황에 적응할 때까지 관망하는 자세를 취하고 있습니다. 전반적으로 화물 수송량 증가와 지원적인 정책이 자율주행 트럭 시장에서 이 지역의 주도적 위치를 뒷받침하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the autonomous truck market size reached USD 42.63 billion in 2026 and is projected to attain USD 74.23 billion by 2031, representing an 11.73% CAGR.
This report is Segmented by Truck Type (Light-Duty Trucks, and More), Level of Autonomy (SAE Level 1-2 (Driver Assist), and More), ADAS Features (Adaptive Cruise Control, Lane Departure Warning, and More), Component (LIDAR, RADAR, Cameras, and More), Drive Type (IC Engine, Battery-Electric, Hybrid, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Autonomous Truck Market Trends and Insights
Driver Shortage and Rising Line-Haul Labor Cost
Chronic gaps in driver availability and escalating wages redefine freight economics in favor of automated line-haul operations. The Federal Motor Carrier Safety Administration limits human operators to 11 driving hours within a 14-hour window, a regulation that caps asset utilization at roughly half of every day. Autonomous tractors running mapped interstate corridors can operate for extended hours, limited mainly by fueling/charging, inspections, and maintenance. ATA-reported large-truckload driver turnover has been around/above 90% in some periods, intensifying the incentive to deploy Level 4 trucks on predictable lanes. European and Japanese fleets face similar demographic pressure as younger workers avoid long-haul careers. Autonomous hub-to-hub shuttles, therefore, enable carriers to redeploy scarce human drivers to first-mile and last-mile routes that remain regulation-bound.
Demand for 24/7 Hub-to-Hub Logistics
E-commerce growth and just-in-time manufacturing create demand for nonstop freight flows that manual operations cannot sustain under hours-of-service rules. Autonomous trucks on fixed terminals can deliver round-the-clock service without contravening rest mandates. Freight integrators have already demonstrated overnight pilot lanes (e.g., Dallas-Houston) aimed at materially improving tractor utilization. China's national modernization plan designates key manufacturing corridors for autonomous freight, targeting significant reductions in average transit time. Retailers and third-party logistics providers see continuous autonomy as a hedge against driver-availability volatility, especially during seasonal spikes when spot rates often triple.
Patchwork Global Regulation and Cross-Border Liability
Divergent legal frameworks divide the autonomous truck market across regions. Germany has established a legal framework for Level 4 autonomous driving in defined operating areas, subject to approval and oversight; however, it still requires safety drivers in France and Spain, creating a discontinuity that disrupts cross-border logistics. The United States governs autonomy largely at the state level, resulting in a mosaic of insurance and data-sharing mandates. Liability allocation remains unresolved regarding the distribution of fault among the OEM, software provider, and fleet operator. Such uncertainty elevates insurance premiums and deters small and mid-size carriers from investing until precedents stabilize. Harmonization efforts continue, but the timeline spans beyond the current forecast horizon, thereby tempering growth.
Other drivers and restraints analyzed in the detailed report include:
- Collaboration of Autonomy with Zero-Emission Powertrains
- Edge-AI Foundation Models Cut Validation Cycles
- High LiDAR/Sensor-Suite Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Heavy-duty tractors retained 46.57% of 2025 revenue due to their dominance in long-haul applications where labor savings and high mileage maximize payback. Light-duty trucks remain niche because lower payload limits dilute the economic advantage of costly sensor suites. Medium-duty platforms account for a smaller base yet will advance at a 13.34% CAGR from 2026 to 2031, driven by regional-haul and last-mile routes within geofenced areas that experience predictable traffic patterns. The autonomous truck market benefits from retailers linking micro-fulfillment centers via dedicated Class 6 box trucks outfitted with Level 4 stacks.
The shift toward medium-duty autonomy aligns with rising e-commerce density inside metropolitan regions. High stop-start duty cycles favor electrification, and electric drivetrains integrate efficiently with autonomous control logic. Heavy-duty tractors continue to test multi-state corridors, yet regulatory risk concentrates investment in locations where statutes explicitly permit driverless operation. Light-duty experimentation centers on campus environments where speed is limited, suggesting that broader scale will follow only when combined payload and autonomy economics improve. Overall, these dynamics reinforce medium-duty trucks as the fastest growing slice of the autonomous truck market.
SAE Level 1-2 driver-assist systems captured 71.87% of the 2025 autonomous truck market, reflecting a large installed base of adaptive cruise control and lane-keeping features. However, Level 4 platforms are projected to scale at a 15.21% CAGR through 2031 as state-approved sandboxes in Texas, Arizona, and Bavaria allow fully driverless operation on mapped highways. The autonomous truck market size for Level 3 systems remains modest because handoff requirements create liability risk that many fleets avoid. Level 5 universal autonomy remains beyond the current forecast window due to sensor and compute constraints.
Commercial pilots show that Level 4 highway-pilot routes capture most of the economic benefit without requiring complete geographic coverage. Remote supervision centers monitor multiple tractors, amplifying labor productivity. Safety regulators focus on performance within defined operating domains rather than theoretical perfection everywhere, which accelerates certification for corridor-specific deployments. Level 1-2 features will continue as mandatory safety baselines, yet their contribution to total addressable value diminishes over time. Consequently, Level 4 systems become the primary revenue engine of the autonomous truck market.
Complete Report Scope:
- By Truck Type
- Light-Duty Trucks
- Medium-Duty Trucks
- Heavy-Duty Trucks
- By Level of Autonomy
- SAE Level 1- 2 (Driver Assist)
- SAE Level 3 (Conditional)
- SAE Level 4 (High)
- SAE Level 5 (Full)
- By ADAS Feature
- Adaptive Cruise Control
- Lane Departure Warning
- Traffic Jam Assist
- Highway Pilot
- Automatic Emergency Braking
- Blind-Spot Detection
- Lane-Keeping Assist
- By Component
- LiDAR
- RADAR
- Cameras
- Ultrasonic and Other Sensors
- AI Compute Modules
- By Drive Type
- Internal-Combustion
- Battery-Electric
- Hybrid
- Hydrogen Fuel-Cell
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle-East and Africa
- North America
Geography Analysis
North America accounted for 37.46% of 2025 revenue and is projected to register a 9.52% CAGR through 2031. Multiple states authorize driverless testing on public highways, making the region the largest commercial sandbox. Ten U.S. DOT-designated Automated Vehicle Proving Grounds support testing and validation, and cross-border lanes into Mexico and Canada stand to benefit once legal harmonization advances. Dense interstate freight networks and generous clean-transport subsidies underpin sustained demand across long-haul, refrigerated, and parcel segments.
Europe is forecasted to expand at a 9.43% CAGR to 2031. EU CO2 standards for new heavy-duty vehicles aim for a reduction of ~45% by 2030, 65% by 2035, and 90% by 2040 (compared to the baseline), with specific rules in place for each vehicle category, catalyzing investment in combined electric and autonomous technologies. Germany leads with dedicated autobahn corridors, while France and Spain progress at a measured pace due to safety driver stipulations. Eastern Europe remains early-stage as infrastructure and financing mature. Western Asia shows double-digit growth as sovereign wealth funds modernize port logistics through 24-hour autonomous container shuttles.
Asia-Pacific will grow fastest at a 13.33% CAGR, reflecting national pilot zones in China and government-backed truck platooning programs in Japan and South Korea. Dense manufacturing clusters and aging workforces accelerate adoption. China's Greater Bay Area supports the world's largest fleet of driverless trucks on dedicated lanes linking factories to port terminals. South Korea invests heavily in 5G-enabled highways tailored for connected autonomy. Southeast Asian nations adopt a wait-and-see approach until sensor costs fall and financing mechanisms adapt to local conditions. Collectively, rising freight volumes and supportive policy drive regional leadership in the autonomous truck market.
- AB Volvo
- Daimler Truck AG
- Traton SE
- PACCAR Inc.
- BYD Co. Ltd.
- Tesla Inc.
- TuSimple
- Aurora Innovation
- Waymo Via
- Plus.ai
- Torc Robotics
- Kodiak Robotics
- Nikola Corp.
- Einride
- Embark Technology
- Hyzon Motors
- Gatik AI
- Volvo - Uber ATG JV
- Scania AB
- Navistar
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Driver Shortage and Rising Line-Haul Labor Cost
- 4.2.2 Demand for 24/7 Hub-to-Hub Logistics
- 4.2.3 Collaboration of Autonomy with Zero-Emission Powertrains
- 4.2.4 Edge-AI Foundation Models Cut Validation Cycles
- 4.2.5 Green-Corridor Tax Incentives (IRA, Fit-For-55)
- 4.2.6 Tightening Safety Regulations
- 4.3 Market Restraints
- 4.3.1 Patchwork Global Regulation and Cross-Border Liability
- 4.3.2 High Lidar/Sensor-Suite Costs
- 4.3.3 Cyber-Security and OTA Update Risks
- 4.3.4 Opaque Transformer Models Hinder ISO-26262 Compliance
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Truck Type
- 5.1.1 Light-Duty Trucks
- 5.1.2 Medium-Duty Trucks
- 5.1.3 Heavy-Duty Trucks
- 5.2 By Level of Autonomy
- 5.2.1 SAE Level 1- 2 (Driver Assist)
- 5.2.2 SAE Level 3 (Conditional)
- 5.2.3 SAE Level 4 (High)
- 5.2.4 SAE Level 5 (Full)
- 5.3 By ADAS Feature
- 5.3.1 Adaptive Cruise Control
- 5.3.2 Lane Departure Warning
- 5.3.3 Traffic Jam Assist
- 5.3.4 Highway Pilot
- 5.3.5 Automatic Emergency Braking
- 5.3.6 Blind-Spot Detection
- 5.3.7 Lane-Keeping Assist
- 5.4 By Component
- 5.4.1 LiDAR
- 5.4.2 RADAR
- 5.4.3 Cameras
- 5.4.4 Ultrasonic and Other Sensors
- 5.4.5 AI Compute Modules
- 5.5 By Drive Type
- 5.5.1 Internal-Combustion
- 5.5.2 Battery-Electric
- 5.5.3 Hybrid
- 5.5.4 Hydrogen Fuel-Cell
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Spain
- 5.6.3.5 Russia
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 India
- 5.6.4.2 China
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Turkey
- 5.6.5.4 Egypt
- 5.6.5.5 South Africa
- 5.6.5.6 Rest of Middle-East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 AB Volvo
- 6.4.2 Daimler Truck AG
- 6.4.3 Traton SE
- 6.4.4 PACCAR Inc.
- 6.4.5 BYD Co. Ltd.
- 6.4.6 Tesla Inc.
- 6.4.7 TuSimple
- 6.4.8 Aurora Innovation
- 6.4.9 Waymo Via
- 6.4.10 Plus.ai
- 6.4.11 Torc Robotics
- 6.4.12 Kodiak Robotics
- 6.4.13 Nikola Corp.
- 6.4.14 Einride
- 6.4.15 Embark Technology
- 6.4.16 Hyzon Motors
- 6.4.17 Gatik AI
- 6.4.18 Volvo - Uber ATG JV
- 6.4.19 Scania AB
- 6.4.20 Navistar
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


