

|
시장보고서
상품코드
2122658
골판지 포장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Corrugated Board Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 골판지 포장 시장 규모는 2,057억 4,000만 달러로 추정되고 2025년 1,983억 4,000만 달러에서 확대해, 2031년에는 2,471억 달러에 이를 것으로 예측됩니다.
2026-2031년 동안의 연평균 성장률(CAGR)은 3.73%를 나타낼 전망입니다.

본 보고서는 재료 유형(버진 컨테이너보드, 재생 컨테이너보드), 박스 형태(슬롯이 있는 박스, 텔레스코픽 박스, 기타), 최종 사용자 산업(식품, 음료, 퍼스널케어·가정용품, 기타), 보드 유형(단벽, 이중벽, 기타),인쇄 기술(플렉소 인쇄, 디지털, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 골판지 포장 시장 동향 및 인사이트
친환경 소재 의무화로 섬유 소재로의 전환 촉진
새로운 재활용 가능성에 관한 규제로 인해 포장재 선택은 섬유 계열로 기울고 있습니다. 2030년까지 모든 포장을 재활용 가능하게 하라는 EU의 요구 사항에 더해, 플라스틱에 대한 재활용 재료의 최소 함유율 기준이 설정됨에 따라 골판지는 규정 준수에 있어 위험이 낮은 선택지가 되었습니다. 미국에서는 재활용 가능한 기재를 장려하는 요금 체계가 도입되어, 플라스틱 포장에 비해 최대 15%의 비용 우위가 발생하고 있습니다. 플라스틱 재활용 인프라 구축에는 2030년 기한을 훨씬 초과하는 시간이 소요되기 때문에 각 브랜드는 사양 변경을 가속화하고 있습니다. 골판지의 71-76%에 달하는 회수율은 감사 증거 관리를 간소화하고, 기업의 ESG 공약을 지원하며, 벌칙 위험을 경감시킵니다. 제지 제조업체에 따르면, 소매업체의 평가 기준을 충족하기 위해 가공업체들이 생산 라인을 재조정하고 있어, 섬유계 SKU의 수주 리드타임이 2주 단축되었다고 합니다.
전자상거래 소포의 폭발적인 증가로 포장 사양 재구축
세계 전자상거래 출하량은 2024년 2,200억 개에서 2029년에는 3,400억 개에 달할 것으로 예측되며, 낙하 테스트를 통한 내구성과 부피 중량 효율과 같은 기능적 측면의 우선순위가 높아지고 있습니다. 현재 대형 물류 사업자를 통해 출하되는 소포의 4분의 1 이상을 이중벽 골판지나 마이크로플루트 골판지가 차지하고 있습니다. 이에 대응해 설비 공급업체들은 인건비를 40% 절감하는 동시에 충전재 필요량을 줄여, 주문 1건당 재료비를 15% 절감하는 온디맨드 상자 제작 시스템으로 대응하고 있습니다. 구독형 전자상거래 사업자들은 브랜드 스토리를 전달하기 위해 인쇄 가능한 내면면을 지정하고 있으며, 이에 따라 배송 용기 내부에 디지털 인쇄 그래픽을 적용하는 것이 더욱 촉진되고 있습니다. 이러한 변화로 인해 골판지는 운송 매체일 뿐만 아니라 마케팅 매체로서의 역할도 확고히 자리 잡고 있습니다.
재사용형 플라스틱·RPC 도입이 일회용 제품 수요에 과제를 제기
소매업체들은 신선식품 및 육류용 반환 가능한 플라스틱 용기(RPC)의 풀을 확대되고 있습니다. 이는 매장 차원의 상품 손실(슈링크)을 줄이고 인건비를 절감할 수 있기 때문입니다. 프랑스, 독일, 한국에서는 일회용 골판지 상자보다 내구성이 뛰어난 목재 상자를 우선적으로 사용하는 재사용 할당 제도나 보증금 제도가 도입되어 있습니다. 자동 세척 네트워크에서는 재사용 횟수가 25회를 넘으면 RPC의 1회당 비용이 0.25달러 미만으로 떨어지며, 예측 가능한 신선식품 공급망에서 일회용 용기보다 비용 면에서 우위를 점하고 있습니다. 골판지 제조업체들은 높은 차단 성능의 내습성 코팅이나 무단 개봉 방지 잠금 탭을 사용하여 시장 점유율을 지키고 있지만, 회전율이 높은 유통 채널에서는 이익률 압박에 직면해 있습니다.
부문별 분석
2025년에는 성숙한 회수 네트워크와 유리한 EPR(생산자 책임 회수) 요금 체계에 힘입어 재생 등급이 골판지 포장 시장 점유율의 55.05%를 차지했습니다. 브랜드 소유자가 소비 후 재생 재료(PCC)의 함유율 기준을 높임에 따라, 이 부문은 연평균 성장률(CAGR) 4.56%를 나타낼 것으로 예측됩니다. 버진 크라프트 라이너는 견고한 수출용 상자에서 여전히 중요성을 유지하고 있지만, 그 수량 점유율은 계속 하락하고 있습니다. 밀짚, 벼 껍질, 토마토 줄기를 원료로 한 펄프가 상업적 시범 단계에 접어들었습니다. 실험실 테스트 결과, 기존 재생 펄프에 비해 인장 강도가 최대 25% 향상되는 것으로 나타났습니다. 원료의 수분 함량과 물류 비용을 관리하기 위해서는 지역 분산형 펄프 제조 설비에 대한 투자가 필수적입니다. 규모 확대가 성공하면, 폐지(OCC)의 가격 변동을 완화하고, 섬유 조달처를 다각화하며, 공급망의 회복탄력성을 높이는 데 기여할 것입니다.
농업 폐기물 펄프는 산림 벌채 과정을 생략할 수 있기 때문에 원목 섬유와 비교해 탄소 강도를 20-25% 줄이는 등 환경적 이점도 제공합니다. 이탈리아와 인도의 선행 도입 기업들은 골판지 제조기의 설정을 변경하지 않고도 농업 폐기물을 15-20%의 혼합 비율로 사용하고 있습니다. 식품 접촉 적합성 인증 체계는 아직 초기 단계이지만, 각 제조업체들은 2027년까지 규제의 조화가 진전될 것으로 전망하고 있습니다. 이러한 혁신은 골판지 포장 시장이 ‘원목 소재 대 재활용 소재’라는 이분법적 틀에서 벗어나, 보다 광범위한 다중 섬유 포트폴리오로 전환되어 지역별 자원 제약에 대한 적응력을 강화할 것임을 시사합니다.
2025년에는 기존 레귤러 슬롯 컨테이너(RSC)가 32.05%의 점유율을 차지했으나, 개봉 경험을 향상시키는 신속한 조립 설계를 추구하는 전자상거래 브랜드 소유주들 수요에 힘입어 폴더형 컨테이너는 2031년까지 연평균 성장률(CAGR) 5.48%로 증가할 것으로 예측됩니다. 자동 조립 장비는 폴더형 상자를 분당 35개 속도로 처리할 수 있으며, 수작업 RSC 라인보다 40% 더 빠르기 때문에 풀필먼트 센터의 노동력을 대폭 절감합니다. 골판지 포장 시장 규모 측면에서 볼 때, 이러한 변화는 2026년부터 2031년 사이에 89억 달러의 매출 증가로 이어질 것으로 예측됩니다.
슬롯이 있는 상자는 산업용 예비 부품 유통 등 부피 효율과 팔레타이징이 최우선으로 고려되는 부문에서 여전히 비용 면에서의 우위를 유지하고 있습니다. 텔레스코픽 방식과 경질 세트 방식의 상자는 고급 전자제품 등, 시각적 아름다움이나 파손 방지가 재료비보다 더 중요시되는 프리미엄 틈새 시장을 차지하고 있습니다. 디지털 인쇄가 가능한 폴더 구조에는 옴니채널 물류 흐름에 맞추어 티어 스트립과 재사용형 씰이 점점 더 많이 적용되고 있습니다. 구조의 진화는 성능 기준, 자동화 능력, 소비자 참여가 골판지 포장 시장의 사양 동향에 어떻게 시너지 효과를 발휘하고 있는지를 보여줍니다.
지역별 분석
2025년, 아시아태평양은 전 세계 골판지 포장 시장 매출의 39.85%를 차지하며, 제조 통합과 비용 효율적인 섬유 조달을 지속적으로 활용했습니다. 나인 드래곤스 페이퍼(Nine Dragons Paper)는 연간 생산 능력을 2,537만 톤으로 확대하여 이 지역공급 측면에서의 우위를 뒷받침하고 있습니다. 중국의 경기 부양책은 국내 소비를 활성화하고 있는 반면, 베트남과 말레이시아의 수출 지향형 공장은 현재 ‘일대일로’ 무역 회랑에 대응하고 있습니다. 폐지 수입 할당량에 대한 투자 또한 현지 농업 폐기물을 활용한 펄프 제조 시범 사업을 촉진하고 있어, 사용 후 골판지(OCC)에 대한 의존도를 낮추고 있습니다.
남미는 가장 빠르게 성장하는 무역 회랑으로, 2031년 연평균 성장률(CAGR)은 7.05%로 예측됩니다. 거시경제의 역풍에도 불구하고 브라질의 골판지 원지 출하량은 증가했습니다. 이는 생산자들이 수출 시장을 위해 공장의 생산 체제를 재편했기 때문입니다. 클라빈(Klabin)사의 파라나 신규 공장은 미래 생산 능력을 위한 선제적 투자의 좋은 사례이며, 한편 칠레와 콜롬비아의 가공업체들은 전자상거래용 상자 형태에 대응하기 위해 접착기 자동화에 투자하고 있습니다. 풍부한 사탕수수 바가스와 유칼립투스 조림지에 힘입은 섬유 자급자족을 바탕으로, 이 지역은 미래의 농업 폐기물 공급 허브로서의 입지를 확고히 하고 있습니다.
북미와 유럽에서는 규제 준수 및 고부가가치 혁신을 기반으로 한 한 자릿수 중반대의 꾸준한 성장이 나타나고 있습니다. 2025년에 발효된 EU의 재활용 의무화로 인해 이미 운송용 플라스틱 포장의 6%가 골판지로 전환되었습니다. 인터내셔널 페이퍼(International Paper)가 DS 스미스(DS Smith)를 72억 달러에 인수한 것은 양대륙에 걸친 해당 기업의 지속 가능한 포장 사업 기반을 확대하는 것이며, 2027년까지 6억-7억 달러의 시너지 효과가 기대되고 있습니다. 유럽의 제지 공장에서는 에너지 절약을 최우선으로 한 설비 현대화가 진행되고 있으며, 스토라 엔소(Stora Enso)의 오울 공장에서는 기존 제지기와 비교해 온실가스 배출 원단위를 20% 감축했습니다. 미국에서는 디지털 인쇄기의 보급률이 골판지 인쇄 설비 총 용량의 18%를 넘어섰으며, 소비재 부문에서 대량 맞춤화가 가속화되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the corrugated board packaging market size in 2026 is estimated at USD 205.74 billion, growing from 2025 value of USD 198.34 billion with 2031 projections showing USD 247.1 billion, growing at 3.73% CAGR over 2026-2031.
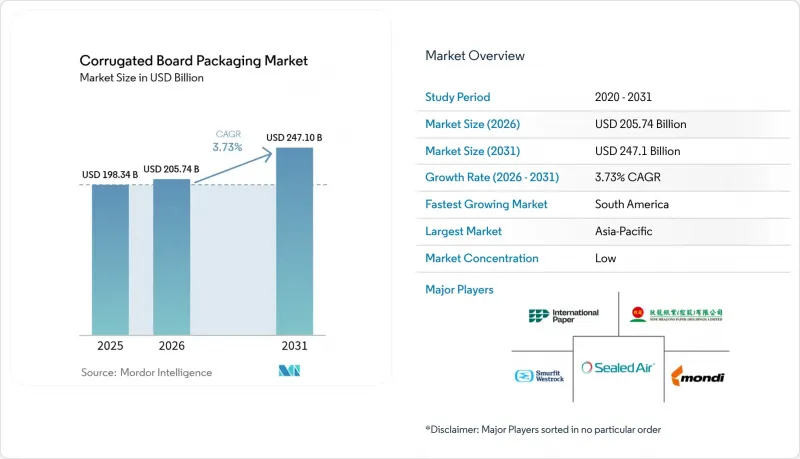
This report is Segmented by Material Type (Virgin Containerboard, and Recycled Containerboard), Box Style (Slotted Boxes, Telescope Boxes, and More), End-User Industry (Food, Beverages, Personal and Household Care, and More), Board Type (Single Wall, Double Wall, and More), Printing Technology (Flexography, Digital, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Corrugated Board Packaging Market Trends and Insights
Eco-friendly material mandates drive fiber substitution
New recyclability rules are tilting packaging material choices toward fiber. The EU requirement that all packaging be recyclable by 2030, alongside minimum recycled-content quotas for plastics, has made corrugated the low-risk compliance option. Five U.S. states impose fee scales that reward recyclable substrates, creating cost advantages of up to 15% versus plastic formats. Brands are accelerating specification changes because plastic recycling infrastructure lag times exceed the 2030 deadline. Corrugated's 71-76% recovery rate simplifies audit trails, supports corporate ESG pledges, and limits penalty exposure. Mill operators report order lead-times for fiber-based SKUs shortening by two weeks as converters re-tool lines to meet retailer scorecard requirements.
E-commerce parcel explosion reshapes packaging specifications
Global e-commerce shipping volumes grew from 220 billion parcels in 2024 to a projected 340 billion by 2029, elevating functional priorities such as drop-test durability and dimensional-weight efficiency. Double-wall and micro-flute boards now constitute over one-quarter of parcels shipped via major integrators. Equipment suppliers respond with on-demand boxmaking systems that trim labor by 40% while reducing void-fill needs, thereby cutting per-order materials cost by 15%. Subscription-commerce operators are specifying printable interiors for brand storytelling, which further boosts the loading of digitally printed graphics inside the shipping container. These shifts cement corrugated's role as both a transport medium and a marketing surface.
Reusable plastics and RPCs adoption challenges single-use demand
Retailers expand returnable-plastic-container (RPC) pools for produce and meat because they cut shrinkage and reduce labor at the store level. France, Germany, and South Korea have introduced reuse quotas or deposit schemes that favor durable crates over single-use corrugated. Automated wash-back networks lower per-trip RPC cost below USD 0.25 when cycle counts exceed 25, undercutting single-use units for predictable fresh-food supply chains. Corrugated converts defend share using high-barrier moisture-resistant coatings and tamper-evident locking tabs, but face margin squeeze in high-turnover channels.
Other drivers and restraints analyzed in the detailed report include:
- Advances in digital and flexo hybrid presses enable mass customization
- AI-driven box-design optimisation reduces material consumption
- Volatile OCC and energy prices compress manufacturing margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Recycled grades commanded 55.05% of the corrugated board packaging market share in 2025, buoyed by mature collection networks and favorable EPR fee structures. The segment is forecast to grow at 4.56% CAGR as brand owners raise post-consumer-content thresholds. Virgin Kraft liner retains relevance for heavy-duty export cartons, but its volume share continues to erode. Wheat-straw, rice-husk, and tomato-stem pulps are entering commercial pilots; laboratory work shows tensile strength gains of up to 25% over conventional recycled pulp. Investment in regional decentralized pulping units is crucial to control raw-material moisture and logistics costs. Successful scale-up would temper OCC price cycles and diversify fiber sourcing, strengthening supply-chain resilience.
Agricultural-waste pulps also deliver environmental gains, trimming carbon intensity by 20-25% relative to virgin wood fiber because they bypass forest-harvesting steps. Early adopters in Italy and India are integrating agri-waste at 15-20% blend ratios without modifying corrugator settings. Though certification frameworks for food-contact compliance remain nascent, producers expect regulatory alignment by 2027. These innovations signal that the corrugated board packaging market will shift from a binary virgin-versus-recycled narrative to a broader multi-fiber portfolio, reinforcing its adaptability to regional resource constraints.
Traditional regular slotted containers (RSCs) held a 32.05% share in 2025, but folder-type formats are projected to increase at a 5.48% CAGR through 2031, propelled by e-commerce brand owners seeking quick-assembly designs that enhance the unboxing experience. Automated erecting equipment processes folder styles at 35 boxes min-1, 40% faster than manual RSC lines, saving fulfillment centers significant labor. In the corrugated board packaging market size context, this shift translates into incremental revenue of USD 8.9 billion between 2026 and 2031.
Slotted boxes retain cost advantages where cube efficiency and palletization are paramount, such as industrial spare parts distribution. Telescope and rigid-set boxes occupy premium niches, including luxury electronics, where visual aesthetics and crush prevention outweigh material cost. Digital print-ready folder constructions increasingly integrate tear-strips and returnable seals, aligning with omnichannel logistics flows. The evolving construction landscape illustrates how performance criteria, automation capability, and consumer engagement jointly influence specification trends within the corrugated board packaging market.
Complete Report Scope:
- By Material Type
- Virgin Containerboard
- Recycled Containerboard
- By Box Style / Construction
- Slotted Boxes
- Telescope Boxes
- Rigid Boxes
- Folder Boxes
- By End-User Industry
- Food
- Processed Foods
- Fresh Food and Produce
- Beverages
- Personal and Household Care
- E-commerce and Fulfilment
- Healthcare and Pharmaceuticals
- Electrical and Electronics
- Industrial
- Other End-user Industry
- Food
- By Board Type
- Single Wall
- Double Wall
- Triple Wall
- Micro-flute
- By Printing Technology
- Flexography
- Digital
- Lithography
- Screen
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Singapore
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific accounted for 39.85% of global corrugated board packaging market revenue in 2025 and continues to leverage manufacturing integration and cost-effective fiber sourcing. Nine Dragons Paper expanded annual capacity to 25.37 million tonnes, underpinning the region's supply dominance. China's stimulus measures stimulate domestic consumption, yet export-oriented plants in Vietnam and Malaysia now serve Belt-and-Road trade corridors. Investment in waste-paper-import quotas also encourages local agri-waste pulping pilots, mitigating OCC dependency.
South America represents the fastest-growing corridor, with a 7.05% CAGR projected to 2031. Brazil's containerboard shipments increased despite macro headwinds as producers realigned mills for export markets. Klabin's new Parana facility exemplifies forward-capacity bets, while Chilean and Colombian converters invest in folder-gluer automation to meet e-commerce box styles. Fiber self-sufficiency, anchored in abundant sugar-cane bagasse and eucalyptus plantations, positions the region as a future agri-waste supply hub.
North America and Europe exhibit steady mid-single-digit growth anchored in regulatory compliance and value-added innovation. The EU recyclability mandate that took effect in 2025 has already shifted 6% of plastic transit-packaging volume into corrugated. International Paper's USD 7.2 billion buyout of DS Smith extends its sustainable-packaging footprint across both continents and is expected to unlock USD 600-700 million in synergy by 2027. European mill upgrades prioritize energy conservation, with Stora Enso's Oulu line claiming 20% lower greenhouse-gas intensity than legacy paper machines. In the United States, digital press penetration exceeds 18% of installed corrugated print capacity, accelerating mass customization in consumer packaged goods.
- International Paper Company
- Smurfit WestRock
- Mondi Group
- Nine Dragons Paper (Holdings) Limited
- Georgia-Pacific LLC
- Oji Holdings Corporation
- Stora Enso Oyj
- Sealed Air Corporation
- Pratt Industries
- Rengo Co., Ltd.
- Packaging Corporation of America
- Lee & Man Paper Manufacturing
- Klabin S.A.
- Cascades Inc.
- SCG Packaging
- Saica Group
- Orora Limited
- Visy Industries
- Grupo Gondi
- Astron Paper & Board Mill
- APP (Sinar Mas)
- Napco National
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Eco-friendly material mandates
- 4.2.2 E-commerce parcel explosion
- 4.2.3 Advances in digital and flexo hybrid presses
- 4.2.4 Light-weight containerboard economics
- 4.2.5 AI-driven box-design optimisation
- 4.2.6 Agricultural-waste fibre pulping
- 4.3 Market Restraints
- 4.3.1 Reusable plastics and RPCs adoption
- 4.3.2 Volatile OCC and energy prices
- 4.3.3 Corrugator electricity-intensity caps
- 4.3.4 Industrial-water withdrawal limits at mills
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Material Type
- 5.1.1 Virgin Containerboard
- 5.1.2 Recycled Containerboard
- 5.2 By Box Style / Construction
- 5.2.1 Slotted Boxes
- 5.2.2 Telescope Boxes
- 5.2.3 Rigid Boxes
- 5.2.4 Folder Boxes
- 5.3 By End-User Industry
- 5.3.1 Food
- 5.3.1.1 Processed Foods
- 5.3.1.2 Fresh Food and Produce
- 5.3.2 Beverages
- 5.3.3 Personal and Household Care
- 5.3.4 E-commerce and Fulfilment
- 5.3.5 Healthcare and Pharmaceuticals
- 5.3.6 Electrical and Electronics
- 5.3.7 Industrial
- 5.3.8 Other End-user Industry
- 5.3.1 Food
- 5.4 By Board Type
- 5.4.1 Single Wall
- 5.4.2 Double Wall
- 5.4.3 Triple Wall
- 5.4.4 Micro-flute
- 5.5 By Printing Technology
- 5.5.1 Flexography
- 5.5.2 Digital
- 5.5.3 Lithography
- 5.5.4 Screen
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Netherlands
- 5.6.2.7 Russia
- 5.6.2.8 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Singapore
- 5.6.3.7 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 Middle East
- 5.6.4.1.1 Saudi Arabia
- 5.6.4.1.2 United Arab Emirates
- 5.6.4.1.3 Turkey
- 5.6.4.1.4 Rest of Middle East
- 5.6.4.2 Africa
- 5.6.4.2.1 South Africa
- 5.6.4.2.2 Nigeria
- 5.6.4.2.3 Egypt
- 5.6.4.2.4 Rest of Africa
- 5.6.4.1 Middle East
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 International Paper Company
- 6.4.2 Smurfit WestRock
- 6.4.3 Mondi Group
- 6.4.4 Nine Dragons Paper (Holdings) Limited
- 6.4.5 Georgia-Pacific LLC
- 6.4.6 Oji Holdings Corporation
- 6.4.7 Stora Enso Oyj
- 6.4.8 Sealed Air Corporation
- 6.4.9 Pratt Industries
- 6.4.10 Rengo Co., Ltd.
- 6.4.11 Packaging Corporation of America
- 6.4.12 Lee & Man Paper Manufacturing
- 6.4.13 Klabin S.A.
- 6.4.14 Cascades Inc.
- 6.4.15 SCG Packaging
- 6.4.16 Saica Group
- 6.4.17 Orora Limited
- 6.4.18 Visy Industries
- 6.4.19 Grupo Gondi
- 6.4.20 Astron Paper & Board Mill
- 6.4.21 APP (Sinar Mas)
- 6.4.22 Napco National
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


