

|
시장보고서
상품코드
2124555
유럽, 중동 및 아프리카(EMEA)의 골판지 포장 : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)EMEA Corrugated Board Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
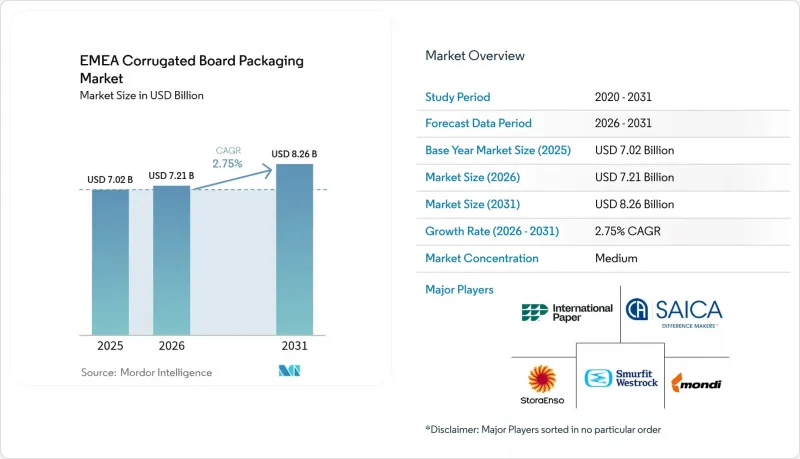
에 의하면, 2026년 유럽, 중동 및 아프리카(EMEA)의 골판지 포장 시장 규모는 72억 1,000만 달러로 추정되고 2025년 70억 2,000만 달러에서 확대해, 2031년에는 82억 6,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 2.75%로 성장할 것으로 전망됩니다.
본 보고서는 최종 사용자 산업별(식품, 음료, 전자상거래, 전기 및 전자기기 등), 플루트 유형별(A 플루트, B 플루트, C 플루트 등), 골판지 유형별(단면, 단층 등),인쇄 기술별(플렉소 인쇄, 디지털 인쇄 등), 지역별(유럽, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
유럽, 중동 및 아프리카(EMEA)의 골판지 포장 시장 동향 및 인사이트
전자상거래 소포 처리량의 폭발적인 증가
2024년 EU 역내 국경 간 거래가 23% 증가함에 따라, 온라인 소매는 골판지에 대한 새로운 수요원을 창출했습니다. 소포 형태에 있어서는 보호 성능이 뛰어난 디자인, 브랜딩을 위한 추가 공간, 제품에 딱 맞는 형태가 요구되고 있으며, 이 모든 요소가 단가 상승으로 이어지고 있습니다. 도시 지역의 풀필먼트 허브에서는 교외의 대규모 복합 시설보다 기동성이 뛰어난 시트 공장이 선호되는 추세이며, 이에 따라 가공업체들은 골판지 생산 라인을 신속하게 전환할 수 있는 모듈식 골판지 제조기 도입을 서두르고 있습니다. Zalando와 같은 브랜드는 2024년에 맞춤형 크기의 수성 코팅 상자로 전환한 결과, 재료비를 15% 절감하고 인쇄 미관도 향상시켰습니다. 당일 배송의 꾸준한 성장은 EMEA 지역의 골판지 포장 시장을 더욱 가속화하고 있으며, 소포의 유통 속도를 현지 공장의 확실한 수주 잔고로 연결하고 있습니다.
EU의 PPWR(포장 폐기물 규정)에 힘입은 재활용 가능 포장 수요
2024년 규정은 2030년까지 골판지 제품의 재활용률을 90%로 의무화하고, 평균 재생 섬유 함유율 기준을 85%로 상향 조정하고 있습니다. 골판지는 이미 88%를 달성하여 플라스틱 기판에 비해 규제 준수에 앞서 있습니다. 첨단 탈색 시스템을 갖춘 제조업체는 백색도가 높은 재생 라이너에 대해 가격 프리미엄을 확보하고 있습니다. 또한, 이 정책으로 인해 유럽 브랜드의 중동 및 아프리카 자회사들도 일관된 지속가능성 주장을 유지하기 위해 섬유 소재 채택을 촉진받고 있습니다. 그 결과, EMEA 지역의 골판지 포장 시장은 보조금에 의한 지원이 아닌 규제에 의한 견인력을 배경으로 하고 있어, 신규 투자의 위험 프로파일이 억제되고 있습니다.
OCC 및 크라프트 라이너의 가격 변동
2024년, OCC 가격은 35%나 변동하여 연간 계약을 체결한 가공업체의 매출 총이익률을 압박했습니다. 헤지 수단의 유동성이 제한적이기 때문에 중견 골판지 공장은 전가 조항을 재협상할 수밖에 없으며, 그렇지 않으면 지급 능력 위기에 직면할 우려가 있습니다. 크라프트 라이너도 펄프 및 에너지 비용과 연동되어 있어 원자재 예산에 불확실성을 초래하고 있습니다. 이러한 변동으로 인해 대규모 통합형 기업들은 광범위한 섬유 원료 조달처와 환율 헤지를 활용하여 사업을 확장하는 반면, 소규모 독립 기업들은 시장에서 철수하거나 전문화로 방향을 전환하는 등 업계 재편이 가속화되고 있습니다. 이러한 가격 변동으로 인해 EMEA 지역의 골판지 포장 시장 예측 연평균 성장률(CAGR)은 0.5포인트 하향 조정되었습니다.
부문별 분석
식품 부문은 2025년 EMEA 골판지 포장 시장에서 34.92%라는 압도적인 점유율을 차지했으며, 그 기반은 농산물 수출, 상온 보관 식품 및 냉장 즉석식사에 있습니다. 생산자들은 골판지가 압축 강도를 저하시키지 않으면서 결로를 흡수하는 능력을 높이 평가하고 있으며, 이를 통해 엄격한 위생 기준을 충족하는 동시에 고해상도 그래픽을 통해 브랜드 인지도를 높일 수 있게 되었습니다. 수성 코팅이 적용된 경량 크레이트가 델리 및 베이커리 매장에 보급되면서 PET 재질의 클램쉘 용기를 대체하고 있습니다. 전자상거래 채널은 소비자에게 직접 배송되는 식료품 박스, 패션 상품의 반품 물류, 그리고 전자제품 배송에 힘입어 2031년까지 4.12%라는 가장 높은 연평균 성장률(CAGR)을 보일 전망입니다. 이 분야의 포장 수요는 퀵셋 잠금장치, 립 탭, 반품용 테이프가 일체화된 제품으로 쏠리고 있으며, 이러한 제품들은 주문 처리 인건비를 절감합니다. 식품 브랜드가 온라인 마켓플레이스에서 여러 상품을 동시에 판매할 때, 신선 식품을 보호하면서도 배송지에서 매력적으로 보이게 하는 이중 목적을 달성하는 SKU가 필요하며, 이는 시너지 효과를 창출합니다. 이로 인해 EMEA 지역의 골판지 포장 시장 점유율 확대가 촉진되고 있습니다.
안정적인 음료 하위 부문에서는 유리나 알루미늄으로 만든 멀티팩을 보호하기 위한 보강된 칸막이가 요구되고 있으며, 기업의 탄소 감축 공약을 충족하기 위해 재고는 사용 후 재활용 라이너로 전환되고 있습니다. 퍼스널케어 및 화장품 라인에서는 구조적 강도와 오프셋 인쇄에 필적하는 인쇄 품질을 겸비한 마이크로 플루트 상자가 선택되어, 개봉 시의 연출 효과를 높이고 있습니다. 산업용 부품 분야에서는 합판을 대체하는 ‘접이식’ 다이컷이 채택되어 경량화와 통관 절차 간소화가 도모되고 있습니다. 자동차 부품의 전동화에 따라 배터리 모듈용 정전기 방지 코팅이 요구되고 있으며, 재료를 대폭 늘리지 않고도 프리미엄 부가가치를 창출하고 있습니다.
C-플루트는 그 다재다능한 완충성과 적층 성능 덕분에 2025년에도 31.95%의 점유율을 유지하며, 케이스 레디 식품 및 내구재의 기본 선택지로 자리 잡았습니다. 그러나 마이크로 플루트의 변형 제품(F 및 N)은 뛰어난 인쇄 정렬 정확도와 운송 비용을 절감하는 얇은 두께 구조라는 강점을 바탕으로 연평균 3.82%의 성장률을 기록하고 있습니다. 전문 가공업체들은 마이크로 플루트와 고백색도 라이너를 조합하여 고급 초콜릿, 개인용 전자제품, POS용 트레이를 타겟으로 하고 있습니다. A 플루트는 냉장 창고에서 수직 적재가 필요한 멜론이나 뿌리채소용 견고한 농업용 컨테이너로 여전히 널리 사용되고 있습니다. B 플루트는 진열대용 디스플레이에 정밀한 다이컷이나 스코어링이 필요한 경우에 적합합니다. E 플루트는 판지와 골판지 두 분야에 걸쳐, 촉감이 단단한 것을 요구하는 소형 가전제품이나 특선 차 분야에서 활용되고 있습니다. 이러한 플루트 형태의 다양화로 인해 SKU가 다양해지고, 골판지 제조 기계에 대한 설비 투자가 분산됨에 따라 EMEA 지역의 골판지 포장 시장에서 혁신의 기세가 유지되고 있습니다.
재료 과학의 발전으로 E/B 이중벽 구조와 같은 하이브리드 플루트 조합이 가능해졌습니다. 이를 통해 인쇄 면과 내압성을 동시에 확보할 수 있게 되었으며, 컨버터는 판지 공급업체를 변경하지 않고도 전자상거래용 의류와 산업용 예비 부품 모두에 대응할 수 있는 모듈식 설정을 구현할 수 있습니다. 이러한 접근 방식은 특히 제품 중량 데이터베이스를 기반으로 플루트 조합을 추천하는 AI 패턴 라이브러리와 결합될 때 고객 유지율 향상으로 이어집니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, EMEA corrugated board packaging market size in 2026 is estimated at USD 7.21 billion, growing from 2025 value of USD 7.02 billion with 2031 projections showing USD 8.26 billion, growing at 2.75% CAGR over 2026-2031.
This report is Segmented by End-User Industry (Food, Beverages, E-Commerce, Electrical and Electronics, and More), Flute Type (A-Flute, B-Flute, C-Flute, and More), Board Type (Single Face, Single Wall, and More), Printing Technology (Flexography, Digital Printing, and More), and Geography (Europe, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
EMEA Corrugated Board Packaging Market Trends and Insights
Exploding e-commerce parcel volumes
Online retail added new corrugated demand streams as cross-border transactions in the EU climbed 23% in 2024. Parcel formats favor protective designs, extra branding space, and fit-to-product geometry, all of which command premium unit prices. Urban fulfillment hubs now prefer agile sheet plants over large suburban complexes, pushing converters to deploy modular corrugators with rapid changeovers. Brands such as Zalando demonstrated 15% material savings and improved print aesthetics after switching to custom-sized water-based coated boxes in 2024. Steady growth in same-day delivery further accelerates the EMEA corrugated board packaging market, translating parcel velocity into reliable order backlogs for local plants.
EU PPWR-driven demand for recyclable packaging
The 2024 regulation mandates 90% recycling rates for corrugated formats by 2030 and elevates average recycled fiber content benchmarks to 85%. Corrugated already delivers 88%, giving it a compliance head-start over plastic substrates. Producers with advanced de-inking systems are locking in price premiums for high-whiteness recycled liner. The policy also nudges Middle Eastern and African subsidiaries of European brands toward fiber adoption to maintain uniform sustainability claims. As a result, the EMEA corrugated board packaging market embeds regulatory pull rather than subsidy push, curbing risk profiles for new investments.
OCC and kraftliner price volatility
OCC prices swung 35% in 2024, compressing gross margins for converters locked into annual contracts. Hedging mechanisms have limited liquidity, forcing mid-tier box plants to renegotiate pass-through clauses or risk solvency. Kraftliner also tracks pulp and energy costs, injecting unpredictability into input budgets. The turbulence intensifies consolidation as scaled integrators leverage broader fiber baskets and currency hedges, while smaller independents exit or specialize. Such swings subtract 0.5 percentage points from the projected CAGR for the EMEA corrugated board packaging market.
Other drivers and restraints analyzed in the detailed report include:
- Fresh produce cold-chain shift to fiber-based crates
- AI-enabled right-size packaging adoption
- Energy-price shock hitting corrugator OPEX
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The food segment generated a dominant 34.92% share of the EMEA corrugated board packaging market in 2025, anchored in agricultural exports, ambient grocery, and chilled ready-meals. Producers value corrugated's capacity to absorb condensation without losing compressive strength, fulfilling stringent hygiene standards while supporting brand visibility through high-resolution graphics. Lightweight crates with water-based coatings now penetrate deli and bakery aisles, displacing PET clamshells. The e-commerce channel exhibits the fastest 4.12% CAGR to 2031, driven by direct-to-consumer grocery boxes, fashion returns logistics, and electronics deliveries. Packaging needs here skew toward quick-set locks, rip-tabs, and integrated returns tape that shrink fulfillment labor costs. Synergies arise when food brands cross-list on online marketplaces, requiring dual-purpose SKUs that protect perishables and present attractively on the doorstep, thereby reinforcing share gains for the EMEA corrugated board packaging market.
A stable beverage sub-segment demands reinforced section dividers to shield glass and aluminum multipacks, with inventory switching toward post-consumer recycled liner to meet corporate carbon pledges. Personal care and cosmetics lines select microflute boxes that blend structural integrity with near-offset print quality, uplifting unboxing theatrics. Industrial parts now adopt fold-to-fit die-cuts that replace plywood, lowering weight and easing customs clearance. Electrification in automotive components invites antistatic coatings for battery modules, adding premium value layers without heavy material additions.
C-Flute maintained 31.95% share in 2025 for its all-round cushioning and stacking competencies, making it a default choice for case-ready foods and durable goods. However, microflute variants (F and N) are growing 3.82% annually on the strength of superior print registration and slimmer wall thickness that cuts freight costs. Specialty converters pair microflute with high-white liners, targeting luxury chocolates, personal electronics, and point-of-sale trays. A-Flute persists in heavy-duty agriculture bins for melons and root vegetables that face vertical stacking in cold stores. B-Flute wins when precise die-cut scoring is needed for shelf-ready displays. E-Flute straddles cartonboard and corrugated territories, servicing small appliances and specialty teas that crave tactile stiffness. This diversification of flute profiles diversifies SKUs and spreads capex across corrugators, sustaining innovation momentum in the EMEA corrugated board packaging market.
Material science developments allow hybrid flute combinations where an E/B double wall mates print surface with crush resistance, giving converters modular setups to serve both e-commerce apparel and industrial spares without switching board suppliers. The approach elevates customer retention, especially when paired with AI pattern libraries that recommend flute mixes from product weight databases.
Complete Report Scope:
- By End-User Industry
- Food
- Processed Foods
- Fresh Food and Produce
- Beverages
- E-commerce
- Electrical and Electronics
- Personal Care and Cosmetics
- Other End-User Industries
- Food
- By Flute Type
- A-Flute
- B-Flute
- C-Flute
- E-Flute
- F/N Microflute
- Other Flute Types
- By Board Type
- Single Face
- Single Wall
- Double Wall
- Triple Wall
- By Printing Technology
- Flexography
- Digital Printing
- Litho-lamination
- Screen Printing
- Other Printing Technologies
- BY Geography
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Europe
List of Companies Covered in this Report:
- Smurfit WestRock
- Mondi plc
- International Paper Company
- Saica S.A.
- Stora Enso Oyj
- Svenska Cellulosa Aktiebolaget (SCA)
- Prinzhorn Holding GmbH
- VPK Group NV
- Palm Gruppe GmbH & Co KG
- Dunapack Packaging (Prinzhorn)
- Mayr-Melnhof Karton AG
- Rengo Co. Ltd.
- Nine Dragons Paper (Holdings) Ltd.
- Packaging Corporation of America
- Georgia-Pacific LLC
- Amcor plc
- Pratt Industries, Inc.
- Cascades Inc.
- Arabian Packaging LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Exploding e-commerce parcel volumes
- 4.2.2 EU PPWR-driven demand for recyclable packaging
- 4.2.3 Fresh produce cold-chain shift to fiber-based crates
- 4.2.4 AI-enabled right-size packaging adoption
- 4.2.5 Water-based barrier coatings replacing plastic trays
- 4.2.6 EU CBAM incentives for local recycled liner
- 4.3 Market Restraints
- 4.3.1 OCC and kraftliner price volatility
- 4.3.2 Substitution by reusable/flexible packaging
- 4.3.3 Energy-price shock hitting corrugator OPEX
- 4.3.4 War-related mill outages in Eastern Europe
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By End-User Industry
- 5.1.1 Food
- 5.1.1.1 Processed Foods
- 5.1.1.2 Fresh Food and Produce
- 5.1.2 Beverages
- 5.1.3 E-commerce
- 5.1.4 Electrical and Electronics
- 5.1.5 Personal Care and Cosmetics
- 5.1.6 Other End-User Industries
- 5.1.1 Food
- 5.2 By Flute Type
- 5.2.1 A-Flute
- 5.2.2 B-Flute
- 5.2.3 C-Flute
- 5.2.4 E-Flute
- 5.2.5 F/N Microflute
- 5.2.6 Other Flute Types
- 5.3 By Board Type
- 5.3.1 Single Face
- 5.3.2 Single Wall
- 5.3.3 Double Wall
- 5.3.4 Triple Wall
- 5.4 By Printing Technology
- 5.4.1 Flexography
- 5.4.2 Digital Printing
- 5.4.3 Litho-lamination
- 5.4.4 Screen Printing
- 5.4.5 Other Printing Technologies
- 5.5 BY Geography
- 5.5.1 Europe
- 5.5.1.1 United Kingdom
- 5.5.1.2 Germany
- 5.5.1.3 France
- 5.5.1.4 Spain
- 5.5.1.5 Italy
- 5.5.1.6 Rest of Europe
- 5.5.2 Middle East
- 5.5.2.1 Saudi Arabia
- 5.5.2.2 United Arab Emirates
- 5.5.2.3 Turkey
- 5.5.2.4 Rest of Middle East
- 5.5.3 Africa
- 5.5.3.1 South Africa
- 5.5.3.2 Egypt
- 5.5.3.3 Nigeria
- 5.5.3.4 Rest of Africa
- 5.5.1 Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Smurfit WestRock
- 6.4.2 Mondi plc
- 6.4.3 International Paper Company
- 6.4.4 Saica S.A.
- 6.4.5 Stora Enso Oyj
- 6.4.6 Svenska Cellulosa Aktiebolaget (SCA)
- 6.4.7 Prinzhorn Holding GmbH
- 6.4.8 VPK Group NV
- 6.4.9 Palm Gruppe GmbH & Co KG
- 6.4.10 Dunapack Packaging (Prinzhorn)
- 6.4.11 Mayr-Melnhof Karton AG
- 6.4.12 Rengo Co. Ltd.
- 6.4.13 Nine Dragons Paper (Holdings) Ltd.
- 6.4.14 Packaging Corporation of America
- 6.4.15 Georgia-Pacific LLC
- 6.4.16 Amcor plc
- 6.4.17 Pratt Industries, Inc.
- 6.4.18 Cascades Inc.
- 6.4.19 Arabian Packaging LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


