

|
시장보고서
상품코드
2124471
영국의 골판지 포장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United Kingdom Corrugated Board Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
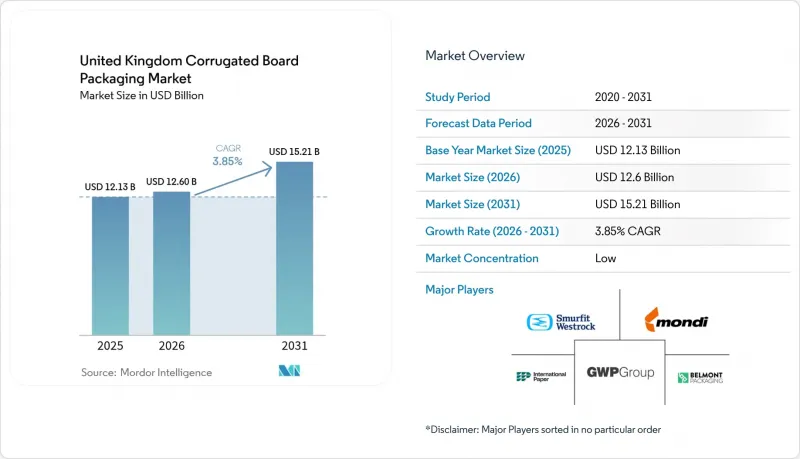
에 의하면, 2026년 영국의 골판지 포장 시장 규모는 126억 달러로 추정되고 2025년 121억 3,000만 달러에서 확대해, 2031년에는 152억 1,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 3.85%로 성장할 것으로 전망됩니다.
본 보고서는 최종 사용자 산업별(식품, 음료, 전자상거래, 전기 및 전자기기 등), 플루트 유형별(A 플루트, B 플루트, C 플루트, E 플루트 등), 보드 유형별(단면, 싱글 골판지 등),인쇄 기술별(플렉소 인쇄, 디지털 인쇄, 리소 라미네이션 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
영국의 골판지 포장 시장 동향 및 인사이트
전자상거래 주문 처리량의 급증
온라인 소매의 경우, 기존 판매 채널에 비해 소포 1개당 약 30% 더 많은 보호 포장재가 필요하기 때문에 소포 수 증가에 따라 골판지 수요가 높아지고 있습니다. 2024년, 영국의 전자상거래 매출은 15.8% 급증했으며, 의류에서 소형 전자기기에 이르기까지 광범위한 카테고리에 걸친 소비 행태의 변화가 정착되었습니다. 가공업체들은 강도를 저하시키지 않으면서 재료 사용량을 최대 25%까지 절감하는 AI 기반 ‘주문형 골판지 상자 제조 장비’를 도입하여, 부피 중량 요금을 억제하는 적정 크기의 배송 솔루션을 실현하고 있습니다. 전자상거래 스토어프론트에서 제조 실행 시스템으로의 직접적인 데이터 연동을 통해 재고 보유량을 줄이고 대응 시간을 단축할 수 있게 되었으며, 이는 프리미엄 개봉 경험을 추구하는 브랜드에게 결정적인 우위를 제공합니다. 이러한 흐름에 동참하는 전문 컨버터 기업들은 디지털 인쇄를 중시하는 경향을 보이며, 최소한의 설정 비용으로 가변 그래픽 및 이벤트 연계형 캠페인을 실현하고 있습니다.
소매 업계의 ‘진열 준비 완료’ 포장로의 전환
테스코(Tesco)나 ASDA와 같은 대형 식료품 체인점들은 상온 상품 매대 전체에서 ‘진열 준비 완료’ 포장의 도입을 확대하여, 매장 내 인건비를 최대 50% 절감하는 동시에 상품 보충 시 파손률을 대폭 낮췄습니다. 미싱선이나 쉽게 뜯을 수 있는 티어 스트립이 적용된 골판지 디자인은 운송 시의 내충격성과 신속한 진열이라는 상반된 요구를 모두 충족시키고 있습니다. 디스플레이의 형태, 케이스 수, 적재 시의 안정성을 조화시켜야 하기 때문에 브랜드, 소매업체, 컨버터 간의 협력이 더욱 강화되고 있습니다. 소규모의 지역 밀착형 컨버터는 신속한 시제품 제작과 지역 밀착형 서비스를 통해 고객의 신뢰를 쌓고 있는 반면, 전국 규모의 기업은 다이 커팅 가공의 규모의 경제와 대용량 플렉소 인쇄기에서 가치를 창출하고 있습니다. 성공한 참여자들에게 있어 성과는 프리미엄 구조적 특징을 통한 단위 매출 증대와 매장 진열 기준에 대한 높은 준수율입니다.
재생지 공급 상황의 재차 긴축
2024년, 종이 회수 증서(PRN) 가격은 톤당 180-200파운드로 지난 20년 동안 최고치를 경신하며, 회수량과 제지 공장으로 반입되는 양의 불균형이 드러났습니다. 혼합된 일반 폐기물에 포함된 불순물이 섬유의 품질을 저하시키고 있기 때문에 컨버터는 더 비싼 선별된 등급의 종이를 조달하거나 유럽 대륙공급업체로부터 재활용 종이를 수입할 수밖에 없는 상황입니다. 이에 반해, 통합형 제조업체는 수거 차량과 선별 시설을 인수해 원료를 확보하는 한편, 현물 시장에 대한 의존도를 낮춤으로써 대응하고 있습니다. 이러한 대응 능력을 갖추지 못한 중소규모의 독립 기업들은 간헐적인 가동 중단을 감수하거나 완제품 상자 가격을 인상할 수밖에 없어, 시장 점유율을 잃을 위험에 직면해 있습니다. 환율 변동도 비용 부담을 더욱 가중시키고 있으며, 유로화 표시 수입 가격이 영국 파운드 대비 상승하면 조달 시 헤지 작업이 복잡해집니다.
부문별 분석
2025년, 식품 용도는 영국의 골판지 포장 시장의 34.92%를 차지하며, 신선 식품, 상온 보관 식품, 음료의 전체 공급망에서 섬유 기반 운송용 포장에 대한 뿌리 깊은 의존도를 반영했습니다. 이 부문의 성장은 재활용이 어려운 플라스틱을 대체하는 추세, 특히 내습성 코팅이 적용된 신선 과일 트레이에 대한 수요 증가와 지속적으로 연계되어 있습니다. 슈퍼마켓이 쇼핑객에게 재활용 가능성을 강조함에 따라 소매 분야의 도입이 가속화되고 있으며, 배리어 가공 능력을 갖춘 가공업체에게는 안정적인 수주량이 예상됩니다. 전자상거래 시장은 규모는 작지만 연평균 성장률(CAGR) 5.16%로 확대될 것으로 예측됩니다. 이는 운송용 상자와 동등한 파열 강도가 필요하면서도, 최종 사용자의 개봉 경험을 중시하는 세련된 그래픽이 요구되는 ‘소비자 직배송(DTC)’ 방식의 배송에 힘입은 것입니다. 전자상거래 출하용 영국의 골판지 포장 시장 규모는 소포 수 증가에 따라 급격히 확대될 것으로 예상되며, 이는 디지털 인쇄기를 갖춘 공장에 수익성 높은 소량 생산 수요를 가져다줄 것입니다.
음료 업계용 포장 제조업체들은 멀티팩용 캐리어를 통해 견조한 성장세를 유지하고 있으며, 스포츠 행사나 공휴일 일정에 맞춘 프로모션 브랜딩에서 플렉소 인쇄의 고속성을 활용하고 있습니다. 전자기기 및 퍼스널케어 틈새 시장은 톤수 기준으로는 비교적 소규모이지만, 정전기 방지 라이너와 고급 인쇄를 통해 평방미터당 수익은 높은 임베디드니다. 이처럼 최종 용도의 다양화로 인해 개별 소비 카테고리의 주기적인 변동으로부터 전체 수요가 보호되고 있으며, 이는 대형 통합 기업들이 채택하고 있는 전략적 리스크 헤지 수단이 되고 있습니다.
C-플루트는 균형 잡힌 완충성과 우수한 인쇄 면이 높이 평가되어, 영국의 골판지 포장 시장에서 31.74%의 점유율을 차지하고 있습니다. 그러나 F/N 마이크로 플루트가 연평균 성장률(CAGR) 4.80%를 나타낼 것으로 예측되어 주목을 받고 있습니다. 극히 얇은 구조 덕분에 더욱 정교한 그래픽 표현이 가능할 뿐만 아니라, 부피당 무게를 줄일 수 있어 운송업체가 부피를 기준으로 요금을 청구하는 소포 배송 네트워크에서 이 특성이 높이 평가되고 있습니다. 의류 및 화장품 취급 배송업체들이 불필요한 공간을 제거하면서도 ‘인스타 감성’이 살아있는 프레젠테이션을 요구하는 가운데, 영국의 골판지 포장 시장에서 마이크로 플루트 제품이 차지하는 점유율은 확대될 전망입니다.
A-플루트 및 B-플루트 등급은 낙하 시험 성능이 부피 최적화 요구를 상회하는 중량물이나 파손되기 쉬운 SKU에 있어 여전히 필수적입니다. E-플루트는 디스플레이의 미관과 구조적 강도를 모두 갖춘 것으로, 외장이 상품 진열 패널 역할을 겸해야 하는 ‘진열대 진열용’ 형식에 널리 활용되고 있습니다. 플루트의 다양화가 진행됨에 따라 재고 계획은 복잡해지고 있으며, 가공업체들은 용지를 확정하기 전에 다양한 평량에서의 성능을 시뮬레이션하는 디지털 트윈 소프트웨어 도입을 추진하고 있습니다. 성공을 거두고 있는 기업들은 폭넓은 플루트 라인업과 신속한 전환을 양립시켜 가동 중단 시간과 폐기물을 최소화하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the United Kingdom corrugated board packaging market size in 2026 is estimated at USD 12.6 billion, growing from 2025 value of USD 12.13 billion with 2031 projections showing USD 15.21 billion, growing at 3.85% CAGR over 2026-2031.
This report is Segmented by End-User Industry (Food, Beverages, E-Commerce, Electrical and Electronics, and More), Flute Type (A-Flute, B-Flute, C-Flute, E-Flute, and More), Board Type (Single Face, Single Wall Board, and More), Printing Technology (Flexography, Digital Printing, Litho-Lamination, and More). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Corrugated Board Packaging Market Trends and Insights
E-commerce Fulfillment Volume Surge
Online retail requires about 30% more protective packaging per parcel than traditional channels, elevating corrugated demand as parcel counts climb. United Kingdom e-commerce sales leapt 15.8% in 2024, locking in behavioral shifts that spread across categories ranging from apparel to small electronics. Converters integrate AI-driven box-on-demand equipment that trims material use by up to 25% without sacrificing strength, enabling right-sized shipping solutions that control dimensional-weight charges. Direct data feeds from e-commerce storefronts into manufacturing execution systems cut inventory holdings and sharpen response times, a decisive advantage for brands targeting premium unboxing experiences. Specialized converters riding this wave often stress digital printing, enabling variable graphics and event-driven campaigns at minimal setup cost.
Retailer Shift to Shelf-Ready Packaging
Major grocery chains such as Tesco and ASDA broadened shelf-ready mandates across ambient aisles, reducing in-store labor by up to 50% and slashing damage rates during restocking. Corrugated designs featuring perforations and easy-open tear strips satisfy the mixed need for shipping resistance and rapid presentation. Collaboration among brands, retailers, and converters intensifies because display geometry, case counts, and stacking integrity must harmonize. Smaller regional converters build loyalty through fast prototyping and local service, whereas national players extract value from die-cutting scale and high-capacity flexo presses. The payoff for successful participants is higher unit revenue from premium structural features and higher end-of-aisle compliance.
Re-tightening Recycled Paper Availability
Paper Recovery Note (PRN) values broke two-decade highs at GBP 180-200 per tonne in 2024, exposing the imbalance between collection output and mill intake. Contamination in mixed municipal streams erodes fiber quality, forcing converters either to hunt costlier sorted grades or import recovered paper from continental suppliers. Integrated producers respond by acquiring collection fleets and sorting facilities, securing feedstock, and reducing spot-market exposure. Smaller independents, lacking such scope, endure episodic downtime or raise finished-box prices, risking share loss. Currency volatility adds another cost layer when euro-denominated imports rise against sterling, complicating procurement hedges.
Other drivers and restraints analyzed in the detailed report include:
- Substitution Away from Single-Use Plastics
- Cost-Optimized Lightweight Fluting Technology
- Energy-Price Volatility Pressuring Mill Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Food applications represented 34.92% of the United Kingdom corrugated board packaging market in 2025, reflecting entrenched dependence on fiber-based transit packaging across produce, ambient grocery, and beverage supply chains. The segment's growth remains linked to substitution away from hard-to-recycle plastics, especially for fresh fruit trays incorporating moisture-resistant coatings. Retail take-up accelerates as supermarkets showcase the recyclability narrative to shoppers, locking in volume for converters with barrier-treatment capacity. E-commerce, though smaller, is forecast to advance at a 5.16% CAGR, buoyed by direct-to-consumer shipping formats that often demand burst strength equal to transit boxes but refined graphics aimed at end-user unboxing. The United Kingdom corrugated board packaging market size for e-commerce shipments is projected to balloon alongside parcel counts, supplying profitable short-run work to plants outfitted with digital presses.
Packagers serving beverages maintain steady momentum through multi-pack carriers, exploiting flexo's high-speed capability for promotional branding aligned with sporting and holiday calendars. Electronics and personal-care niches, while comparatively modest in tonnage, deliver higher revenue per square meter due to anti-static liners and premium printing. End-use diversification thus cushions overall demand against cyclical swings in any single consumption category, a strategic hedge embraced by larger integrated players.
C-Flute holds a 31.74% slice of the United Kingdom corrugated board packaging market share, beloved for its balanced cushioning and print surface. Yet F/N Microflute is stealing the spotlight with a projected 4.80% CAGR; its ultra-thin profile allows finer graphics while shaving dimensional weight, an attribute highly prized in parcel networks where carriers bill by volume. The United Kingdom corrugated board packaging market size allocated to microflute designs is set to rise as apparel and cosmetic shippers demand Instagram-ready presentation without superfluous airspace.
A- and B-Flute grades remain essential for heavy or fragile SKUs where drop-test performance eclipses cube-optimization needs. E-Flute, positioned between display aesthetics and structural integrity, thrives in shelf-ready formats whose outer facing must double as a merchandising panel. Ongoing flute diversification complicates inventory planning, prompting converters to deploy digital twin software that simulates performance at varying grammages before committing paper. The winners balance wide flute arsenals with agile changeovers, minimizing downtime and scrap.
Complete Report Scope:
- By End-User Industry
- Food
- Processed Foods
- Fresh Food and Produce
- Beverages
- E-commerce
- Electrical and Electronics
- Personal Care and Cosmetics
- Other End-User Industries
- Food
- By Flute Type
- A-Flute
- B-Flute
- C-Flute
- E-Flute
- F/N Microflute
- Other Flute Types
- By Board Type
- Single Face
- Single Wall
- Double Wall
- Triple Wall
- By Printing Technology
- Flexography
- Digital Printing
- Litho-lamination
- Screen Printing
- Other Printing Technologies
List of Companies Covered in this Report:
- Smurfit WestRock
- International Paper Company
- Mondi plc
- GWP Group Ltd.
- The Box Factory Ltd.
- Belmont Packaging Ltd.
- The Corrugated Case Company Ltd.
- Nuttall Packaging
- Cardboard Box Company Ltd.
- Saica Group
- Rigid Containers Ltd.
- Board24 Ltd.
- Cepac Holdings Ltd.
- Boxes and Packaging (UK) Ltd.
- LC Packaging UK Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-commerce fulfilment volume surge
- 4.2.2 Retailer shift to shelf-ready packaging
- 4.2.3 Substitution away from single-use plastics
- 4.2.4 Cost-optimised lightweight fluting technology
- 4.2.5 AI-enabled box-on-demand systems
- 4.2.6 Carbon-footprint labelling mandates
- 4.3 Market Restraints
- 4.3.1 Re-tightening recycled paper availability
- 4.3.2 Energy-price volatility pressuring mill margins
- 4.3.3 Labour shortages in UK logistics
- 4.3.4 Import competition from Eastern Europe
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Investment Analysis
- 4.10 Overview of the Global Corrugated Board Packaging Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By End-User Industry
- 5.1.1 Food
- 5.1.1.1 Processed Foods
- 5.1.1.2 Fresh Food and Produce
- 5.1.2 Beverages
- 5.1.3 E-commerce
- 5.1.4 Electrical and Electronics
- 5.1.5 Personal Care and Cosmetics
- 5.1.6 Other End-User Industries
- 5.1.1 Food
- 5.2 By Flute Type
- 5.2.1 A-Flute
- 5.2.2 B-Flute
- 5.2.3 C-Flute
- 5.2.4 E-Flute
- 5.2.5 F/N Microflute
- 5.2.6 Other Flute Types
- 5.3 By Board Type
- 5.3.1 Single Face
- 5.3.2 Single Wall
- 5.3.3 Double Wall
- 5.3.4 Triple Wall
- 5.4 By Printing Technology
- 5.4.1 Flexography
- 5.4.2 Digital Printing
- 5.4.3 Litho-lamination
- 5.4.4 Screen Printing
- 5.4.5 Other Printing Technologies
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Smurfit WestRock
- 6.4.2 International Paper Company
- 6.4.3 Mondi plc
- 6.4.4 GWP Group Ltd.
- 6.4.5 The Box Factory Ltd.
- 6.4.6 Belmont Packaging Ltd.
- 6.4.7 The Corrugated Case Company Ltd.
- 6.4.8 Nuttall Packaging
- 6.4.9 Cardboard Box Company Ltd.
- 6.4.10 Saica Group
- 6.4.11 Rigid Containers Ltd.
- 6.4.12 Board24 Ltd.
- 6.4.13 Cepac Holdings Ltd.
- 6.4.14 Boxes and Packaging (UK) Ltd.
- 6.4.15 LC Packaging UK Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


