

|
시장보고서
상품코드
2122701
자동차 와이어링 하네스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Automotive Wiring Harness - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
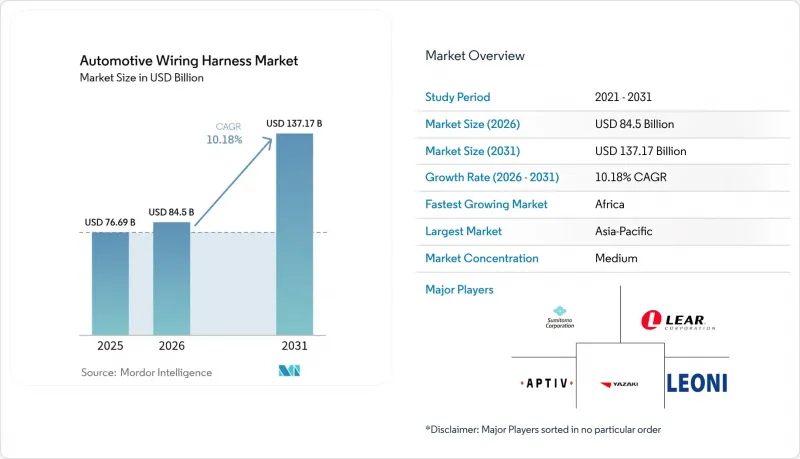
에 의하면, 2026년 자동차 와이어링 하네스 시장 규모는 845억 달러로 추정되고 2025년 766억 9,000만 달러에서 확대해, 2031년에는 1,371억 7,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 동안의 연평균 성장률(CAGR)은 10.18%가 될 것으로 전망됩니다.

본 보고서는 용도별(점화 시스템, 기타), 도체 재료별(구리, 기타), 정격 전압별(저전압(60V 미만), 기타), 추진 방식별(내연기관 차량, 기타),차종별(승용차, 기타), 유통 채널별(OEM, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)과 수량(개)으로 제시되어 있습니다.
세계의 자동차 와이어링 하네스 시장 동향 및 인사이트
전동화에 힘입은 고전압 와이어 하네스 수요 급증
배터리 팩의 전압이 800V, 나아가 1,000V로 상승함에 따라, 엄격한 전자기 호환성(EMC) 기준을 충족하면서도 더 큰 열 부하를 견딜 수 있는 새로운 등급의 케이블 어셈블리 수요가 촉진되고 있습니다. 현재 많은 중국 브랜드가 주 구동 라인에 알루미늄계 도체를 지정하고 있어, 소재 혁신이 전기차(EV)의 비용 절감으로 직결되고 있습니다. 알루미늄에는 새로운 접합 기술이 필요하기 때문에 각 공급업체들은 5년 전에는 볼 수 없었던 속도로 마찰 용접 및 레이저 용접 설비에 대한 투자를 진행하고 있습니다. 여기서 도출되는 새로운 관점은 경쟁상의 중요한 장벽으로서 구리 원자재 조달보다 용접 노하우가 머지않아 그 위상을 능가할 가능성이 있다는 점입니다.
OEM에 의한 경량 알루미늄·광섬유 하네스 추진
자동차 제조업체들은 1그램 단위의 경량화를 지속적으로 추구하고 있으며, 고급차의 경우 배선 무게가 20kg 이상을 차지하기도 합니다. 알루미늄 도체는 구리에 비해 질량을 약 60% 줄일 수 있을 뿐만 아니라, 구리 가격 변동 위험도 낮춥니다. 전도율이 낮다는 단점은 접촉 저항을 사양 범위 내로 억제하는 다심 설계나 바이메탈 단자를 통해 상쇄되고 있습니다. 연결 기술이 성숙해짐에 따라, 여러 OEM이 알루미늄 전력선과 데이터용 광섬유를 결합한 혼합 도체 하네스를 도입하고 있으며, 이는 다음 단계가 단일 금속 솔루션이 아닌 하이브리드 복합 하네스에 있음을 시사합니다.
구리·수지 가격 변동에 따른 이익률 압박
기존 하네스에서 구리는 부품 총 원가의 절반 이상을 차지하기 때문에 최근의 가격 변동으로 인해 공급업체의 매출 총이익률이 압박받고 있습니다. 대부분의 라인 핏 계약에는 가격 전가 조항이 포함되어 있지만, 자동차 제조업체들은 생산 주기 도중에 가격 인상을 수용하는 데 점점 더 소극적인 태도를 보이고 있습니다. 따라서 공급업체들은 리스크 분산책으로 상품 거래소에서 헤지를 하거나 알루미늄으로의 다각화를 추진하고 있습니다. 이러한 상황은 수익성을 확보하는 데 있어 재무 설계 및 조달 전략의 고도화가 핵심 엔지니어링과 동등한 중요성을 띠고 있음을 여실히 보여주고 있습니다.
부문별 분석
2025년 자동차 와이어링 하네스 시장 규모에서 차체, 조명, 실내 편의 시스템이 가장 큰 비중을 차지하며, 시장 규모의 35.35%를 차지했습니다. LED의 높은 보급률, 파워 리프트 게이트, 멀티존 공조 모듈이 수요를 지속시키는 요인으로 작용하고 있습니다. 흥미롭게도, 판매 대수를 끌어올리는 이러한 편의 장비는 차량의 최종 조립을 복잡하게 만드는 요인이 되기도 하여, 각 OEM 업체들은 대시보드나 도어 패널에 스냅 방식으로 장착 가능한, 미리 구성된 서브 하네스를 요구하고 있습니다.
충전·전원 시스템용 하네스는 2031년까지 연평균 성장률(CAGR) 25.44%라는 가장 높은 성장률을 보일 것으로 예측되며, 전기자동차 모델이 쇼룸에 늘어남에 따라 10%대 중반의 성장률을 유지할 전망입니다. 이러한 하네스는 배터리 팩 주변의 급격한 온도 상승과 기계적 진동을 견뎌야 하기 때문에 고품질의 절연 재료가 주류를 이루고 있습니다. 수냉 슬리브 및 초박형 차폐 기술을 확보한 공급업체는 프리미엄 가격대에서 제품을 판매할 수 있을 것으로 보입니다. 향후에는 고전압 배선에 대한 전문 지식이 배터리 관리 시스템으로의 교차 판매 발판이 될 가능성이 있습니다.
구리는 타의 추종을 불허하는 전도성과 1세기에 걸친 제조 노하우에 힘입어, 현재도 자동차 와이어링 하네스 시장 점유율의 약 93.45%를 차지하고 있습니다. 그러나 그 고밀도와 가격 변동성으로 인해 OEM의 조달 부서는 대체 소재를 검토해야 하는 상황에 직면해 있습니다. 새로운 트렌드로, 구리제 데이터 페어와 알루미늄 전원 코어를 동일한 주선에 묶어 신호 무결성을 해치지 않으면서 경량화를 실현하는 방식이 주목받고 있습니다.
알루미늄의 예상 연평균 성장률(CAGR)은 2031년까지 11.95%를 나타낼 것으로 전망되며, 이는 자동차 와이어링 하네스 산업 전체의 성장 궤도를 쉽게 상회하는 수치입니다. 내식성 단자와 마찰 용접 연결 기술의 발전으로 인해 과거의 신뢰성 관련 우려는 해소되었습니다. 알루미늄은 구리에 비해 가격이 안정적이기 때문에 재무 부문에서는 헤지 수단으로서 그 사용을 모델링하는 사례가 늘고 있습니다. 이러한 변화는 주요 공급업체에서 재료 과학적 선택이 재무 위험 관리 전략과 직접적으로 연결되어 있음을 보여줍니다.
지역별 분석
아시아태평양은 자동차 와이어링 하네스 시장 점유율의 약 48.40%를 차지하며, 절대적인 매출 성장률이 가장 높은 지역입니다. 중국은 막대한 경차 생산 대수와 탄탄한 전기차(EV) 공급망을 통해 이 지역의 중심적인 역할을 하고 있는 반면, 일본과 한국은 데이터 및 고전압 용도에 활용되는 첨단 연구 개발(R&D)에 기여하고 있습니다. 인도 및 동남아시아의 전동화를 위한 정부 지원책은 세계 경제 성장이 정상화되더라도 해당 지역 수요가 계속해서 견조한 추세를 보일 것임을 시사합니다. 주목할 만한 동향으로, 여러 중국 OEM 업체들이 유럽으로 전기차를 수출하고 있으며, 이를 위해서는 유럽연합(EU)의 규제 기준을 충족하는 통일된 배선 사양이 요구되므로, 아시아에 기반을 둔 공급업체들도 세계 규정 준수 기준을 충족하도록 하고 있습니다.
아프리카에서는 2026년부터 2031년까지 11.79%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 경쟁력 있는 인건비, 유럽연합(EU)과의 무역 협정에 따른 시장 접근성, 정부의 산업단지 정책이 맞물려 하네스 부문에 대한 새로운 투자를 유치하고 있습니다. 유럽의 여러 Tier 1 기업들이 노동 집약도가 높은 하위 조립품의 생산을 해당 지역으로 이전하고 있으며, 이를 통해 자국 시장의 공장에서 자동화 공정을 도입할 수 있게 되었습니다. 케이블 압착 및 품질 검사와 관련된 현지 근로자 기술 향상 프로그램도 등장하고 있어, 인적 자본 전략이 지역 성장과 밀접하게 연결되어 있음을 시사하고 있습니다.
북미와 유럽의 성장세는 다소 완만하지만, 여전히 기술 최첨단을 달리고 있습니다. 존 아키텍처(Zone Architecture) 시범 프로젝트는 독일의 고급 브랜드와 북미의 전기차 스타트업에 집중되어 있으며, 뮌헨, 슈투트가르트, 실리콘밸리의 디자인 사무소가 차세대 와이어 하네스 컨셉의 중추 역할을 하고 있습니다. 이러한 추세는 지식재산 창출이 노동 집약적 생산과 점차 분리되고 있음을 시사합니다. 이에 따라 OEM 본사 인근에 연구개발(R&D) 클러스터가 형성되고, 대량 생산 조립 공정이 비용 최적화된 지역으로 이전되는 이른바 ‘양극화된 세계 전개’가 더욱 강화되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, automotive wiring harness market size in 2026 is estimated at USD 84.5 billion, growing from 2025 value of USD 76.69 billion with 2031 projections showing USD 137.17 billion, growing at 10.18% CAGR over 2026-2031.
This report is Segmented by Application Type (Ignition System, and More), Conductor Material (Copper, and More), Voltage Rating (Low-Voltage [less Than 60V] and More), Propulsion Type (Internal Combustion Engine Vehicles and More), Vehicle Type (Passenger Cars and More), Sales Channel (OEM and More) and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Automotive Wiring Harness Market Trends and Insights
Electrification-Driven Surge in High-Voltage Harness Demand
Rising battery pack voltages to 800 V and even 1000 V are spurring a new class of cable assemblies that carry greater thermal loads while meeting tight electromagnetic-compatibility (EMC) targets. Many Chinese brands now specify aluminum-based conductors for main traction lines, directly linking material innovation to EV cost reduction. Because aluminum requires revised joining techniques, suppliers are investing in friction and laser welding cells at a pace unseen five years ago. An emerging inference is that welding know-how may soon overshadow raw copper sourcing as the key competitive barrier.
OEM Push for Lightweight Aluminum and Optical Harnesses
Automakers continue to chase every gram of weight saving, and wiring can account for more than 20 kg in premium cars. Aluminum conductors slash mass by roughly 60% relative to copper and also cut exposure to copper-price swings. The downside-lower conductivity-is being offset through multi-strand designs and bimetal terminals that keep contact resistance within specification. As connection technology matures, several OEMs have introduced mixed conductor looms that pair aluminum power lines with optical fibres for data, hinting that the next frontier will lie in hybrid composite bundles rather than single-metal solutions.
Margin Pressure from Volatile Copper and Resin Prices
Copper accounts for well over half of total bill-of-materials cost in a conventional loom, so recent price gyrations have compressed supplier gross margin. Although most line-fit contracts include pass-through clauses, automakers are increasingly reluctant to accept mid-cycle price increases. Suppliers are therefore hedging on commodity exchanges and diversifying into aluminum as a risk-spreading measure. The situation underscores that financial engineering and procurement sophistication are becoming as important as core engineering in safeguarding profitability.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Centralized Zonal E/E Architectures in Premium Cars
- Regulatory Mandates for ADAS Wiring Redundancy
- EV-Specific Thermal and EMC Challenges Raising Validation Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Body, Lighting, and Cabin Comfort systems command the largest share of the Automotive Wiring Harness market size in 2025, accounting for 35.35% of the market size. High LED adoption, power lift-gates, and multi-zone climate modules explain persistent demand. An interesting observation is that the same comfort features that boost volume also complicate final vehicle assembly, nudging OEMs to request pre-configured sub-looms that snap into dashboards and door panels.
Charging and power supply system harnesses show the fastest forecast CAGR expanding at an 25.44% through 2031, expanding in the mid-teens as more electric models reach showrooms. These harnesses must endure temperature spikes and mechanical vibration around battery packs, so higher-grade insulation materials are becoming mainstream. Suppliers that master liquid-cooling sleeves and low-profile shielding will likely command premium price points. Over time, expertise in high-voltage routing may provide cross-selling entry into battery management systems.
Copper retains around 93.45% of the Automotive Wiring Harness market share today, supported by unmatched conductivity and a century of process know-how. Yet its density and volatile cost profile keep pressure on OEM purchasing departments to pursue alternatives. An emerging pattern is the bundling of copper data pairs with aluminum power cores in the same trunk line, achieving weight reduction without sacrificing signal integrity.
Aluminum's forecast CAGR is 11.95% by 2031, easily outpacing the broader Automotive Wiring Harness industry trajectory. Advances in anti-corrosion terminals and friction-weld splice techniques have removed earlier reliability concerns. Because aluminum is price-stable relative to copper, finance teams increasingly model its use as a hedge. The shift indicates that material science choices now intersect directly with treasury risk management strategies inside large suppliers.
Complete Report Scope:
- By Application
- Ignition System
- Charging & Power Supply System
- Drivetrain & Powertrain (ICE)
- High-Voltage Traction Harness (xEV)
- Infotainment, Cockpit & Telematics
- ADAS & Safety Control
- Body, Lighting & Cabin Comfort
- By Conductor Material
- Copper
- Aluminum
- By Voltage Rating
- Low-Voltage (<60 V)
- High-Voltage (60-1,000 V)
- By Propulsion Type
- Internal Combustion Engine Vehicles
- Battery Electric Vehicles
- Plug-in Hybrid & Hybrid Vehicles
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy-duty Trucks & Buses
- By Sales Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East
- GCC
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia Pacific holds almost 48.40% Automotive Wiring Harness market share and boasts the fastest absolute revenue expansion. China anchors the region through its vast light-vehicle output and deep EV supply chains, while Japan and South Korea contribute high-grade R&D for data and high-voltage applications. Government incentives for electrification in India and Southeast Asia suggest that regional demand will remain resilient even as global growth normalises. A noteworthy development is that multiple Chinese OEMs are exporting EVs to Europe, requiring harmonised wiring specifications that meet European Union regulatory norms and thus elevating Asia-based suppliers to global compliance standards.
Africa, records the highest CAGR of 11.79% between 2026-2031. Competitive labour costs, trade-agreement access to the European Union, and government industrial-park policies together attract fresh harness investment. Several European tier-1 firms are locating high-labour-content sub-assemblies in the region, freeing up home-market plants for automated processes. Local workforce up-skilling programs in cable crimping and quality inspection are emerging, indicating that human-capital strategy is entwined with regional growth.
North America and Europe grow more modestly but remain technology front-runners. Zonal architecture pilots are concentrated in German luxury brands and North American electric start-ups, so design offices in Munich, Stuttgart, and Silicon Valley serve as nerve centres for next-generation loom concepts. This pattern implies that intellectual property creation is decoupling from labour-intensive production. This reinforces the two-speed global footprint in which R&D clusters near OEM headquarters and large-batch assembly migrate to cost-optimised regions.
- Yazaki Corporation
- Sumitomo Electric Industries Ltd.
- LEONI AG
- Lear Corporation
- Motherson Wiring Harness Ltd.
- Furukawa Electric Co. Ltd.
- Fujikura Ltd.
- Kyungshin Corporation
- Draexlmaier Group
- Kromberg & Schubert
- Nexans Autoelectric
- PKC Group (Motherson)
- Coroplast Fritz Muller GmbH & Co.
- THB Group
- Prestolite Wire LLC
- Lear Yangzhou (China)
- Guangdong Hivolt Wiring Harness
- BizLink Holding Inc.
- Shanghai Shenglong Automotive Harness
- Samvardhana Motherson Reydel
- Korea Electric Terminal Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Drivers
- 4.1.1 Electrification-Driven Surge in High-Voltage Harness Demand (Asia)
- 4.1.2 OEM Push for Lightweight Aluminum & Optical Harnesses
- 4.1.3 Shift Toward Centralized Zonal E/E Architectures in Premium Cars (EU)
- 4.1.4 Regulatory Mandates for ADAS Wiring Redundancy (US, Japan)
- 4.1.5 Rising Local Content Rules Fueling Wire-Harness Localization (India, Mexico)
- 4.1.6 Autonomous Vehicle Development Driving Redundant Circuit Architectures
- 4.2 Market Restraints
- 4.2.1 Margin Pressure From Volatile Copper & Resin Prices
- 4.2.2 EV-Specific Thermal & EMC Challenges Raising Validation Costs
- 4.2.3 Mismatch Between Design Complexity & Skilled Labor Availability (ASEAN)
- 4.2.4 Manufacturing Automation Limitations Constraining Productivity Gains
- 4.3 Value / Supply-Chain Analysis
- 4.4 Regulatory & Technological Outlook
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Application
- 5.1.1 Ignition System
- 5.1.2 Charging & Power Supply System
- 5.1.3 Drivetrain & Powertrain (ICE)
- 5.1.4 High-Voltage Traction Harness (xEV)
- 5.1.5 Infotainment, Cockpit & Telematics
- 5.1.6 ADAS & Safety Control
- 5.1.7 Body, Lighting & Cabin Comfort
- 5.2 By Conductor Material
- 5.2.1 Copper
- 5.2.2 Aluminum
- 5.3 By Voltage Rating
- 5.3.1 Low-Voltage (<60 V)
- 5.3.2 High-Voltage (60-1,000 V)
- 5.4 By Propulsion Type
- 5.4.1 Internal Combustion Engine Vehicles
- 5.4.2 Battery Electric Vehicles
- 5.4.3 Plug-in Hybrid & Hybrid Vehicles
- 5.5 By Vehicle Type
- 5.5.1 Passenger Cars
- 5.5.2 Light Commercial Vehicles
- 5.5.3 Heavy-duty Trucks & Buses
- 5.6 By Sales Channel
- 5.6.1 OEM
- 5.6.2 Aftermarket
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Rest of North America
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Spain
- 5.7.2.5 Russia
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 South Korea
- 5.7.3.5 Rest of Asia Pacific
- 5.7.4 Middle East
- 5.7.4.1 GCC
- 5.7.4.2 Turkey
- 5.7.4.3 Rest of Middle East
- 5.7.5 Africa
- 5.7.5.1 South Africa
- 5.7.5.2 Egypt
- 5.7.5.3 Rest of Africa
- 5.7.6 South America
- 5.7.6.1 Brazil
- 5.7.6.2 Argentina
- 5.7.6.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Strategic Initiatives
- 6.2 Market Share Analysis
- 6.3 Company Profiles
- 6.3.1 Yazaki Corporation
- 6.3.2 Sumitomo Electric Industries Ltd.
- 6.3.3 LEONI AG
- 6.3.4 Lear Corporation
- 6.3.5 Motherson Wiring Harness Ltd.
- 6.3.6 Furukawa Electric Co. Ltd.
- 6.3.7 Fujikura Ltd.
- 6.3.8 Kyungshin Corporation
- 6.3.9 Draexlmaier Group
- 6.3.10 Kromberg & Schubert
- 6.3.11 Nexans Autoelectric
- 6.3.12 PKC Group (Motherson)
- 6.3.13 Coroplast Fritz Muller GmbH & Co.
- 6.3.14 THB Group
- 6.3.15 Prestolite Wire LLC
- 6.3.16 Lear Yangzhou (China)
- 6.3.17 Guangdong Hivolt Wiring Harness
- 6.3.18 BizLink Holding Inc.
- 6.3.19 Shanghai Shenglong Automotive Harness
- 6.3.20 Samvardhana Motherson Reydel
- 6.3.21 Korea Electric Terminal Co.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


