|
시장보고서
상품코드
2122888
전자책 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)E-book - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
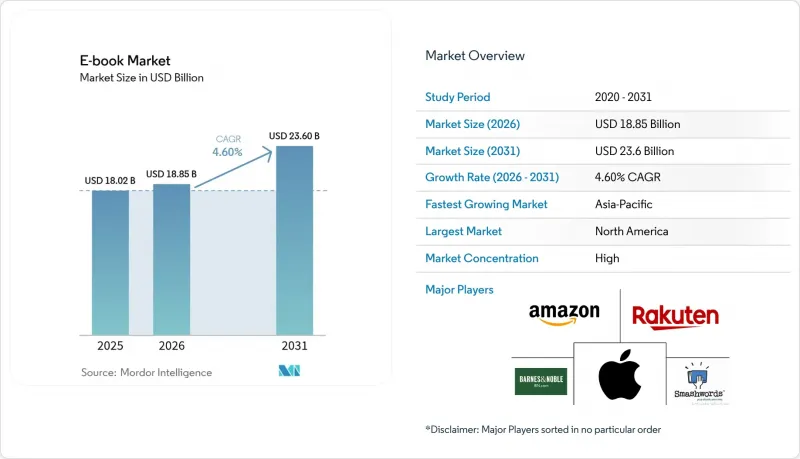
전자책 시장 규모는 2025년 180억 2,000만 달러로 평가되었고, 2026년에는 188억 5,000만 달러로 추정되고, 2026-2031년 CAGR 4.6%로 성장을 지속할 전망이며, 2031년에는 236억 달러에 이를 것으로 예측됩니다.
본 보고서는 수익 모델별(구독, 다운로드 과금, 프리미엄/광고 수익형, 기관용 라이선싱), 장르별(소설, 논픽션, 교육·학술, 만화·그래픽 노블, 전문·기술 서적), 최종 사용자별(개인 소비자, 기관) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 전자책 시장 동향 및 인사이트
모바일 기기의 보급 확대
스마트폰 보급률이 높아짐에 따라 디지털 독서의 중심이 전용 전자책 리더기에서 상시 연결이 가능한 단말기로 이동하고 있습니다. 출판사는 이러한 실정을 활용하여 단편 컨텐츠의 에피소드를 배포하거나, 세로 스크롤에 최적화하거나, 매일의 연속 독서 습관을 강화하는 게임화 요소를 도입하고 있습니다. 디스플레이 제조업체들은 장시간 독서 시 눈의 피로를 줄이기 위해 반사 방지 기능을 갖춘 OLED 스크린과 적응형 재생률 개선을 추진하고 있습니다. AI를 활용한 추천 엔진의 부상으로 앱 내 컨텐츠 발견이 더욱 개인화되어, 완독률과 세션당 평균 독서 시간이 향상되고 있습니다. 기기 교체 주기가 짧은 아시아태평양에서는 현재 프리미엄 기기에 독서 앱이 사전 설치되어 있어, 이것이 전자책 시장으로 들어가는 기본적인 진입로가 되고 있습니다.
전 세계 인터넷 접속 환경의 확대
차세대 광대역의 전개와 5G 백홀 투자로 인해, 그동안 대역폭 비용으로 인해 제약을 받았던 시장에서도 대상 사용자층이 확대되고 있습니다. GSMA의 ‘Digital Nations’ 프레임워크에 따르면, 아시아태평양의 18개 정부는 경제 경쟁력의 핵심 요소로서, 모든 곳에 통신 커버리지를 확보하는 것을 최우선 과제로 삼고 있습니다. 더 빠르고 저렴한 접속 환경 덕분에 출판사는 용납할 수 없을 정도의 로딩 시간을 발생시키지 않으면서도 고해상도 일러스트, 음성 발췌문, 단편 동영상을 삽입할 수 있게 되었습니다. 지역의 대역폭 품질에 따른 동적 가격 책정도 점차 보급되고 있습니다. 통신 속도가 느린 네트워크를 이용하는 독자는 저렴한 저비트레이트 요금제를 선택할 수 있어, 인프라의 현실을 고려하면서도 접근성을 확보할 수 있습니다. 또한, 연결성 향상으로 클라우드 동기화의 장벽이 제거되어 여러 기기 간에 끊김 없이 읽기 진행 상황을 추적할 수 있게 됩니다.
전자책 판매업체와 저자 간의 개인정보 보호 및 저작권 문제
디지털 저작권 관리 및 데이터 이용을 둘러싼 복잡한 문제는 유통 생태계의 분열을 초래할 우려가 있습니다. 유럽 규제 당국은 GDPR(EU 개인정보보호규정)에 근거한 제재를 적용하고 있으며, 규정 준수를 위한 인프라 유지에 어려움을 겪는 소규모 출판사의 경우 연간 디지털 수익의 10% 이상을 부담해야 할 가능성이 있습니다. 관리형 디지털 대여를 둘러싼 소송은 공정 이용의 경계에 대한 모호성이 여전히 남아 있음을 여실히 드러내고 있으며, 이로 인해 기관의 구매 결정이 지연되고 도서관 채널 내 전자책 시장의 단기적 성장이 억제되고 있습니다. 저자들은 AI 기업들이 동의 없이 전문을 스크래핑하고 있지 않은지에 대한 의구심을 키우고 있으며, 존스 홉킨스 대학 출판국과 같은 초기 도입자들은 모델 학습에 대한 보상을 보장하는 명확한 AI 라이선싱 체계를 수립할 것을 촉구받고 있습니다. 선견지명을 가진 출판사들은 컨텐츠 거래에 대한 블록체인 타임스탬프를 모색하고 있으며, 각 사본이 언제, 어디서, 어떻게 접근되었는지를 기록함으로써 투명성과 감사 가능성을 높이고 있습니다.
부문 분석
구독 서비스는 2025년 매출의 55.72%를 차지했으며, 계속해서 전자책 시장의 확장을 이끄는 원동력이 되고 있습니다. 데이터가 풍부한 이러한 환경은 새로운 시리즈의 알고리즘 기반 기획에 활용되어, 도서가 사전에 선정된 독자층을 대상으로 확실하게 출시될 수 있도록 하고 있습니다. 주로 도서관 및 기업 교육 포털을 대상으로 하는 기관용 라이선싱은 사용자 1인당 지출액이 높은 점을 배경으로 연평균 성장률(CAGR) 5.05%라는 가장 급격한 성장세를 보이고 있습니다. 이러한 상승 추세는 사용자 수가 소비자 대상 구독 서비스에 미치지 못함에도 불구하고 전자책 시장 규모에 크게 기여하고 있습니다. 지속적인 접근이 필수적인 학술 단행본이나 전문 참고서의 경우, 다운로드당 과금 모델이 여전히 정착되어 있지만, 비용에 민감한 지역에서는 광고 공간 수익화나 소셜 미디어 공유 후 챕터 잠금 해제 등의 프리미엄 모델이 기세를 얻고 있습니다.
출판사들은 ‘컨텐츠 아즈 어 서비스(Content as a Service)’를 중심으로 워크플로우를 구축하고, 실시간 오탈자 수정 및 멀티미디어 컨텐츠 추가를 통해 디지털 백리스트를 혁신하고 있습니다. 이러한 라이프사이클 연장을 통해 수익 인식이 안정화되고, 카탈로그의 지속성이 강화됩니다. 플랫폼의 경우, 구독 해지율 관리는 과학적인 영역이 되었습니다. 예측 분석을 통해 참여도가 떨어지고 있는 독자를 파악하고, 해지 위험이 정점에 달하기 전에 엄선된 푸시 알림이나 로열티 보상을 제공합니다. 통합된 결제 시스템을 통해 요금제 업그레이드가 간소화되어, 열성 독자들을 오디오북과 그래픽 컨텐츠가 포함된 프리미엄 요금제로 유도하고 있습니다. 이러한 노력은 참여도 향상을 통해 구독형 전자책 시장 점유율이 해마다 확대되는 선순환을 강화하고 있습니다.
지역별 분석
북미는 정착된 전자책 리더 이용 습관, 높은 광대역 보급률, 그리고 도서관 및 학술 기관 구매자들이 형성한 긴밀한 생태계 덕분에 2025년에도 39.45%의 점유율을 유지했습니다. 주요 플랫폼들은 챕터를 요약하거나 문장을 즉시 번역해 주는 AI 기반 독서 지원 도구에 투자하며, 시간에 쫓기는 비즈니스맨들의 참여도를 높이고 있습니다. 플랫폼의 독점 거래에 대한 규제 당국의 조사는 아직 구조적인 시정 조치로 이어지지는 않았지만, 인수 전략을 억제하는 효과를 가져오고 있어 기존 기업들은 적극적인 컨텐츠 임베디드보다는 고객 중심의 기능 업그레이드에 주력하도록 압박받고 있습니다.
아시아태평양은 스마트폰 보급과 유연한 모바일 결제 시스템에 힘입어 2031년까지 연평균 성장률(CAGR) 4.72%를 기록하며 지역별 가장 빠른 성장세를 보이고 있습니다. 일본의 디지털 만화 매출은 2020년 이후 2배로 증가했으며, 한편 한국의 웹툰은 드라마나 게임으로의 각색을 통해 IP의 지속적인 가치를 높여 소비자를 원작 타이틀로 다시 불러들이고 있습니다. GSMA에 따르면 싱가포르, 한국, 호주에서는 5G 커버리지율이 거의 100%에 달하고, 대역폭을 대량으로 소비하는 인터랙티브 도서에 유리한 여건이 조성되어 있습니다. 동남아시아의 스타트업 기업들은 1장을 몇 센트에 판매하는 ‘소량 단위 가격 책정’을 시도하고 있으며, 이를 통해 합리적인 가격대가 확대되면서 전자책 시장이 활성화되고 있습니다.
유럽에서는 기관 차원의 디지털화 의무화 및 국경을 초월한 컨텐츠 규제를 배경으로 꾸준한 성장이 나타나고 있습니다. GDPR(EU 개인정보보호규정) 준수는 소비자의 신뢰를 창출하고, 비용이 많이 드는 데이터 처리 안전 대책을 부과하는 한편, 구독 전환율을 향상시키고 있습니다. 다국어 지원 수요가 높아지는 가운데, 출판사들은 현지화 리드타임을 단축하는 AI 번역 파이프라인에 대한 투자를 가속화하고 있습니다. 독일과 네덜란드에서는 블록체인을 활용한 시범 프로젝트를 통해 투명성이 높은 로열티 지급 방식이 시험적으로 도입되어, 지급 주기를 수개월에서 수일로 단축하는 것을 목표로 하고 있습니다. 이와 병행하여, 영국은 브렉시트 이후의 복잡한 라이선싱 문제를 해결하는 동시에, 견고한 독립 출판업계의 강점을 살려 온디맨드 인쇄 추가 서비스를 통합한 ‘독자 대상 직접 판매 번들’ 실험을 진행하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the e-book market size is expected to grow from USD 18.02 billion in 2025 to USD 18.85 billion in 2026 and is forecast to reach USD 23.6 billion by 2031 at 4.6% CAGR over 2026-2031.
This report is Segmented by Revenue Model (Subscription, Pay-Per-Download, Freemium/Ad-supported, and Institutional Licensing), Genre (Fiction, Non-Fiction, Education and Academic, Comics and Graphic Novels, and Professional and Technical), End-User (Individual Consumers, and Institutional), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global E-book Market Trends and Insights
Increasing Penetration of Mobile Devices
Smartphone saturation has shifted the center of gravity for digital reading away from dedicated e-readers and toward always-connected handsets. Publishers capitalize on this reality by releasing bite-sized content episodes, optimizing for vertical scrolling, and layering in gamified achievements that reinforce daily reading streaks. Display manufacturers are refining glare-free OLED screens and adaptive refresh rates that reduce eye strain during extended reading sessions. The rise of AI-driven recommendation engines further personalizes in-app discovery, boosting completion rates and average reading time per session. In Asia Pacific, where handset upgrades occur on rapid cycles, premium devices now ship with pre-installed reading apps that create a default pathway into the e-book market.
Expanding Global Internet Connectivity
Next-generation broadband rollouts and 5G backhaul investments expand addressable audiences in markets historically constrained by bandwidth cost. GSMA's Digital Nations framework shows 18 Asia Pacific governments prioritizing ubiquitous coverage as a pillar of economic competitiveness. Faster, cheaper connections enable publishers to embed high-resolution artwork, audio snippets, and short-form video without incurring intolerable load times. Dynamic pricing tied to regional bandwidth quality is also gaining traction: readers on slower networks can opt for lower-bitrate packages at reduced prices, preserving accessibility while respecting infrastructure realities. Enhanced connectivity likewise removes frictions for cloud synchronization, ensuring seamless progress tracking across multiple devices.
Privacy and Copyright Issues Among E-sellers and Authors
Complexities around digital rights management and data usage threaten to fragment distribution ecosystems. European regulators enforce GDPR penalties that can absorb more than 10% of annual digital revenue for small presses struggling to maintain compliant infrastructure. Controlled digital lending lawsuits underscore lingering ambiguity over fair-use boundaries, delaying institutional purchasing decisions and depressing near-term e-book market growth in library channels. Authors increasingly question whether AI companies scrape full texts without consent, prompting early adopters like Johns Hopkins University Press to craft explicit AI licensing frameworks that guarantee compensation for model training. Forward-looking publishers explore blockchain timestamping of content transactions to record when, where, and how each copy is accessed, enhancing transparency and auditability.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Digital Education and E-learning
- Rising Adoption of Subscription-Based Reading Platforms
- Persistent Preference for Print Books in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Subscription services commanded 55.72% of 2025 revenue and remain the engine behind the e-book market expansion. Their data-rich environments inform algorithmic commissioning of new series, ensuring that titles debut with pre-qualified audiences. Institutional licensing, chiefly libraries and corporate training portals, shows the sharpest momentum, growing at 5.05% CAGR on a base of high per-user spending. That uptrend contributes meaningfully to the e-book market size even though its user count trails consumer subscriptions. Pay-per-download persists for academic monographs and professional references where perpetual access is mandatory, while freemium models gain traction in cost-sensitive territories by monetizing advertising inventory or unlocking chapters after social sharing actions.
Publishers are engineering workflows around "content-as-a-service," refreshing digital backlists with real-time errata fixes and multimedia add-ons. This lifecycle extension smooths revenue recognition and strengthens catalog durability. For platforms, subscription churn management has become a science: predictive analytics flag disengaging readers so that curated push notifications or loyalty rewards arrive before cancellation risk peaks. Integrated payment rails simplify tier upgrades, nudging heavy readers toward premium plans that bundle audiobooks or graphic content. These measures reinforce a virtuous loop wherein higher engagement elevates the e-book market share of subscription formats year over year.
Complete Report Scope:
- By Revenue Model
- Subscription (all-you-can-read)
- Pay-per-download
- Freemium / Ad-supported
- Institutional licensing
- By Genre
- Fiction
- Non-fiction
- Education and Academic
- Comics and Graphic Novels
- Professional and Technical
- By End-user
- Individual Consumers
- Adults
- Children and Young Adults
- Institutional
- K-12 Schools
- Higher Education
- Corporate / Professional Training
- Public Libraries
- Individual Consumers
- By Geography
- North America
- United States
- Canada
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Indonesia
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained its 39.45% share in 2025 owing to entrenched e-reader habits, high broadband penetration, and a dense ecosystem of library and academic buyers. Leading platforms invest in AI-generated reading companions that summarize chapters and translate passages on the fly, raising engagement among time-pressed professionals. Regulatory inquiries into platform exclusivity have not yet produced structural remedies, but they do temper acquisition strategies, pushing incumbents to focus on customer-centric feature upgrades rather than aggressive content hoarding.
Asia Pacific charts the fastest regional expansion at a 4.72% CAGR through 2031, propelled by smartphone ubiquity and flexible mobile payment systems. Japanese digital manga revenue has doubled since 2020, while Korean webtoons add recurring IP value thanks to drama and gaming adaptations that rebound consumers back into source titles. GSMA notes that Singapore, South Korea, and Australia achieve near-total 5G coverage, creating fertile ground for bandwidth-heavy interactive books. South-East Asian start-ups experiment with sachet-pricing, selling single chapters for cents, thereby broadening affordability and bolstering the e-book market.
Europe grows steadily on the back of institutional digitization mandates and cross-border content regulation. GDPR compliance engenders consumer trust, elevating subscription conversion rates though it imposes costly data-handling safeguards. Multilingual requirements spur publishers to invest in AI-translation pipelines that reduce localization timelines. Blockchain pilots in Germany and the Netherlands test transparent royalty disbursement, aiming to shorten payment cycles from months to days. In parallel, the UK navigates post-Brexit licensing complexities, leveraging its robust independent press scene to experiment with direct-to-reader bundles that integrate print-on-demand add-ons.
- Amazon.com, Inc.
- Rakuten Kobo Inc.
- Apple Inc.
- Barnes and Noble, LLC
- Smashwords, Inc.
- Blurb, Inc.
- DIY Media Group, Inc.
- Lulu Press, Inc.
- Macmillan Publishers Ltd
- Scribd, Inc.
- Google LLC
- Hachette Livre SA
- HarperCollins Publishers LLC
- Penguin Random House LLC
- Draft2Digital, LLC
- OverDrive, Inc.
- Storytel AB
- Wattpad Corp.
- Inkitt GmbH
- John Wiley and Sons, Inc.
- Pearson plc
- Cengage Learning, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing penetration of mobile devices
- 4.2.2 Expanding global internet connectivity
- 4.2.3 Growth of digital education and e-learning
- 4.2.4 Rising adoption of subscription-based reading platforms
- 4.2.5 Blockchain-enabled rights management and micropayments
- 4.2.6 Publisher D2C storefront integration with CRM data
- 4.3 Market Restraints
- 4.3.1 Privacy and copyright issues among e-sellers and authors
- 4.3.2 Persistent preference for print books in emerging markets
- 4.3.3 Interoperability limitations across e-reader ecosystems
- 4.3.4 Digital fatigue driving screen-time reduction initiatives
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Revenue Model
- 5.1.1 Subscription (all-you-can-read)
- 5.1.2 Pay-per-download
- 5.1.3 Freemium / Ad-supported
- 5.1.4 Institutional licensing
- 5.2 By Genre
- 5.2.1 Fiction
- 5.2.2 Non-fiction
- 5.2.3 Education and Academic
- 5.2.4 Comics and Graphic Novels
- 5.2.5 Professional and Technical
- 5.3 By End-user
- 5.3.1 Individual Consumers
- 5.3.1.1 Adults
- 5.3.1.2 Children and Young Adults
- 5.3.2 Institutional
- 5.3.2.1 K-12 Schools
- 5.3.2.2 Higher Education
- 5.3.2.3 Corporate / Professional Training
- 5.3.2.4 Public Libraries
- 5.3.1 Individual Consumers
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Chile
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Spain
- 5.4.3.5 Italy
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Indonesia
- 5.4.4.6 Rest of Asia Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 Saudi Arabia
- 5.4.5.1.2 United Arab Emirates
- 5.4.5.1.3 Turkey
- 5.4.5.1.4 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Nigeria
- 5.4.5.2.3 Egypt
- 5.4.5.2.4 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Amazon.com, Inc.
- 6.4.2 Rakuten Kobo Inc.
- 6.4.3 Apple Inc.
- 6.4.4 Barnes and Noble, LLC
- 6.4.5 Smashwords, Inc.
- 6.4.6 Blurb, Inc.
- 6.4.7 DIY Media Group, Inc.
- 6.4.8 Lulu Press, Inc.
- 6.4.9 Macmillan Publishers Ltd
- 6.4.10 Scribd, Inc.
- 6.4.11 Google LLC
- 6.4.12 Hachette Livre SA
- 6.4.13 HarperCollins Publishers LLC
- 6.4.14 Penguin Random House LLC
- 6.4.15 Draft2Digital, LLC
- 6.4.16 OverDrive, Inc.
- 6.4.17 Storytel AB
- 6.4.18 Wattpad Corp.
- 6.4.19 Inkitt GmbH
- 6.4.20 John Wiley and Sons, Inc.
- 6.4.21 Pearson plc
- 6.4.22 Cengage Learning, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment