|
시장보고서
상품코드
2122891
방충제 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Insect Repellent - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
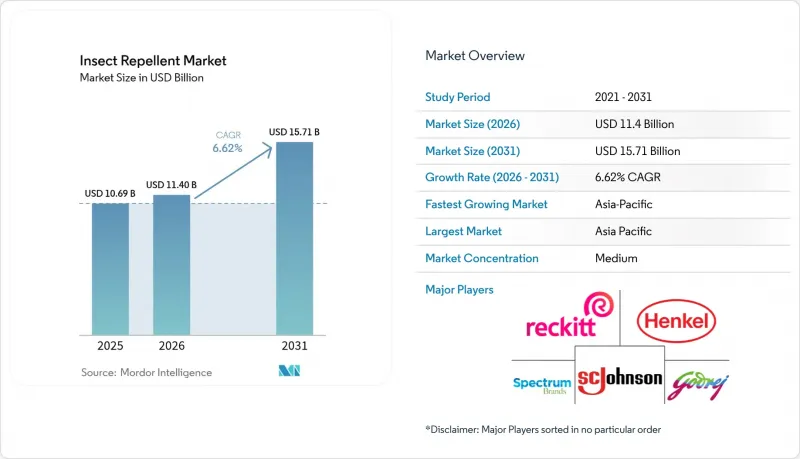
방충제 시장 규모는 2026년에 114억 달러로 추정되고, 2025년 106억 9,000만 달러에서 확대해, 2031년에는 157억 1,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 6.62%로 성장할 것으로 전망됩니다.
본 보고서는 제품 유형별(유인제, 모기향, 스프레이/에어로졸,매트, 액체 증발기 등), 성분 유형별(천연 유래 방충제 및 기존 방충제), 최종 사용자별(성인 및 어린이), 유통 채널별(슈퍼마켓 및 하이퍼마켓, 편의점, 온라인 소매점 등), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 방충제 시장 동향 및 인사이트
매개성 질환 증가
매개체에 의한 감염병은 전 세계적으로 증가하는 추세입니다. 세계보건기구(WHO)는 2024년 9월 팩트시트에서 모기, 진드기 및 기타 절지동물에 의해 매개되는 질병으로 인해 연간 70만 명 이상이 사망하고 있다고 지적했습니다. 기후 변화로 인해 매개 생물의 서식지가 북쪽으로 더욱 확대되고 있으며, 과거에는 안전하다고 여겨졌던 온대 지역에도 말라리아와 뎅기열의 위협이 미치고 있습니다. 미국 질병통제예방센터(CDC)에 따르면, 2024년에는 북미, 중남미, 남미 및 카리브해 지역에서 1,300만 건 이상의 뎅기열 사례가 보고되었습니다. 2025년에도 이들 지역의 뎅기열 감염 상황은 여전히 높은 수준을 유지하고 있습니다. 이러한 급증으로 인해 새롭게 위험에 노출된 이들 지역에서 모기 퇴치제에 대한 수요가 증가하고 있습니다. 또한, 말라리아 매개 곤충의 피레스로이드계 살충제에 대한 내성은 현재 전 세계적인 우려 사항으로 대두되고 있으며, 감시 대상 지역의 80% 이상에 영향을 미치고 있습니다. 이러한 내성으로 인해 소비자들은 대체 유효 성분을 찾게 되었고, 새로운 제형 개발 혁신이 촉진되고 있습니다. 이러한 과제에 대응하기 위해 각국의 보건 당국은 개인 예방 조치에 대한 권고를 강화하고 있습니다. 특히, CDC는 매개 곤충에 대한 효과적인 예방 조치로 DEET, 피카리딘, IR3535를 최우선 선택지로 꼽고 있습니다.
야외 레크리에이션 활동 증가
팬데믹으로 인한 라이프스타일 변화에 따라 야외 레크리에이션 참여가 현저히 증가했습니다. 예를 들어, 아웃도어 재단(Outdoor Foundation)의 보고에 따르면, 2024년 미국에서 6,340만 명 이상이 적어도 한 번은 하이킹에 참여했습니다. 이는 2010년 이후 가장 높은 참여율이며, 지난 15년간 약 31퍼센트 포인트 증가세를 보였습니다. 소비자들이 레크리에이션 용품에 해충 방지 기능을 도입하는 추세가 강해짐에 따라, 어드벤처 관광 및 아웃도어 스포츠 용품의 매출은 방충제 시장의 성장과 직접적인 상관관계를 보이고 있습니다. 이러한 추세는 캠핑이나 하이킹과 같은 전통적인 활동에 그치지 않고, 현재는 야외 식사, 축제, 도시 녹지 이용 등으로까지 확대되어 시장의 범위가 자연 애호가들에게만 국한되지 않게 되었습니다. 또한, 건설, 농업, 조경 등의 분야에서 일하는 전문 야외 근로자들은 종종 간과되기 쉽지만, 업무용 방충제 수요를 크게 끌어올리고 있습니다.
대체 방충 대책과의 경쟁
대체 방충 기술이 기존 방충제 시장에 점점 더 침투하고 있습니다. 퍼메트린으로 처리된 의류, 모기장, 전자 기기 등의 제품은 그 유효성에 대한 증거가 여전히 엇갈리고 있음에도 불구하고 소비자들의 관심을 끌고 있습니다. 체계적 문헌 고찰에 따르면, 전자식 모기 퇴치 장치는 모기의 착륙을 막는 데 있어 측정 가능한 방제 효과를 발휘하지 못하는 것으로 나타났습니다. 그럼에도 불구하고 소비자들은 편의성과 ‘화학 물질 미사용’이라는 매력에 이끌려 계속해서 이러한 제품을 채택하고 있습니다. 퍼메트린 처리된 의류는 도포형 방충제보다 방충 효과가 오래 지속된다는 점을 내세우고 있지만, 이러한 장점은 특히 야외에서 일하는 전문가나 군 관계자들에게 시장에서 대체 위험을 초래하고 있습니다. 주거 환경에서는 환경 조절, 생물학적 방제, 물리적 장벽을 결합한 통합 해충 관리(IPM) 전략을 통해 개인용 방충 제품에 대한 의존도가 점차 낮아지고 있습니다. 또한, 그 유효성을 부정하는 과학적 증거가 있음에도 불구하고, 초음파식 방충 기능을 내세우는 스마트폰 앱의 부상은 대체 기술을 모색하려는 소비자의 동향을 여실히 보여주고 있으며, 기존 제품에서 벗어나는 속도를 늦출 가능성도 있습니다.
부문 분석
2025년에는 스프레이 및 에어로졸 제품이 시장 점유율의 45.72%를 차지했으며, 그 편의성, 휴대성, 그리고 폭넓은 소비자에게 어필하는 즉각적인 효과를 바탕으로 시장을 주도하고 있습니다. 한편, 액체식 기화기는 가장 빠르게 성장하는 부문으로, 2031년까지 연평균 성장률(CAGR)이 7.32%를 나타낼 것으로 전망됩니다. 이러한 급속한 성장은 공간 보호 기술의 발전과 핸즈프리로 지속적인 방충 효과를 원하는 소비자의 성향 변화에 힘입은 것입니다. 코일 제품은 연소 부산물에 대한 우려에도 불구하고 가격에 민감한 시장에서 확고한 입지를 유지하고 있는 반면, 매트 제품은 기존의 코일과 최신 액상 시스템의 중간적인 위치를 차지하고 있습니다. 종합 해충 관리(IPM)용으로 설계된 미끼 제품은 규제상의 장벽과 복잡한 사용 방법 때문에 성장에 어려움을 겪고 있습니다.
액체형 발연기는 특히 서방 메커니즘과 휘발성 피레스로이드 제제에 대한 특허를 취득한 혁신 기술의 혜택을 받고 있습니다. 특히 2024년 7월, 고드레이지 컨슈머 프로덕츠(Godrej Consumer Products)는 액체형 발연기를 위해 개발된 인도 최초의 국산 모기 퇴치 분자인 ‘레노플루트린’을 발표했습니다. 이러한 첨단 제제는 카트리지당 12시간의 보호 효과를 약속하며, 유효 성분의 안정적인 방출을 보장합니다. 이 혁신은 효과의 지속을 원하는 소비자의 요구에 부응하는 것이며, 잦은 재도포의 필요성을 줄여줍니다. 웨어러블 기기나 전자식 디스펜서와 같은 신흥 카테고리는 방충 성분공급 기능을 일용품에 통합하고 있지만, 해당 시장에서의 존재감은 여전히 미미하며, 효능 검증과 비용 절감을 기다리고 있는 상황입니다.
2025년, 기존 방충제는 82.10%의 시장 점유율을 차지했으며, 이는 수십 년에 걸친 입증된 효과, 규제 당국의 승인, 그리고 DEET, 피카리딘, 피레스로이드 제제를 위한 확립된 제조거점에 힘입은 것입니다. 반면, 천연 유래 방충제는 성장 궤도에 올라 있으며, 2031년까지의 연평균 성장률(CAGR)은 8.05%로 전망됩니다. 이러한 급속한 성장의 배경에는 소비자의 건강에 대한 인식 제고와 레몬 유칼립투스 오일 및 각종 에센셜 오일 블렌드와 같은 식물 유래 유효 성분에 대한 규제 당국의 지지가 있습니다. 성장률의 격차는 소비자의 우선순위 변화를 여실히 보여주고 있습니다. 현재 많은 소비자들은 안전성과 환경적 지속가능성이 향상된다면, 방충 효과의 지속 시간이 짧아도 괜찮다고 생각합니다.
연구를 통해 천연 성분의 효능이 입증되었습니다. 예를 들어, PMD(파라멘탄-3,8-디올)는 적절한 농도로 사용될 경우 주요 매개 생물 종에 대해 DEET와 동등한 효과를 발휘합니다. 또한, 나노 에멀젼 기술 등의 발전으로 식물 유래 성분의 안정성과 생체 이용률이 향상되고 있습니다. 이 혁신적인 기술은 급속한 분해나 효능의 편차와 같이 식물 유래 방충제가 기존에 안고 있던 과제를 해결해 줍니다. 천연 제품에 대한 프리미엄 가격 수용도가 높아지면서 이익률 확대 가능성이 시사되고 있지만, 식물 유래 성분 조달에 따른 과제가 시장 점유율의 급속한 확대를 저해할 가능성이 있습니다.
지역별 분석
2025년, 아시아태평양은 전 세계 매출의 49.10%를 차지했으며, 2031년까지의 기간 동안 9.15%라는 지역별 최고 연평균 성장률(CAGR)을 기록하고 있습니다. 이는 주로 뎅기열과 말라리아에 대한 공중보건상의 지속적인 관심이 주도한 결과입니다. 대중매체를 통한 캠페인의 후원을 받은 정부 주도의 계몽 활동으로 인해 방충제의 보급이 대폭 확대되었습니다. 현지 연구 개발 역량의 우수성을 보여주는 사례로, 인도의 ‘굿나이트 플래시’(유효 성분: 레노플루트린)는 수입 비용을 절감할 뿐만 아니라 공급 안정성도 높이고 있습니다. 가처분 소득 증가에 따라 도시 지역 가구에서는 기존의 모기향에서 액체형 모기 퇴치기로의 전환이 진행되고 있으며, 이에 따라 지역 방충제 시장은 더욱 확대되고 있습니다.
북미는 다른 지역에 비해 다소 뒤처져 있지만, 주로 야외 레크리에이션 활동과 모기가 매개하는 질병의 확산으로 인해 상당한 규모를 자랑하고 있습니다. 2024년, 미국의 소매 매출액은 3억 7,690만 달러라는 눈부신 수치를 기록했습니다. 이 지역에서는 식물 유래 성분에 대한 선호도가 높아, 혁신적인 기업들은 프리미엄 가격 책정과 높은 이익률을 실현할 수 있습니다. 또한 기후 변화로 인해 북부 주들의 모기 발생 시즌이 장기화되면서, 이전에는 여름에 급격한 수요 정점이 나타났던 것과 달리 현재는 방충제에 대한 월별 수요가 더욱 안정적으로 유지되고 있습니다.
유럽의 성장은 엄격한 화학 물질 규제로 인해 제약을 받고 있으며, 업계는 생태독성학 기준을 충족하는 천연 유래 성분 배합으로 전환하고 있습니다. 독일과 프랑스는 지속가능성 인증을 추진하고 재활용 가능한 포장재 채택을 주도하는 최전선에 서 있습니다.
아프리카와 중동에서는 기부자들의 자금 지원을 받은 이니셔티브를 통해 말라리아 유행 지역에서의 유통이 강화되어, 저소득층 커뮤니티에서도 방충제를 더 쉽게 구할 수 있게 되었습니다.
한편, 라틴아메리카에서는 열대 지역으로의 도시 확장에 따라 매개 생물과의 접촉이 증가하고 있으며, 이에 따라 다양한 제품공급이 급증하고 현지 생산에 대한 투자도 활발해지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, insect repellent market size in 2026 is estimated at USD 11.4 billion, growing from 2025 value of USD 10.69 billion with 2031 projections showing USD 15.71 billion, growing at 6.62% CAGR over 2026-2031.
This report is Segmented by Product Type (Bait, Coils, Sprays/Aerosols, Mats, Liquid Vaporizer, and More), by Ingredient Type (Natural Insect Repellent and Conventional Insect Repellent), by End User (Adults and Kids/Children), by Distribution Channel (Supermarkets/Hypermarkets, Convenience Stores, Online Retail Stores, and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Insect Repellent Market Trends and Insights
Rise in Vector-borne Diseases
Vector-borne diseases are on the rise worldwide. The World Health Organization (WHO) highlighted in its September 2024 factsheet that over 700,000 deaths occur annually due to diseases spread by mosquitoes, ticks, and other arthropods. Climate change is pushing vector habitats further north, bringing malaria and dengue threats to temperate regions that were once safe. According to the Centers for Disease Control and Prevention, in 2024, more than 13 million cases of dengue were reported in North, Central, and South America and the Caribbean. Dengue transmission in these areas remains high in 2025. This surge has led to a heightened demand for repellents in these newly at-risk areas. Furthermore, pyrethroid resistance in malaria vectors is now a global concern, affecting over 80% of monitored sites. This resistance is steering consumers towards alternative active ingredients and spurring innovation in new formulations. In response to these challenges, government health agencies are amplifying their recommendations for personal protective measures. Notably, the CDC has highlighted DEET, picaridin, and IR3535 as top choices for effective protection against disease vectors.
Increasing Outdoor Recreational Activities
In the wake of pandemic-induced lifestyle changes, outdoor recreation saw a notable uptick in participation. For example, the Outdoor Foundation reported that in 2024, over 63.4 million individuals in the U.S. engaged in hiking activities at least once. This marks the highest participation rate since 2010, showcasing a growth of approximately 31 percentage points over the past 15 years. As consumers increasingly incorporate pest protection into their recreational gear, sales in adventure tourism and outdoor sports equipment have seen a direct correlation with the growth of the repellent market. This trend isn't limited to traditional activities like camping and hiking; it now encompasses outdoor dining, festivals, and the use of urban green spaces, expanding the market's reach beyond just wilderness enthusiasts. Moreover, professional outdoor workers from sectors like construction, agriculture, and landscaping, often overlooked, are significantly boosting the demand for commercial-grade repellents.
Competition from Alternative Protection Methods
Alternative protection technologies are increasingly encroaching on the traditional repellent market. Products like permethrin-treated clothing, bed nets, and electronic devices are drawing consumer interest, even as evidence of their efficacy remains mixed. Systematic reviews indicate that electronic mosquito repellents fail to offer measurable protection against mosquito landings. Yet, consumers continue to adopt them, swayed by their perceived convenience and the allure of being chemical-free. While permethrin-treated clothing boasts a longer protection duration than topical repellents, this advantage poses a substitution risk in the market, especially for outdoor professionals and military users. In residential settings, integrated pest management strategies, merging environmental tweaks, biological controls, and physical barriers, are diminishing the dependence on personal repellent products. Furthermore, the rise of smartphone apps touting ultrasonic repellent features, despite scientific evidence debunking their effectiveness, underscores a consumer trend: a willingness to explore alternative technologies, potentially postponing the shift away from traditional products.
Other drivers and restraints analyzed in the detailed report include:
- Growing Pet Ownership
- Shifting Consumer Preferences Towards Natural Products
- Consumer Health Concerns Over Chemicals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, sprays and aerosols command the market with a 45.72% share, capitalizing on their convenience, portability, and instant application appeal to a wide range of consumers. Meanwhile, liquid vaporizers are the fastest-growing segment, boasting a 7.32% CAGR through 2031. This surge is fueled by tech advancements in spatial protection and a consumer shift towards hands-free, continuous coverage. While coils hold their ground in price-sensitive markets, despite concerns over combustion byproducts, mats strike a balance between traditional coils and modern liquid systems. Bait products, tailored for integrated pest management, face growth challenges due to regulatory hurdles and complex applications.
Liquid vaporizers are reaping the rewards of patent innovations, especially in controlled-release mechanisms and volatile pyrethroid formulations. Notably, in July 2024, Godrej Consumer Products unveiled 'Renofluthrin', India's inaugural indigenous mosquito repellent molecule, tailored for liquid vaporizers. These advanced formulations promise 12-hour protection per cartridge, ensuring a steady release of active ingredients. This innovation meets consumer demands for prolonged efficacy, reducing the need for frequent reapplications. Emerging categories like wearable devices and electronic dispensers are weaving repellent delivery into everyday products, but their market presence is still modest, awaiting validation of efficacy and a drop in costs.
In 2025, conventional insect repellents command an 82.10% market share, bolstered by decades of proven efficacy, regulatory endorsements, and a well-established manufacturing base for DEET, picaridin, and pyrethroid formulations. Meanwhile, natural insect repellents are on a growth trajectory, boasting an 8.05% CAGR through 2031. This surge is fueled by a rising consumer health consciousness and regulatory backing for botanical active ingredients, such as oil of lemon eucalyptus and various essential oil blends. The disparity in growth rates underscores a shift in consumer priorities: many now prefer shorter protection durations if it means enhanced safety and environmental sustainability.
Research underscores the efficacy of natural ingredients. For instance, PMD (para-menthane-3,8-diol) matches DEET's performance against major vector species, provided it's used in the right concentrations. Furthermore, advancements like nano-emulsion technologies bolster the stability and bioavailability of botanical ingredients. This innovation addresses the traditional challenges of plant-based repellents, such as swift degradation and variable efficacy. While there's a growing acceptance of premium pricing for natural products, hinting at potential margin expansions, challenges in sourcing botanical ingredients could temper swift market share growth.
Complete Report Scope:
- By Product Type
- Bait
- Coils
- Sprays/Aerosols
- Mats
- Liquid Vaporizer
- Other Product Types
- By Ingredient Type
- Natural Insect Repellent
- Conventional Insect Repellent
- By End User
- Adults
- Kids/Children
- By Distribution Channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Online Retail Stores
- Other Distribution Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Sweden
- Belgium
- Poland
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Thailand
- Singapore
- Indonesia
- South Korea
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- South Africa
- Saudi Arabia
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Geography Analysis
In 2025, the Asia-Pacific region accounted for 49.10% of global revenue, and the region also registers the strongest regional CAGR at 9.15% during the period to 2031, primarily driven by the ongoing public health focus on dengue and malaria. Government-led awareness initiatives, bolstered by mass media campaigns, have significantly increased the adoption of repellents. A testament to local research and development capabilities, India's Goodknight Flash, featuring Renofluthrin, not only cuts down on import costs but also fortifies supply resilience. With rising disposable incomes, urban households are upgrading from traditional coils to liquid vaporizers, further expanding the regional insect repellent market.
North America, while trailing, boasts substantial figures, largely due to outdoor recreational activities and the spread of insect-borne diseases. In 2024, retail sales in the U.S. reached an impressive USD 376.9 million. The region's strong preference for botanical ingredients allows for premium pricing and higher margins for innovators. Additionally, climate change has lengthened the mosquito season in northern states, leading to a more consistent monthly demand for insect repellents, rather than the previously sharp summer peak.
Europe's growth is tempered by stringent chemical regulations, pushing the industry towards natural formulations that align with eco-toxicology standards. Germany and France are at the forefront, championing sustainability certifications and driving the adoption of recyclable packaging.
In the Middle East and Africa, donor-funded initiatives are bolstering distribution in malaria-prone areas, making repellents more accessible to lower-income communities.
Meanwhile, Latin America's urban sprawl into tropical regions is increasing contact with disease vectors, prompting a surge in diverse product offerings and investments in localized manufacturing.
- S.C. Johnson & Son Inc.
- Reckitt Benckiser Group PLC
- Spectrum Brands Holdings Inc.
- Godrej Consumer Products Ltd.
- Dabur India Ltd.
- Henkel AG & Co. KGaA
- Newell Brands Inc.
- Enesis Group
- Quantum Health
- Jyothy Labs Limited
- Sawyer Products Inc.
- Avon Products Inc.
- Tender Corporation (Natrapel)
- Kao Corporation
- The Coleman Company, Inc.
- Merck KGaA (IR3535)
- 3M
- Coleman (Repel brand)
- Wondercide Inc.
- Sawyer Products, Inc.
- Enesis Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rise in Vector-borne Diseases
- 4.2.2 Increasing Outdoor Recreational Activities
- 4.2.3 Growing Pet Ownership
- 4.2.4 Shifting Consumer Preferences Towards Natural Products
- 4.2.5 Rapid Technological Advancements Driving Innovation
- 4.2.6 Government and Public Health Campaigns
- 4.3 Market Restraints
- 4.3.1 Competition from Alternative Protection Methods
- 4.3.2 Consumer Health Concerns Over Chemicals
- 4.3.3 Insecticide Resistance
- 4.3.4 Availability of Counterfeit Products
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Product Type
- 5.1.1 Bait
- 5.1.2 Coils
- 5.1.3 Sprays/Aerosols
- 5.1.4 Mats
- 5.1.5 Liquid Vaporizer
- 5.1.6 Other Product Types
- 5.2 By Ingredient Type
- 5.2.1 Natural Insect Repellent
- 5.2.2 Conventional Insect Repellent
- 5.3 By End User
- 5.3.1 Adults
- 5.3.2 Kids/Children
- 5.4 By Distribution Channel
- 5.4.1 Supermarkets/Hypermarkets
- 5.4.2 Convenience Stores
- 5.4.3 Online Retail Stores
- 5.4.4 Other Distribution Channels
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.1.4 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Colombia
- 5.5.2.4 Chile
- 5.5.2.5 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Sweden
- 5.5.3.8 Belgium
- 5.5.3.9 Poland
- 5.5.3.10 Netherlands
- 5.5.3.11 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 Thailand
- 5.5.4.5 Singapore
- 5.5.4.6 Indonesia
- 5.5.4.7 South Korea
- 5.5.4.8 Australia
- 5.5.4.9 New Zealand
- 5.5.4.10 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 South Africa
- 5.5.5.3 Saudi Arabia
- 5.5.5.4 Nigeria
- 5.5.5.5 Egypt
- 5.5.5.6 Morocco
- 5.5.5.7 Turkey
- 5.5.5.8 Rest of Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 S.C. Johnson & Son Inc.
- 6.4.2 Reckitt Benckiser Group PLC
- 6.4.3 Spectrum Brands Holdings Inc.
- 6.4.4 Godrej Consumer Products Ltd.
- 6.4.5 Dabur India Ltd.
- 6.4.6 Henkel AG & Co. KGaA
- 6.4.7 Newell Brands Inc.
- 6.4.8 Enesis Group
- 6.4.9 Quantum Health
- 6.4.10 Jyothy Labs Limited
- 6.4.11 Sawyer Products Inc.
- 6.4.12 Avon Products Inc.
- 6.4.13 Tender Corporation (Natrapel)
- 6.4.14 Kao Corporation
- 6.4.15 The Coleman Company, Inc.
- 6.4.16 Merck KGaA (IR3535)
- 6.4.17 3M
- 6.4.18 Coleman (Repel brand)
- 6.4.19 Wondercide Inc.
- 6.4.20 Sawyer Products, Inc.
- 6.4.21 Enesis Group