|
시장보고서
상품코드
2122900
중국의 건설기계 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)China Construction Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 중국의 건설기계 시장 규모는 2025년 561억 8,000만 달러로 평가되었습니다. 2026년에는 596억 2,000만 달러로 확대되어 2031년까지 802억 4,000만 달러에 이를 것으로 예상되고 2026-2031년에 걸쳐 CAGR 6.12%로 성장할 전망입니다.

본 보고서는 기계 유형(토공 기계, 자재관리 기계, 기타), 구동 방식(내연기관, 하이브리드, 기타), 유통 채널(OEM 직접 판매, 공식 대리점 판매), 용도(건축 공사, 인프라 건설, 기타)별로 분류되어 있습니다. 시장 전망은 금액(달러)과 수량(대)으로 제시되어 있습니다.
중국의 건설기계 시장 동향 및 인사이트
정부의 ‘신 인프라 2025-30’ 계획
중앙 계획 당국은 교통망, 수자원 프로젝트, 송전망 회랑을 향후 5년간의 정비 계획의 핵심으로 삼고 있습니다. 초기 단계의 프로젝트 목록에 따라 이미 굴삭기, 크레인, 도로 건설 기계에 대한 입찰 활동이 활발해지고 있습니다. 서부 변방 성에서 활동하는 건설업체들은 지형 및 기후 문제에 신속하게 대응할 수 있는 국산 브랜드를 선호하고 있습니다. 또한, 기업들이 수년에 걸친 건설 프로젝트 참여 시 자산을 최소화하는 방침을 취함에 따라 건설 기계 임대 수요도 증가하고 있습니다. 이러한 변화들이 맞물려 주택 건설이 부진한 상황에서도 안정적인 수주 흐름이 확보되고 있습니다.
탄소 중립 의무가 전기 기계 보급을 뒷받침
중국의 배출권 거래제에 따라 현재 중공업용 탄소 가격이 책정되어 있어, 현장 관리자들은 수명 주기 전반에 걸친 연료비와 규제 준수 비용을 더욱 신중하게 비교 검토할 수밖에 없게 되었습니다. 그 결과, 제로 배출 모델은 실증용 차량군에서 일반 조달 목록으로 점차 전환되고 있으며, 특히 엄격한 대기질 목표가 부과된 도시 지역 프로젝트에서 이러한 경향이 두드러집니다. 연안 지역 지자체는 전기 차량을 도입하는 건설업체에 대해 허가 절차 간소화 및 홍보상의 이점을 제공합니다. 이에 대응하여 각 제조업체는 배터리 및 구동 시스템의 생산 능력을 확대하는 한편, 구매자가 느끼는 위험을 완화하기 위해 애프터서비스 체계를 강화하고 있습니다. 이러한 가격 외의 인센티브 덕분에 순수한 경제성만으로는 설명할 수 없을 정도로 도입이 가속화되고 있습니다.
장기화되는 부동산 시장의 침체
아파트 분양 부진이 민간 개발사의 현금 흐름을 계속해서 압박하고 있어, 콘크리트 펌프나 타워 크레인, 기타 건축 관련 기계에 대한 수요를 억제하고 있습니다. 정부의 구제 조치조차도 이러한 하락 추세를 막는 데 그칠 뿐, 반전시키지는 못하고 있습니다. 대형 렌탈 업체들은 주택 건설에서 인프라 건설로 차량을 재배치하고 있지만, 가동률 하락은 여전히 해소되지 않고 있습니다. 콘크리트 기계에 대한 의존도가 높은 제조업체들은 현재 부품 및 서비스 수입에 대한 의존도를 높이고 있습니다. 가계 경기 심리가 호전될 때까지는 고층 건축 관련 기계가 시장 전체의 성장에 뒤처질 것으로 예측됩니다.
부문별 분석
2025년 중국의 건설기계 시장에서 굴삭기는 55.28%의 점유율을 차지하며, 기계 유형 개발 및 공급업체의 우선순위에 결정적인 영향을 미쳤습니다. 토공, 광업, 철거 공사에서의 범용성 덕분에 경기 사이클과 관계없이 수요는 견조한 추세를 보이고 있습니다. 건설업체들은 단일 베이스 머신을 다양한 작업에 대응할 수 있는 솔루션으로 전환해 주는 점점 더 다양해지는 부착 장치를 높이 평가했습니다. 한편, 인건비 급등에 따라 작업자의 피로를 줄여주는 반자율형 굴착 모드에 대한 관심이 높아지고 있습니다. 전전기식 굴삭기는 현재로서는 제한적이지만, 제로 배출 솔루션으로의 단계적 전환을 반영하여 2031년 연평균 성장률(CAGR)이 12.15%로 예측되며, 이 부문에서 가장 높은 성장률을 달성할 것으로 전망됩니다.
기타 건설기계 부문도 이러한 ‘양극화’된 현실에 적응해 나가고 있습니다. 로더와 그레이더의 경우 연료 소비 감축을 위해 구동계가 개선되고 있으며, 불도저에서는 수소 엔진의 초기 시험이 진행되고 있습니다. 자재관리용 크레인은 해상 풍력 발전 및 모듈식 주택에 대응하기 위해 적재 용량을 확대되고 있습니다. 주택 시장 침체로 가장 큰 타격을 입은 콘크리트 관련 장비는 디지털 배치 처리 및 예측 유지보수 도입을 시도하며 시장 내 입지를 유지하려 하고 있습니다.
2025년 시점에서 중국의 건설기계 시장에서 디젤 동력의 점유율은 92.64%를 유지했습니다. 이는 잘 갖춰진 급유 인프라와 외진 지역에서의 입증된 높은 가동률 덕분입니다. 차량 관리자들은 익숙한 정비 절차와 부품의 폭넓은 입수 가능성을 높이 평가했습니다. 그러나 배기가스 규제의 강화와 도시 지역의 소음 규제로 인해 디젤의 장기적인 매력은 점차 약화되고 있습니다. 정책에 따른 인센티브와 배터리 비용의 하락이 맞물리면서, 경량급에서 디젤에서 다른 동력원으로의 전환은 점점 더 합리적인 선택지가 되고 있습니다.
완전 전기식 시스템은 출발점은 낮지만, 2031년까지 업계 최고 수준인 연평균 성장률(CAGR) 37.85%를 달성할 것으로 예측되어, 전환점에 도달했을 때의 변화 속도를 여실히 보여주고 있습니다. 하이브리드 차량은 이 두 극단 사이의 중간 지점에 위치하며, 주행 거리에 대한 불안감 없이 연료비 절감을 실현합니다. 일부 주에서는 하이브리드 차량에 탄소 크레딧을 부여하고 있어, 회의적인 사람들을 부분적인 전동화로 이끌고 있습니다. 수소를 연료로 사용하는 실증 사업에서는 중량물 운반이나 연속 운전이 필요한 작업에서의 실용성이 검증되고 있습니다. 이러한 대체 기술들이 결합되어, 획일적인 디젤 차량이 아닌 현장별 제약 조건에 맞추어 구동 방식을 선택할 수 있는 미래의 전망이 그려지고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the China construction equipment market size is expected to increase from USD 56.18 billion in 2025 to USD 59.62 billion in 2026 and reach USD 80.24 billion by 2031, growing at a CAGR of 6.12% over 2026-2031.
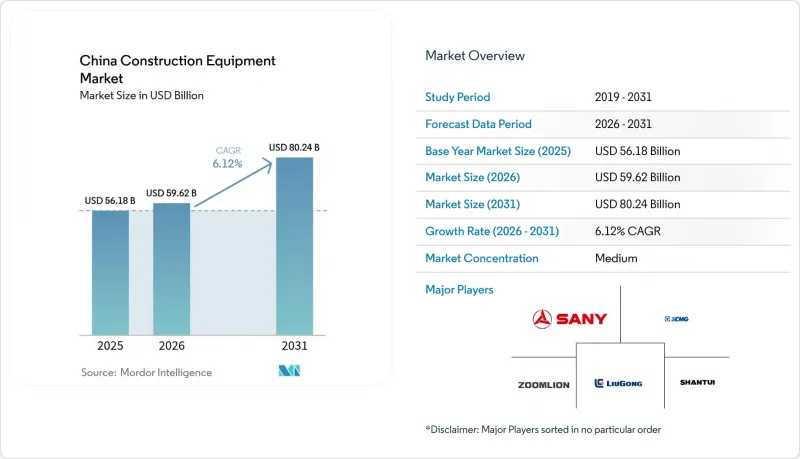
This report is Segmented by Machinery Type (Earth-Moving Machinery, Material-Handling Machinery, and More), Drive Type (Internal-Combustion Engine, Hybrid, and More), Sales Channel (OEM Direct Sales, and Authorized Dealer Sales), and Application (Building Construction, Infrastructure Construction, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
China Construction Equipment Market Trends and Insights
Government 'New Infrastructure 2025-30' Pipeline
Central planners have placed transport links, water projects, and power-grid corridors at the heart of the next 5-year build-out. The early-batch project list has already accelerated tender activity for excavators, cranes, and road equipment. Contractors active in remote western provinces prefer domestic brands that can respond quickly to terrain and climate challenges. Equipment-rental demand is also rising as firms opt for asset-light participation in multi-year construction packages. Together, these shifts anchor a dependable stream of orders even as residential construction lags.
Carbon-Neutral Mandate Spurring Electric Machinery
China's emissions-trading scheme now prices carbon for heavy industry, forcing site managers to weigh lifetime fuel and compliance costs more carefully. Zero-emission models are therefore moving from demonstration fleets into regular procurement lists, especially for urban projects that face strict air-quality targets. Local governments in coastal provinces offer expedited permits and publicity benefits to contractors using electric fleets. Manufacturers respond by expanding battery and drivetrain capacity while refining after-sales support to reduce buyers' perceived risk. These non-price incentives accelerate adoption beyond what pure economics would dictate.
Prolonged Real-Estate Downturn
Weak apartment presales continue to undermine private developers' cash flow, curbing demand for concrete pumps, tower cranes, and other building-centric gear. Even state rescue measures have merely slowed, not reversed, the slide. Large rental companies are redeploying fleets from housing to infrastructure, but utilization gaps remain. Manufacturers with heavy exposure to concrete machinery now lean harder on parts and service revenue. Until household sentiment turns, equipment tied to vertical construction is likely to lag broader market growth.
Other drivers and restraints analyzed in the detailed report include:
- OEM Export Push Enables Domestic Economies of Scale
- Digital Equipment-Rental Platforms Unlocking SME Demand
- Domestic Price Wars from Over-Capacity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Excavators captured 55.28% of the Chinese construction equipment market share in 2025, giving them a commanding influence over model development and supplier priorities. Their versatility in earthworks, mining, and demolition keeps demand resilient across cycles. Contractors value the growing range of attachments that convert one base machine into multiple task solutions. Meanwhile, rising labor costs elevate interest in semi-autonomous dig modes that reduce operator fatigue. Although full-electric excavators are currently limited, they are expected to achieve the segment's fastest growth, with a 12.15% CAGR projected through 2031, reflecting a gradual transition toward zero-emission solutions.
The rest of the machinery spectrum is adapting to this two-speed reality. Loaders and graders refine drivetrains for fuel savings, while dozers see early trials of hydrogen engines. Material-handling cranes stretch lifting capacities to serve offshore wind and modular housing. Concrete equipment, hit hardest by housing weakness, experiments with digital batching and predictive maintenance to stay relevant.
Diesel power retained 92.64% of the Chinese construction equipment market share in 2025, thanks to dense refueling infrastructure and proven uptime in remote areas. Fleet managers appreciate the familiar maintenance routines and broad availability of parts. However, tightening emissions caps and urban noise rules erode diesel's long-term appeal. Policy incentives, paired with falling battery costs, make the switch increasingly rational for lighter classes.
Full-electric systems, although starting from a low base, are projected to deliver a sector-leading 37.85% CAGR through 2031, underscoring the speed of change once tipping points are reached. Hybrids sit between these poles, offering fuel savings without range anxiety. Some provinces reward them with carbon credits, nudging skeptics toward partial electrification. Hydrogen pilots probe viability for heavy, continuous-duty tasks. Together, these alternatives sketch a future in which drivetrain choice aligns with specific site constraints rather than a one-size-fits-all diesel.
Complete Report Scope:
- By Machinery Type
- Earth-moving Machinery
- Excavators
- Loaders
- Dozers
- Material-Handling Machinery
- Cranes
- Fork-lifts
- Telescopic Handlers
- Road-Construction Machinery
- Motor Graders
- Rollers/Compactors
- Pavers
- Concrete Equipment
- Concrete Mixers
- Concrete Pumps
- Earth-moving Machinery
- By Drive Type
- Internal-Combustion Engine (Diesel)
- Hybrid
- Full-Electric
- By Sales Channel
- Original Equipment Manufacturer (OEM) Direct Sales
- Authorized Dealer Sales
- By Application
- Building Construction
- Infrastructure Construction
- Energy and Natural Resources
- Others
List of Companies Covered in this Report:
- Sany Group
- Xuzhou Construction Machinery Group Co., Ltd. (XCMG)
- Caterpillar Inc.
- Zoomlion Heavy Industry
- LiuGong Machinery
- Komatsu Ltd.
- Hitachi Construction Machinery
- AB Volvo (Volvo CE)
- Liebherr Group
- Shantui Construction Machinery
- Tadano Ltd.
- J.C. Bamford Excavators Limited
- Doosan Bobcat Ltd.
- Hyundai Construction Equipment Ltd.
- Yanmar Holdings Co. Ltd.
- Terex Corporation
- China Railway Construction Heavy Industry Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government 'New Infrastructure 2025-30' Pipeline
- 4.2.2 Carbon-Neutral Mandate Spurring Electric Machinery
- 4.2.3 OEM Export Push Enables Domestic Economies of Scale
- 4.2.4 Digital Equipment-Rental Platforms Unlocking SME Demand
- 4.2.5 Belt And Road Back-Orders for Component Suppliers
- 4.2.6 Provincial Carbon-Credit Markets Favouring Hybrids
- 4.3 Market Restraints
- 4.3.1 Prolonged Real-Estate Downturn
- 4.3.2 Domestic Price Wars from Over-Capacity
- 4.3.3 Tight Credit to SME Contractors
- 4.3.4 Inverter and BMS Chip Shortages For E-Equipment
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Machinery Type
- 5.1.1 Earth-moving Machinery
- 5.1.1.1 Excavators
- 5.1.1.2 Loaders
- 5.1.1.3 Dozers
- 5.1.2 Material-Handling Machinery
- 5.1.2.1 Cranes
- 5.1.2.2 Fork-lifts
- 5.1.2.3 Telescopic Handlers
- 5.1.3 Road-Construction Machinery
- 5.1.3.1 Motor Graders
- 5.1.3.2 Rollers/Compactors
- 5.1.3.3 Pavers
- 5.1.4 Concrete Equipment
- 5.1.4.1 Concrete Mixers
- 5.1.4.2 Concrete Pumps
- 5.1.1 Earth-moving Machinery
- 5.2 By Drive Type
- 5.2.1 Internal-Combustion Engine (Diesel)
- 5.2.2 Hybrid
- 5.2.3 Full-Electric
- 5.3 By Sales Channel
- 5.3.1 Original Equipment Manufacturer (OEM) Direct Sales
- 5.3.2 Authorized Dealer Sales
- 5.4 By Application
- 5.4.1 Building Construction
- 5.4.2 Infrastructure Construction
- 5.4.3 Energy and Natural Resources
- 5.4.4 Others
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Sany Group
- 6.4.2 Xuzhou Construction Machinery Group Co., Ltd. (XCMG)
- 6.4.3 Caterpillar Inc.
- 6.4.4 Zoomlion Heavy Industry
- 6.4.5 LiuGong Machinery
- 6.4.6 Komatsu Ltd.
- 6.4.7 Hitachi Construction Machinery
- 6.4.8 AB Volvo (Volvo CE)
- 6.4.9 Liebherr Group
- 6.4.10 Shantui Construction Machinery
- 6.4.11 Tadano Ltd.
- 6.4.12 J.C. Bamford Excavators Limited
- 6.4.13 Doosan Bobcat Ltd.
- 6.4.14 Hyundai Construction Equipment Ltd.
- 6.4.15 Yanmar Holdings Co. Ltd.
- 6.4.16 Terex Corporation
- 6.4.17 China Railway Construction Heavy Industry Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment