|
시장보고서
상품코드
2123154
유럽의 자전거 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Bicycle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
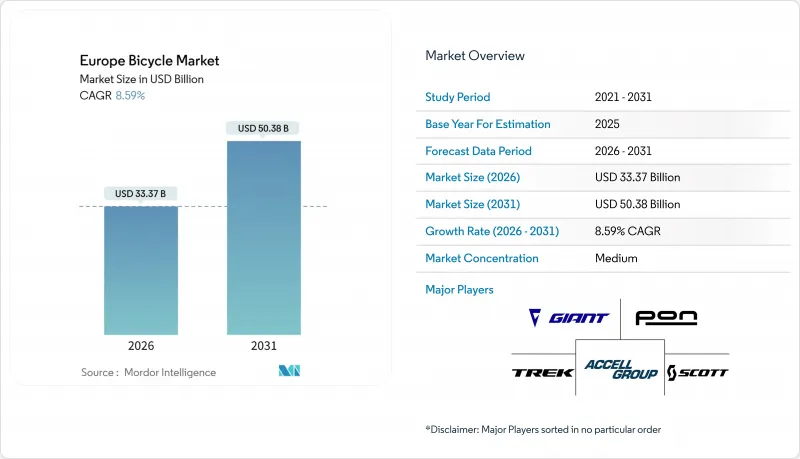
에 의하면, 유럽의 자전거 시장 규모는 2026년에 333억 7,000만 달러로 추정되고, 2031년까지 503억 8,000만 달러에 이를 것으로 예측되며, 예측 기간 중 연평균 복합 성장률(CAGR)은 8.59%를 나타낼 전망입니다.
본 보고서는 제품 유형별(로드/시티, 마운틴/올테레인, 하이브리드, 전동 자전거, 기타), 디자인별(일반형 및 접이식), 최종 사용자별(남성, 여성, 어린이), 유통 채널별(오프라인 매장 및 온라인 소매점), 지역별(영국, 독일, 프랑스,이탈리아, 스페인 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(대)으로 제시되어 있습니다.
유럽의 자전거 시장 동향 및 인사이트
도시 지역의 교통 체증이 통근용 자전거의 보급을 촉진하고 있습니다.
유럽의 도시들은 ‘퍼스트 마일’ 및 ‘라스트 마일’ 모빌리티 경제를 재정의함으로써 교통 체증 해소에 나서고 있습니다. 파리시는 2021-2026년 2억 5,000만 유로(2억 7,200만 달러)를 투자하여 총 길이 1,400킬로미터의 자전거 전용 차선을 조성할 계획입니다. 이러한 변화는 지자체가 ‘유도 수요’에 중점을 두고 있음을 반영하며, 레저용 모델보다 화물용 전동자전거나 스피드 페데렉을 우선시하고 있습니다. 도시 지역의 인구 밀도 증가와 유류비 급등으로 인해 자전거는 비용 대비 효과가 높은 대체 수단으로서의 입지를 확고히 하고 있습니다. 특히 전기 자전거는 통근 거리를 늘리고, 유연하며 저공해 이동 수단을 찾는 직장인들을 끌어들이고 있습니다. 유럽연합(EU)의 ‘지속 가능한 도시 이동성 계획’과 각국의 보조금 같은 정책을 통해 자전거가 대중교통 시스템에 통합되면서 퍼스트 마일 및 라스트 마일의 연결성이 향상되고, 자동차 의존도는 낮아지고 있습니다. 세계은행에 따르면, 2024년에는 유럽연합(EU) 인구의 75%가 도시 지역에 거주하게 되어 도시 지역의 교통 체증이 더욱 심화되고 있습니다. 이러한 인구 동향으로 인해 일상적인 이동 수요가 증가하고 있으며, 혼잡한 도시 지역을 이동하고 이동 시간을 최소화하기 위한 효율적인 해결책으로서 자전거와 전기 자전거의 보급이 확대되고 있습니다.
건강과 피트니스에 대한 인식이 높아지면서 레크리에이션으로서의 자전거 타기가 활성화되고 있습니다.
2024년 스포츠 잉글랜드(Sport England)의 보고서에 따르면, 잉글랜드에서는 716만 9,700명이 자전거 타기를 즐기고 있으며, 자전거 타기가 단순한 이동 수단에서 웰빙과 피트니스 습관의 핵심 요소로 크게 변화했음이 드러나고 있습니다. 이러한 변화는 팬데믹 이후 시대에 건강과 웰빙에 대한 관심이 높아짐에 따라 크게 촉진되고 있습니다. 그 결과, 피트니스 지향적인 소비자들은 합리적인 가격보다 성능 향상을 위한 경량 카본 프레임, 부드러운 변속을 실현하는 전자식 변속 시스템, 정확한 성능 모니터링을 위한 내장 파워미터와 같은 고급 기능을 점점 더 요구하고 있습니다. 이러한 프리미엄 제품에 대한 수요 증가로 인해, 제조업체들은 총 판매량이 안정화되기 시작했음에도 불구하고 높은 이익률을 유지할 수 있게 되었습니다. 또한, 이 소비자층은 가격에 대한 민감도가 낮기 때문에 2025년 2월 프랑스가 자전거 구매 보조금 제도를 폐지하기로 한 결정과 같은 정책 변화에 대해 제조업체들에게 일정한 내성을 제공합니다.
대체 교통수단의 부상이 자전거 시장 점유율을 압박
전동 킥보드의 인기 상승과 고속 교통망의 확장으로 인해, 도시 지역의 모빌리티 예산은 점점 더 세분화되고 있습니다. 공유형 전동 킥보드는 자전거나 도보 이동뿐만 아니라 대중교통 이용까지 대체하고 있습니다. 이는 마이크로모빌리티 옵션이 자동차보다는 오히려 자전거와 더 직접적으로 경쟁하고 있음을 여실히 보여줍니다. 네덜란드에서는 공공 도로에서의 전동 킥보드 사용이 금지되어 있어, 이로 인해 자전거 시장이 보호받고 있습니다. 반면, 스페인이나 프랑스에서는 전동 킥보드가 허용되어 있어 직접적인 경쟁이 격화되고 있습니다. 이탈리아에서는 뿌리 깊은 오토바이 문화가 상황을 더욱 복잡하게 만들고 있습니다. 로마나 밀라노와 같은 도시에서는 교통 체증세가 부과되고 있음에도 불구하고, 날씨로부터의 보호나 속도 면에서 오토바이가 여전히 인기를 끌고 있어 자전거 보급을 제한하고 있습니다. 자전거 제조업체들은 속도나 편의성을 우선시하기보다는 적재 용량이나 내후성 같은 실용성 향상에 전략적 초점을 맞추어야 합니다. 왜냐하면 이러한 분야는 이미 전동 킥보드나 대중교통이 장악하고 있기 때문입니다.
부문 분석
2025년, 전동 자전거는 유럽 시장 점유율의 50.17%를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 9.56%로 성장할 것으로 전망됩니다. 중급 모델에서는 니켈·망간·코발트계 배터리 대신 인산철 리튬 배터리가 점점 더 많이 채택되고 있으며, 에너지 밀도는 약간 낮아지지만 더 긴 수명과 저렴한 비용을 실현하고 있습니다. 두 번째로 큰 카테고리인 로드 바이크와 시티 바이크는 포장 도로에서의 속도와 효율성을 중시하는 통근자를 대상으로 합니다. 한편, 산악자전거와 전지형 모델은 알프스 지역이나 북유럽의 레저 이용자를 대상으로 합니다. 도로 주행과 오프로드 주행 기능을 겸비한 하이브리드 자전거는 한때 다목적 이용자들 사이에서 인기가 있었습니다. 그러나 전동 자전거의 모터 덕분에 더 이상 타협할 필요가 없어지면서, 그 시장 점유율은 하락하고 있습니다. 라이더들은 현재 전용 프레임을 선택하고 페달 어시스트를 활용하여 다양한 지형에 대응할 수 있게 되었습니다. 카고 바이크나 리컴번트 모델은 여전히 틈새 시장이지만, 특히 도시 물류 분야에서 급속히 성장하고 있습니다.
전동 자전거가 계속해서 시장을 장악하는 가운데, 모터나 배터리를 통합할 능력이 없는 기존 자전거 제조업체들은 이익률 압박에 직면해 있습니다. 보쉬나 시마노와 같은 기업들은 수직 통합을 실현함으로써, 부품 공급업체들이 이전에는 프레임 제조업체에 귀속되었던 부가가치를 획득할 수 있게 되었습니다. 이러한 추세로 인해 캐니언이나 스페셜라이즈드와 같은 브랜드들은 독자적인 전자 장치를 개발할 것인지, 아니면 상품화(commoditization)에 직면할 것인지의 선택에 놓여 있습니다. 직장에 충전소 설치를 의무화하는 EU의 ‘대체 연료 인프라 규정’은 전기 자전거 보급에 있어 큰 장벽을 제거하고 있습니다. 이 정책은 선견지명 있는 접근 방식을 강조할 뿐만 아니라, 기존 시장 역학을 뒤집어 정책이 소비자 수요를 선제적으로 이끌어가게 하는 상황을 만들어내고 있습니다.
2025년 시점에서 일반 디자인의 자전거가 시장의 83.35%를 차지했습니다. 그러나 접이식 자전거는 급속한 성장을 이루고 있으며, 2026-2031년 연평균 성장률(CAGR) 10.21%가 예상되어 가장 빠르게 성장하는 부문이 되었습니다. 2024년에 출시된 브롬프턴의 ‘G 라인’은 접이식 모델에 대한 인식이 변화하고 있음을 여실히 보여줍니다. 20인치 휠, 8단 변속, 유압식 디스크 브레이크를 갖춘 이 자전거들은 더 이상 단순한 실용적인 이동 수단이 아니라, 성능 면에서도 경쟁할 수 있는 존재가 되었습니다. 마찬가지로, 무게 15.6kg의 경량 티타늄 프레임을 탑재한 ‘일렉트릭 P 라인’은 UL2849 인증을 획득하기 위해 8년에 걸친 사내 연구 개발을 거쳐 완성되었습니다. 이 성과는 안전 기준의 엄격화를 반영하며, 저비용 경쟁사들에게 진입 장벽이 높아지고 있음을 시사합니다. 접이식 자전거는 전철에서 사무실로, 혹은 자동차에서 트레일로 갈아타는 등 여러 교통 수단을 조합한 통근에 특히 효과적입니다. 바로 이러한 장점 덕분에 런던, 파리, 베를린과 같은 인구 밀집 도시에서 대폭적인 보급 확대가 이루어지고 있습니다. 이러한 도시에서는 광범위한 대중교통망이 갖춰져 있음에도 불구하고, 종종 ‘라스트 마일’의 공백이 발생하기 때문입니다.
기존 디자인은 뛰어난 승차감, 부품의 호환성, 그리고 높은 재판매 가치 덕분에 여전히 주류 지위를 유지하고 있습니다. 애호가나 장거리 통근자들은 휴대성보다 프레임의 강성이나 휠 크기를 더 중요시하기 때문에 이에 따라 기존 지오메트리에 대한 수요가 지속되고 있습니다. 중요한 점은 접이식 자전거가 기존 모델을 대체하는 것이 아니라, 오히려 병행하는 카테고리를 확립해 가고 있다는 것입니다. 이는 자전거와 대중교통을 직접 경쟁시키는 것이 아니라, 이를 조합하여 이용하는 도시 지역 비즈니스맨들의 요구에 부응하고 있습니다. 제조업체들은 접이식 자전거를 만능 해결책으로 포지셔닝하는 것을 피하고, 대신 특정 통근자층을 타겟으로 한 세심한 마케팅 및 유통 전략에 주력해야 합니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the Europe bicycle market size stands at USD 33.37 billion in 2026 and is projected to reach USD 50.38 billion by 2031, registering an 8.59% CAGR over the forecast period.
This report is Segmented by Product Type (Road/City, Mountain/All-Terrain, Hybrid, E-Bicycle, and Other Types), Design (Regular and Folding), End-User (Men, Women, and Children), Distribution Channel (Offline Retail Stores and Online Retail Stores), and Geography (United Kingdom, Germany, France, Italy, Spain, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units)
Europe Bicycle Market Trends and Insights
Urban congestion drives commuter bicycle adoption
European cities are addressing traffic saturation by redefining first-mile and last-mile mobility economics. Paris allocated EUR 250 million (USD 272 million) between 2021 and 2026 to develop 1,400 kilometers of bike lanes. This shift reflects municipalities' focus on induced demand, favoring cargo e-bikes and speed pedelecs over leisure models. Increasing urban density and rising fuel costs position bicycles as a cost-efficient alternative. E-bikes, in particular, extend commuting distances and attract professionals seeking flexible, low-emission travel options. Policies such as the European Union's Sustainable Urban Mobility Plans and national subsidies are integrating cycling into public transit systems, enhancing first and last-mile connectivity while reducing car dependency. In 2024, 75% of the European Union's population resides in cities, according to the World Bank, intensifying urban congestion . This demographic trend increases daily mobility needs, driving the adoption of bikes and e-bikes as efficient solutions for navigating crowded urban areas and minimizing travel times.
Health and fitness awareness fuels recreational cycling
In 2024, Sport England reported that 7,169,700 individuals in England engaged in cycling, highlighting a significant shift where cycling has evolved from being merely a mode of transportation to becoming a core component of wellness and fitness routines. This transformation has been largely driven by the growing emphasis on health and well-being in the post-pandemic era. As a result, fitness-focused consumers are increasingly seeking high-end features, such as lightweight carbon frames for enhanced performance, electronic shifting systems for smoother gear transitions, and integrated power meters for accurate performance monitoring, over prioritizing affordability. This growing demand for premium products allows manufacturers to maintain strong profit margins, even as overall sales volumes begin to stabilize. Moreover, this consumer segment exhibits lower price sensitivity, offering manufacturers a degree of insulation against policy changes, such as France's decision to terminate its bike bonus subsidy in February 2025.
Alternative transportation options constrain bicycle market share
Urban mobility budgets are becoming increasingly fragmented due to the growing popularity of e-scooters and the expansion of rapid transit networks. Shared e-scooters are replacing not only cycling trips and walking but also public transport journeys. This highlights that micro-mobility options are competing more directly with bicycles than with cars. In the Netherlands, the prohibition of e-scooters on public roads protects its cycling market. Conversely, Spain and France allow e-scooters, which intensifies direct competition. In Italy, the strong motorcycle culture adds another layer of complexity: in cities like Rome and Milan, motorcycles remain popular for their weather protection and speed, even with congestion charges, limiting bicycle adoption. For bicycle manufacturers, the strategic focus should be on enhancing utility, such as cargo capacity and weather resistance, rather than prioritizing speed or convenience, as e-scooters and transit options already dominate those areas.
Other drivers and restraints analyzed in the detailed report include:
- Government sustainable transportation policies accelerate market growth
- Environmental consciousness and sustainability goals drive adoption
- Elevated e-bicycle prices limit mass-market penetration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, e-bicycles accounted for 50.17% of the European market share and are expected to grow at a 9.56% CAGR through 2031. Mid-tier models are increasingly using lithium-iron-phosphate batteries instead of nickel-manganese-cobalt chemistries, offering a longer cycle life and lower costs, though with a slight reduction in energy density. The second-largest category, road and city bicycles, serves commuters who value speed and efficiency on paved roads. On the other hand, mountain and all-terrain models cater to recreational users in the Alpine and Nordic regions. Hybrid bicycles, which combine road and off-road features, were once popular among versatile riders. However, their market share is declining as e-bike motors remove the need for compromise. Riders can now choose specialized frames and rely on pedal assistance to handle diverse terrains. While cargo and recumbent models remain niche, they are growing rapidly, particularly in urban logistics.
As e-bicycles continue to dominate, traditional bicycle manufacturers without motor and battery integration capabilities are experiencing compressed margins. Companies like Bosch and Shimano demonstrate vertical integration, allowing component suppliers to capture value that previously belonged to frame builders. This trend is pressuring brands such as Canyon and Specialized to either develop proprietary electronics or face commoditization. The EU's Alternative Fuels Infrastructure Regulation, which requires workplace charging points, is removing a major barrier to e-bike adoption. This policy not only highlights a forward-thinking approach but also reverses traditional market dynamics, with policy now outpacing consumer demand.
In 2025, regular-design bicycles accounted for 83.35% of the market. However, folding variants are experiencing rapid growth, with a 10.21% CAGR projected for 2026-2031, making them the fastest-growing segment. Brompton's G Line, launched in 2024, highlights the evolving perception of folding models. Featuring 20-inch wheels, 8-speed gearing, and hydraulic disc brakes, these bicycles are now competing on performance rather than being seen solely as utilitarian. Similarly, the Electric P Line, equipped with a lightweight titanium frame weighing 15.6 kilograms, underwent 8 years of in-house research and development to achieve UL2849 certification. This achievement reflects stricter safety standards, which are raising entry barriers for low-cost competitors. Folding bicycles are particularly effective for intermodal commuting, such as transitioning from train to office or car to trail. This advantage explains their significant growth in densely populated cities like London, Paris, and Berlin, where extensive public transit systems often leave last-mile gaps.
Regular designs maintain their dominance due to superior ride quality, component compatibility, and higher resale value. Enthusiasts and long-distance commuters prioritize frame stiffness and wheel size over portability, ensuring continued demand for traditional geometries. The key insight is that folding bicycles are not replacing regular models but are instead establishing a parallel category. They cater to urban professionals who integrate cycling with public transit rather than competing directly. Manufacturers should avoid positioning folding bikes as universal solutions and instead focus on targeting specific commuter profiles with tailored marketing and distribution strategies.
Complete Report Scope:
- By Product Type
- Road/City
- Mountain/All-Terrain
- Hybrid
- E-Bicycle
- Other Types
- By Design
- Regular
- Folding
- By End-User
- Men
- Women
- Children
- By Distribution Channel
- Offline Retail Stores
- Online Retail Stores
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Sweden
- Belgium
- Poland
- Netherlands
- Rest of Europe
List of Companies Covered in this Report:
- Accell Group NV
- Trek Bicycle Corporation
- Pon Holdings BV
- Giant Manufacturing Co. Ltd
- Scott Sports SA
- Merida Industry Co. Ltd
- Riese and Muller GmbH
- Canyon Bicycles GmbH
- Decathlon SA
- Bosch eBike Systems (Robert Bosch GmbH)
- Shimano Inc.
- VanMoof BV
- Orbea S. Coop.
- KTM Fahrrad GmbH
- myStromer AG
- Bianchi S.p.A.
- Bulls Bikes (ZEG eG)
- Ribble Cycles
- Simplon Fahrrad GmbH
- Specialized Bicycle Components Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing traffic congestion in urban areas is leading to higher adoption of bicycles for daily commuting.
- 4.2.2 Growing awareness of health and fitness is driving a rise in cycling activities.
- 4.2.3 Government efforts to promote sustainable transportation are encouraging bicycle usage.
- 4.2.4 Rising environmental consciousness and sustainability goals are boosting bicycle adoption.
- 4.2.5 Corporate wellness initiatives are fostering greater use of bicycles among employees.
- 4.2.6 Escalating fuel prices are positioning bicycles as an economical mode of transportation.
- 4.3 Market Restraints
- 4.3.1 Alternative transportation options such as motorcycles and rapid transit systems reduce bicycle adoption rates
- 4.3.2 Elevated prices of electric bicycles limit widespread consumer acceptance across regions
- 4.3.3 Proliferation of fake bicycle products negatively impacts market expansion
- 4.3.4 Inadequate road infrastructure in rural regions affects bicycle riding experience
- 4.4 Consumer Behaviour Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE AND VOLUME)
- 5.1 By Product Type
- 5.1.1 Road/City
- 5.1.2 Mountain/All-Terrain
- 5.1.3 Hybrid
- 5.1.4 E-Bicycle
- 5.1.5 Other Types
- 5.2 By Design
- 5.2.1 Regular
- 5.2.2 Folding
- 5.3 By End-User
- 5.3.1 Men
- 5.3.2 Women
- 5.3.3 Children
- 5.4 By Distribution Channel
- 5.4.1 Offline Retail Stores
- 5.4.2 Online Retail Stores
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Russia
- 5.5.7 Sweden
- 5.5.8 Belgium
- 5.5.9 Poland
- 5.5.10 Netherlands
- 5.5.11 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accell Group NV
- 6.4.2 Trek Bicycle Corporation
- 6.4.3 Pon Holdings BV
- 6.4.4 Giant Manufacturing Co. Ltd
- 6.4.5 Scott Sports SA
- 6.4.6 Merida Industry Co. Ltd
- 6.4.7 Riese and Muller GmbH
- 6.4.8 Canyon Bicycles GmbH
- 6.4.9 Decathlon SA
- 6.4.10 Bosch eBike Systems (Robert Bosch GmbH)
- 6.4.11 Shimano Inc.
- 6.4.12 VanMoof BV
- 6.4.13 Orbea S. Coop.
- 6.4.14 KTM Fahrrad GmbH
- 6.4.15 myStromer AG
- 6.4.16 Bianchi S.p.A.
- 6.4.17 Bulls Bikes (ZEG eG)
- 6.4.18 Ribble Cycles
- 6.4.19 Simplon Fahrrad GmbH
- 6.4.20 Specialized Bicycle Components Inc.