|
시장보고서
상품코드
2123295
비냉각 적외선 이미징 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Uncooled Infrared Imaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 비냉각 적외선 이미징 시장 규모는 2025년 47억 5,000만 달러에서 2026년에는 51억 4,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 8.21%로 성장을 지속하여, 2031년에는 76억 3,000만 달러에 이를 것으로 예측됩니다.
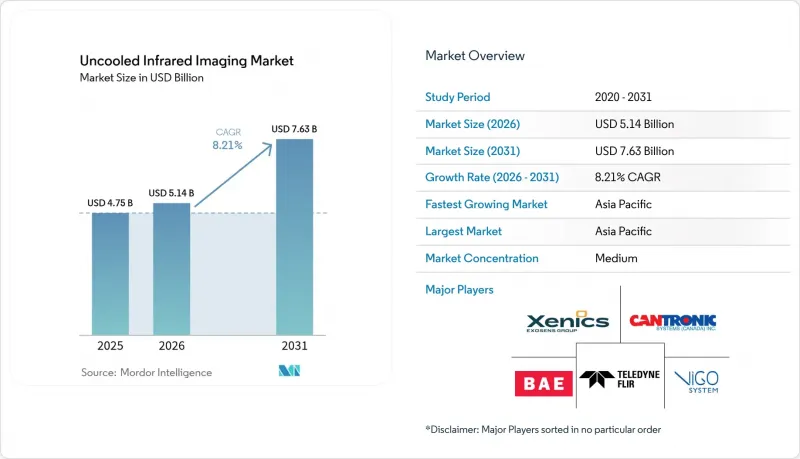
본 보고서는 용도별(자동차, 군 및 방위, 산업 및 제조, 기타), 검출기 기술별(바나듐 산화물 마이크로볼로미터, 비정질 실리콘, 기타),스펙트럼 대역별(장파장 적외선, 중파장 적외선, 기타), 제품 유형별(휴대용 카메라, 고정식 카메라, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 비냉각 적외선 이미징 시장 동향 및 인사이트
자동차용 ADAS 및 야간 투시 시스템에서의 채택 확대
야간에도 보행자 감지가 가능한 자동 긴급 제동 장치를 의무화하는 미국 도로교통안전국(NHTSA)의 신규 규정이 시행될 예정인 만큼, 열화상 카메라는 단순한 고급 옵션에서 주류 안전 장비로 그 위상이 변화하고 있습니다. Valeo와 Teledyne FLIR는 2024년에 자동차 안전 무결성 수준 B(SIL B)에 대한 첫 계약을 수주하며, 양산 모델의 양산 준비가 완료되었음을 입증했습니다. 레이더는 잡음 속에서 생물을 식별하는 데 어려움을 겪고, 라이다(LiDAR)는 우천 시 성능이 저하되며, 가시광선 센서는 저조도 환경에서는 작동하지 않지만, 열화상 기술은 100미터를 넘는 거리에서도 이러한 과제를 해결합니다. 분석가들은 현재 마이크로볼로미터의 연간 출하 대수가 2024년 200만 대 미만에서 2030년까지 1,600만 대를 넘어설 것으로 예측하고 있으며, 이러한 규모 확대로 인해 비냉각 적외선 이미징 시장의 다이 비용은 한 자릿수 달러대로 하락할 전망입니다. 마그나(Magna)는 이미 자사의 운전자 지원 시스템에 120만 대 이상의 열화상 시스템을 도입했으며, 이는 각 OEM 업체들의 신뢰가 높아지고 있음을 보여줍니다.
산업용 예측 유지보수 및 검사에 대한 수요 증가
반도체 팹, 화학 플랜트, 발전소에서 예기치 않은 가동 중단은 시간당 5만 달러 이상의 비용을 발생시키기 때문에 실시간 열화상 검사의 비즈니스적 타당성이 더욱 높아지고 있습니다. 5,000달러 미만의 비냉각식 핸드헬드 카메라를 사용하면, 기술자는 1교대당 수백 개의 자산을 스캔하여 고장이 발생하기 몇 주 전에 핫스팟을 식별할 수 있습니다. 센서에 내장된 엣지 추론 모듈이 장치에서 컨볼루션 네트워크 분석을 수행함으로써 지연 및 대역폭의 장벽을 해소합니다. 전기차 배터리 생산 라인에서는 열화상 어레이를 활용하여 폭주 현상이 발생하기 전에 셀 적층 결함을 감지하고, 전체 생산 배치를 보호하고 있습니다. 또한, ISO 50001 에너지 효율 감사를 통해 건물 관리자가 온도 지도를 개보수 우선순위에 반영하여 운영 비용을 절감함으로써, 제품 구매가 더욱 촉진되고 있습니다.
냉각식 적외선 검출기와 비교한 성능상의 제약
50-100 mK에 달하는 잡음 등가 온도 차이는 장거리 감시, 정밀 유도탄 및 조사용 분광법과 같은 분야에서의 활용을 제한하고 있습니다. 이러한 분야에서는 여전히 20 mK 미만의 성능을 발휘할 수 있는 냉각식 중파장 어레이가 지정되고 있습니다. 비냉각의 경우, 열 시간 상수에 의해 프레임 속도는 60 Hz 부근이 상한이 되며, 탄도 이미징에 필요한 킬로헤르츠급 속도에 훨씬 미치지 못합니다. 따라서 군용 저격 시스템이나 터빈 진단 분야에서는 여전히 냉각 기술이 계약 대상으로 지정되고 있어, 비용이나 전력 소비 측면에서 이점이 있음에도 불구하고 비냉각의 보급에는 한계가 있습니다.
부문 분석
보안 및 감시 분야는 그림자나 헤드라이트로 인한 오경보를 줄여주는 주변 경비 시스템에 힘입어 2025년 매출의 34.10%를 차지했습니다. 대조적으로, 자동차 용도는 규모는 작지만 야간에 보행자, 자전거 이용자, 대형 동물을 감지하도록 의무화하는 미국 브레이크 규제에 힘입어 2031년까지 연평균 10.05%의 성장률이 예상되며, 이는 모든 최종 용도 중 가장 빠른 성장률입니다. 이 규제로 인해 비냉각 적외선 이미징 시장의 성장 기회는 고급차 브랜드에 그치지 않고 양산차 플랫폼으로까지 확대되고 있습니다.
산업용 유지보수 분야에서는 개폐 장치 및 회전 기계의 열화상 스캔이 수요를 견인하고 있는 반면, 소비자용 전자기기 분야에서는 200달러 미만의 스마트폰용 핵심 제품이 전문가와 프로슈머의 경계를 모호하게 함으로써 시장을 확대되고 있습니다. 매핑 및 측량 분야에서는 작물 생육 상황이나 송전선 점검을 위해 드론에 비냉각 카메라가 탑재되고 있지만, 여전히 틈새 시장에 머물러 있습니다. 의료 분야의 발열 검진 수요는 팬데믹 이후 정상화되어 병원이나 교통 거점에서 안정적인 기반을 유지하고 있습니다.
2025년에는 바나듐 산화물 설계가 매출의 48.60%를 차지했습니다. 이는 감도를 향상시킨 국방 예산의 영향 때문이지만, 팹이 표준 CMOS 장비를 활용함에 따라 비정질 실리콘은 연평균 성장률(CAGR) 9.62%로 시장 점유율을 확대되고 있습니다. 비정질 실리콘의 공정 친화성으로 인해 다이당 비용이 대폭 절감되고, 판독 회로와의 모노리식 집적이 간소화됩니다. 이는 자동차 분야의 규모의 경제에 있어 매우 중요합니다. 자동차 생산 대수가 방위 수요를 훨씬 능가하기 때문에 비냉각 적외선 이미징 시장에서 바나듐 산화물의 점유율은 하락할 가능성이 있으며, 설비 투자는 실리콘 제품 라인으로 이동할 것입니다.
서모파일 및 피에조일렉트릭 어레이는 해상도가 부차적인 요소인 동작 감지 분야에서 한 자릿수 초반의 낮은 점유율을 차지하고 있습니다. 신흥 양자점 프로토타입은 상온에서 단파장 영역을 커버할 것으로 기대되지만, 제조상의 과제로 인해 여전히 연구실 단계에 머물러 있습니다. 2024년 10월 Lynred사가 New Imaging Technologies사를 인수한 것은 장파장 분야의 틈새 시장이 성숙해가는 가운데 공급업체들이 단파장 자산을 통해 리스크 헤지를 꾀하려는 움직임을 여실히 보여주고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 41.10%를 차지하며, 2031년까지 연평균 성장률(CAGR) 11.29%를 나타낼 것으로 전망됩니다. 이는 비냉각 적외선 이미징 시장 평균을 크게 웃도는 수치이며, 중국 공급업체들이 검출기 제조, 웨이퍼 가공, 카메라 조립을 일원화하고 있기 때문입니다. 수직 통합을 통해 리드 타임이 8주로 단축되고, 유럽 및 미국 기업의 견적 가격보다 최대 40% 낮은 가격을 제시함으로써 동남아시아 전역에서 주변 경비 및 산업용 분야의 입찰을 수주하고 있습니다. 인도의 ‘현지 조달률 60%’ 조항에 따라 국방 관련 수주가 합작 기업으로 유입되면서, 국내 팹에 대한 투자가 촉진되고 공급 탄력성이 높아지고 있습니다.
북미는 2025년 매출의 약 29.80%를 차지했습니다. ‘스트라이커’ NBCRV 업그레이드, 병사용 조준기, 대드론용 페이로드 등의 방위 프로그램이 계속해서 수요의 주축을 이루고 있지만, 자동차 분야에서는 야간 시인성 제동 장치의 의무화를 앞두고 실증 시험이 본격화되고 있습니다. 그러나 규제 최종안이 확정되기를 기다리고 있는 탓에 상용화 진전이 더뎌지고 있으며, 성장률은 아시아에 뒤처지고 있습니다. 유럽은 NATO의 GDP 대비 2% 국방비 목표와 EU의 건물 감사 의무화에 힘입어 매출의 약 15.20%를 차지했습니다. 세계 최고 수준의 연구개발 체제를 갖추고 있음에도 불구하고, 조달 체제의 세분화와 엄격한 수출 규제가 성장을 저해하고 있습니다.
중동 및 아프리카는 파이프라인과 공항에 AI 탑재 열화상 카메라를 도입하는 걸프 지역의 인프라 프로젝트를 견인력으로 삼아 2025년 매출의 약 8.10%를 차지했습니다. 정치적 리스크와 환율 변동이 다년간의 전망을 하향 조정하고 있지만, 중요 인프라 보호가 기초적인 지출을 뒷받침하고 있습니다. 남미의 5.80% 점유율은 브라질과 칠레의 광업, 유틸리티, 산불 감시 등의 활용 사례에서 비롯되었습니다. 수입 관세와 인센티브 부족이 광범위한 보급을 저해하고 있지만, 지역적 에너지 전환 프로젝트가 새로운 수요를 창출할 가능성이 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the uncooled infrared imaging market size is expected to grow from USD 4.75 billion in 2025 to USD 5.14 billion in 2026 and is forecast to reach USD 7.63 billion by 2031 at 8.21% CAGR over 2026-2031.
This report is Segmented by Application (Automotive, Military and Defense, Industrial and Manufacturing, and More), Detector Technology (Vanadium Oxide Microbolometers, Amorphous Silicon, and More), Spectral Band (Long-Wave Infrared, Mid-Wave Infrared, and More), Product Type (Handheld Cameras, Fixed-Mount Cameras, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Uncooled Infrared Imaging Market Trends and Insights
Rising Adoption in Automotive ADAS and Night Vision Systems
Pending National Highway Traffic Safety Administration rules that mandate automatic emergency braking capable of night-time pedestrian detection are propelling thermal cameras from luxury options to mainstream safety equipment. Valeo and Teledyne FLIR secured the first Automotive Safety Integrity Level B contract in 2024, validating production readiness for high-volume models. Radar struggles to classify living objects in clutter, lidar performance degrades in rain, and visible sensors fail in low light; thermal imaging closes these gaps at ranges beyond 100 m. Analysts now forecast annual microbolometer volumes exceeding 16 million units by 2030 versus fewer than 2 million in 2024, a scale shift that drives the uncooled infrared imaging market toward single-digit dollar die costs. Magna has already deployed more than 1.2 million thermal systems across its driver-assistance suite, signaling growing OEM confidence.
Growing Demand for Industrial Predictive Maintenance and Inspection
Unplanned downtime in semiconductor fabs, chemical plants, and power stations costs upwards of USD 50,000 per hour, sharpening the business case for real-time thermal inspection. Uncooled handheld cameras priced below USD 5,000 let technicians scan hundreds of assets per shift, flagging hot spots weeks before failures emerge. Edge-inferencing modules embedded within the sensor conduct convolutional-network analysis on-device, removing latency and bandwidth barriers. Electric-vehicle battery lines rely on thermal arrays to catch cell-stacking defects before runaway events, protecting entire production batches. ISO 50001 energy-efficiency audits further stimulate purchases as building managers translate temperature maps into retrofit priorities that cut operating costs.
Performance Limitations Compared to Cooled Infrared Detectors
Noise-equivalent temperature differences of 50-100 mK limit long-range surveillance, precision munitions, and research spectroscopy, domains that still specify cooled mid-wave arrays capable of sub-20 mK performance. Uncooled frame-rates top out near 60 Hz due to thermal time constants, well below the kilohertz speeds needed for ballistic imaging. Military sniper systems and turbine diagnostics therefore keep cooled technology on contract, capping the ceiling for uncooled penetration despite its cost and power benefits.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Defense and Security Expenditure on Thermal Imaging
- Decreasing Cost of Microbolometer Sensors
- Export Control Regulations on Infrared Components
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Security and surveillance retained 34.10% of 2025 revenue, fueled by perimeter systems that cut false alarms from shadows and headlights. In contrast, automotive applications, though smaller, are forecast to grow at 10.05% through 2031, the fastest among all end-uses, driven by proposed U.S. braking rules that require nighttime detection of pedestrians, cyclists, and large animals. This regulation anchors the uncooled infrared imaging market size opportunity within mass-production vehicle platforms, moving beyond premium marques.
Industrial maintenance gains from thermal scans of switchgear and rotating machinery, while consumer electronics expand via sub-USD 200 smartphone cores that blur professional and prosumer boundaries. Mapping and surveying segments attach uncooled cameras to drones for crop health and power-line inspection, yet remain niche. Healthcare fever-screening demand has normalized post-pandemic, leaving a stable base in hospitals and transit hubs.
Vanadium-oxide designs captured 48.60% revenue in 2025, a legacy of defense funding that honed sensitivity, but amorphous silicon is climbing at 9.62% CAGR as fabs leverage standard CMOS tooling. Amorphous silicon's process affinity slashes per-die costs and simplifies monolithic integration with read-out circuits, critical for automotive economies of scale. The uncooled infrared imaging market share for vanadium-oxide may erode as car volumes dwarf defense demand, tilting capital investment toward silicon lines.
Thermopile and pyroelectric arrays hold low single-digit slices for motion sensing, where resolution is secondary. Emerging quantum-dot prototypes promise short-wave coverage at ambient temperature, yet manufacturability hurdles keep them in labs. Lynred's October 2024 purchase of New Imaging Technologies highlights supplier moves to hedge with short-wave assets as long-wave niches mature
Complete Report Scope:
- By Application
- Automotive
- Military and Defense
- Industrial and Manufacturing
- Security and Surveillance
- Consumer Electronics
- Mapping and Surveying
- Healthcare
- By Detector Technology
- Vanadium Oxide Microbolometers
- Amorphous Silicon Microbolometers
- Thermopile Arrays
- Pyroelectric Arrays
- Other Uncooled Detectors
- By Spectral Band
- Long-Wave Infrared (LWIR)
- Mid-Wave Infrared (MWIR)
- Short-Wave Infrared (SWIR)
- Far Infrared (FIR)
- By Product Type
- Handheld Cameras
- Fixed-Mount Cameras
- Pan-Tilt-Zoom Cameras
- Vehicle-Mounted Sensors
- Smartphone Modules
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Kenya
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific generated 41.10% of 2025 revenue and is projected to post an 11.29% CAGR to 2031, well above the uncooled infrared imaging market average, as Chinese vendors integrate detector growth, wafer processing, and camera assembly under one roof . Vertical integration trims lead times to eight weeks and undercuts Western quotes by up to 40%, winning perimeter and industrial bids across Southeast Asia. India's 60% local-content clause reroutes defense orders to joint ventures, catalyzing domestic fab investment and broadening supply resilience.
North America contributed roughly 29.80% of 2025 revenue. Defense programs such as Stryker NBCRV upgrades, soldier-borne sights, and counter-drone payloads continue to anchor demand, while automotive pilots ramp ahead of night-vision brake mandates. Growth, however, lags Asia as commercial uptake waits for the final regulatory text. Europe secured about 15.20% revenue, buoyed by NATO's 2% GDP defense pledge and EU building-audit mandates. Fragmented procurement and strict export controls temper growth despite world-class R&D.
The Middle East and Africa combined for around 8.10% of 2025 revenue, led by Gulf infrastructure projects that deploy AI-enabled thermal cameras along pipelines and airports. Political risk and currency volatility dampen multi-year forecasts, yet critical-infrastructure protection sustains baseline spending. South America's 5.80% share stems from mining, utility, and wildfire-monitoring use cases in Brazil and Chile; import tariffs and limited incentives restrain broader adoption, yet regional energy-transition projects may unlock incremental demand.
- Teledyne FLIR LLC
- Xenics NV
- Cantronic Systems Inc.
- BAE Systems plc
- Teledyne DALSA Inc.
- Zhejiang ULIRVISION Technology Co., Ltd.
- VIGO System S.A.
- Axis Communications AB
- Lynred USA Inc.
- Seek Thermal Inc.
- Wuhan Guide Infrared Co., Ltd.
- Zhejiang Dali Technology Co., Ltd.
- Yantai IRay Technology Co., Ltd.
- Raytheon Technologies Corporation
- L3Harris Technologies, Inc.
- Leonardo DRS, Inc.
- Fluke Corporation
- Opgal Optronic Industries Ltd.
- Honeywell International Inc.
- Excelitas Technologies Corp.
- InfraTec GmbH Infrarotsensorik und Messtechnik
- Hamamatsu Photonics K.K.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Adoption in Automotive ADAS and Night Vision Systems
- 4.2.2 Growing Demand for Industrial Predictive Maintenance and Inspection
- 4.2.3 Increasing Defense and Security Expenditure on Thermal Imaging
- 4.2.4 Decreasing Cost of Microbolometer Sensors
- 4.2.5 Emergence of Smartphone Integrated Thermal Cameras
- 4.2.6 Wafer-Level Packaging Advancements Reducing Pixel Pitch Below 10 µm
- 4.3 Market Restraints
- 4.3.1 Performance Limitations Compared to Cooled Infrared Detectors
- 4.3.2 Export Control Regulations on Infrared Components
- 4.3.3 Price Sensitivity in Mass-Market Consumer Applications
- 4.3.4 Germanium Supply Constraints Impacting Infrared Optics
- 4.4 Industry Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Automotive
- 5.1.2 Military and Defense
- 5.1.3 Industrial and Manufacturing
- 5.1.4 Security and Surveillance
- 5.1.5 Consumer Electronics
- 5.1.6 Mapping and Surveying
- 5.1.7 Healthcare
- 5.2 By Detector Technology
- 5.2.1 Vanadium Oxide Microbolometers
- 5.2.2 Amorphous Silicon Microbolometers
- 5.2.3 Thermopile Arrays
- 5.2.4 Pyroelectric Arrays
- 5.2.5 Other Uncooled Detectors
- 5.3 By Spectral Band
- 5.3.1 Long-Wave Infrared (LWIR)
- 5.3.2 Mid-Wave Infrared (MWIR)
- 5.3.3 Short-Wave Infrared (SWIR)
- 5.3.4 Far Infrared (FIR)
- 5.4 By Product Type
- 5.4.1 Handheld Cameras
- 5.4.2 Fixed-Mount Cameras
- 5.4.3 Pan-Tilt-Zoom Cameras
- 5.4.4 Vehicle-Mounted Sensors
- 5.4.5 Smartphone Modules
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Kenya
- 5.5.5.2.3 Nigeria
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Teledyne FLIR LLC
- 6.4.2 Xenics NV
- 6.4.3 Cantronic Systems Inc.
- 6.4.4 BAE Systems plc
- 6.4.5 Teledyne DALSA Inc.
- 6.4.6 Zhejiang ULIRVISION Technology Co., Ltd.
- 6.4.7 VIGO System S.A.
- 6.4.8 Axis Communications AB
- 6.4.9 Lynred USA Inc.
- 6.4.10 Seek Thermal Inc.
- 6.4.11 Wuhan Guide Infrared Co., Ltd.
- 6.4.12 Zhejiang Dali Technology Co., Ltd.
- 6.4.13 Yantai IRay Technology Co., Ltd.
- 6.4.14 Raytheon Technologies Corporation
- 6.4.15 L3Harris Technologies, Inc.
- 6.4.16 Leonardo DRS, Inc.
- 6.4.17 Fluke Corporation
- 6.4.18 Opgal Optronic Industries Ltd.
- 6.4.19 Honeywell International Inc.
- 6.4.20 Excelitas Technologies Corp.
- 6.4.21 InfraTec GmbH Infrarotsensorik und Messtechnik
- 6.4.22 Hamamatsu Photonics K.K.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment