

|
시장보고서
상품코드
2123324
헤드업 디스플레이(HUD) 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Head-Up Display - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
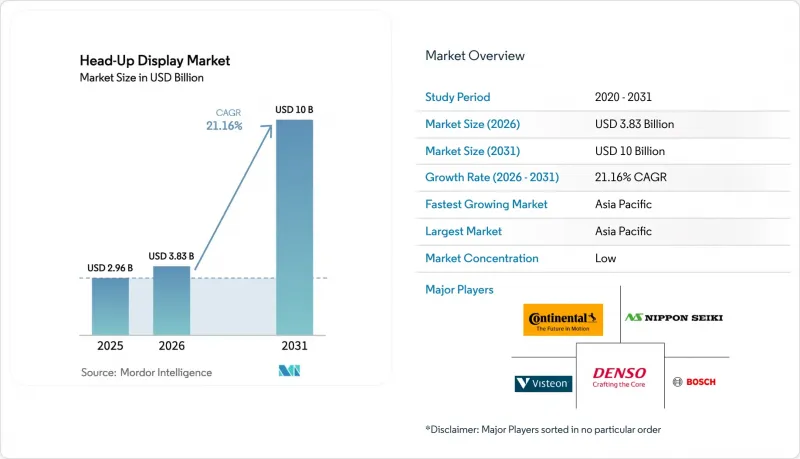
에 의하면, 헤드업 디스플레이(HUD) 시장 규모는 2025년 29억 6,000만 달러에서 2026년에는 38억 3,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 21.16%로 성장을 지속하여, 2031년까지 100억 달러에 이를 것으로 예측됩니다. 이것은 이 콕핏 기술이 급격한 성장 곡선을 그리고 있는 것을 나타내고 있습니다.
본 보고서는 HUD의 유형(앞유리식 HUD, 컴바이너식 HUD, 증강현실(AR) HUD 및 기존 HUD), 표시 형식(2D HUD 및 3D HUD), 차량 등급(상용차 및 승용차), 판매 채널(OEM 순정 장착 및 애프터마켓),용도(자동차, 군용 및 민간 항공, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 헤드업 디스플레이 시장 동향 및 인사이트
중가대 차량에서의 증강현실(AR) HUD 도입 확대
중국 및 유럽의 자동차 제조업체들은 AR 프로젝션 기술을 고급차 라인에서 3만-5만 달러 가격대의 차량으로 확대하고 있어, 헤드업 디스플레이 시장에서 구매자의 기대치를 재정의하고 있습니다. 웨이브 가이드 광학 시스템을 통해 프로젝터의 부피가 1리터 미만으로 축소되어 대시보드 공간을 확보할 수 있을 뿐만 아니라, 재료비를 300달러 미만으로 낮추는 가격대를 실현함으로써 일반 시장에서의 보급을 촉진하고 있습니다. 2025년 6월에 출시될 Xpeng의 G7은 화웨이(Huawei)가 제작한 AR-HUD를 채택하여 12,000니트 이상의 밝기로 87인치 가상 이미지를 투영합니다. 이는 중형 크로스오버 차량에서도 조기에 프리미엄 사양을 구현할 수 있음을 보여줍니다. 현대자동차와 자이스는 주력 모델인 ‘투손’ 및 ‘산타페’를 위해 전면 유리를 전체적으로 덮는 홀로그래픽 HUD를 개발 중이며, 2027년 양산을 목표로 하고 있습니다. 이는 기술의 흐름이 앞으로도 양산 플랫폼으로 계속 이어질 것임을 시사합니다. 탑재율이 상승함에 따라, 헤드업 디스플레이 시장의 Tier 1 공급업체들은 다양한 가격대의 프로그램 수주를 확보하기 위해 광학 기술의 혁신과 적극적인 비용 절감 조치 간의 균형을 맞추어야 합니다.
운전자 정보 시스템의 장착을 의무화하는 엄격한 안전 규정
유엔 규정 제171호에서는 시선에 맞춘 시각적 경고를 활용하여 운전자의 주의를 환기시키고 운전자의 대응을 확인하도록 규정하고 있으며, 이에 따라 HUD는 레벨 2 및 레벨 3 자율주행 프로그램에서 규정 준수를 가속화하는 요소가 되고 있습니다. 미국에서는 FMVSS 127에 따라 충돌 경고 기호를 좁은 시야 범위 내에 배치해야 할 의무가 있지만, 이는 앞유리에 투영함으로써 자연스럽게 충족되는 요건입니다. 2025년 3월에 발표된 Euro NCAP의 ‘운전자 참여 프로토콜(Driver Engagement Protocol)’에서는 증강현실(AR) 오버레이를 통해 자동화 상태를 표시하는 차량에 높은 평가를 부여하고 있으며, 안전성 점수가 경쟁적인 마케팅 수단이 되고 있습니다. 이러한 규제가 빠르게 도입됨에 따라, 각 OEM 업체들은 HUD 하드웨어를 사후 장착 옵션이 아닌 기본 플랫폼 개발 단계에서 통합해야만 하는 상황에 처해 있습니다. ISO/TS 21957에 따라 휘도, 고스트 이미지, 아이박스 등의 매개변수를 인증할 수 있는 공급업체는 HUD 시장에서 3개 대륙에 걸친 신모델 프로그램에서 우선 공급업체 지위를 확보하고 있습니다.
전면 유리 투사형 AR HUD의 시스템 비용은 여전히 높은 수준을 유지하고 있습니다.
전면 유리 전체 투사에는 홀로그래픽 광학 소자, 레이저 다이오드 어레이, 그리고 운전자의 안구를 지속적으로 추적하는 기능이 필요하며, 이로 인해 부품 원가가 1,000달러를 초과하여 초고급 모델로만 채택이 제한되고 있습니다. 전면 유리 전체에 투영 필름으로 적용되는 BMW의 ‘파노라믹 비전’은 여전히 표준 사양이 아닌 추가 비용이 필요한 옵션으로 제공되고 있으며, 이는 각 OEM 업체들이 이러한 비용을 흡수하는 데 신중한 태도를 보이고 있음을 보여줍니다. 도파관을 채택하는 경우에도 양산용 전면 유리는 엄격한 왜곡 허용 범위를 충족해야 하므로, 이로 인해 유리 조달 비용이 높아지고 검증 일정도 장기화됩니다. 이러한 가격 장벽은 인도에서 특히 심각하여, 2025년 초 ADAS 보급률은 고작 8.3%에 그치고 있으며, 프리미엄 콕핏 기능에 할당할 예산의 여력은 거의 없습니다. 부품 가격이 대폭 하락하기 전까지는 대중차 시장에서 계속해서 전면 유리의 투사 영역을 작게 유지하거나, 콤바이너 방식의 솔루션에 의존하게 될 것입니다.
부문 분석
앞유리 일체형 프로젝션은 각 OEM 업체들이 더 큰 가상 이미지와 깔끔한 대시보드 레이아웃을 선호함에 따라, 2025년 헤드업 디스플레이 시장 매출 점유율의 56.00%를 차지했습니다. 이러한 우위는 앞으로도 지속될 전망이지만, 증강현실(AR) 하위 부문은 2031년까지 연평균 성장률(CAGR) 19.40%를 나타낼 것으로 예측되며, 센서와 연동된 화살표, 위험 구역 테두리 표시, 차선 안내 등이 추가되어 상황 인식 능력이 향상될 것으로 보입니다. 따라서 AR의 점유율이 확대되더라도 전면 유리 장착형 헤드업 디스플레이 시장 규모는 절대값 기준으로 확대될 것이며, 기존 설계와 홀로그래픽 설계 모두에 대한 이중 수요가 발생하게 될 것입니다.
AR HUD에 대한 수요는 BMW가 2025년 말까지 ‘Neue Klasse’ 시리즈의 모든 차량에 3D 오버레이 옵션을 장착할 계획에 힘입어 증가하고 있으며, 이를 통해 프리미엄 인테리어의 사실상의 표준이 확립될 전망입니다. 현재 Tier 1 공급업체들은 도파관 설계 부품 원가를 300달러 미만으로 억제하는 것을 목표로 하고 있어, 이익률을 희생하지 않고도 중급 부문에 도입할 수 있게 되었습니다. 가격에 민감한 지역에서는 커바이너형 애드온이 계속 남아 있겠지만, 각 OEM 업체들이 무선 업데이트가 가능하고 ADAS 센서와 보정이 가능한 통합 솔루션을 추진함에 따라 그 시장 점유율은 점차 축소될 것입니다.
2025년 헤드업 디스플레이(HUD) 시장에서 2차원 디스플레이는 61.50%의 점유율을 유지했으나, 레벨 2 및 레벨 3 자율주행이 확대됨에 따라 3D HUD는 연평균 21.30%의 성장률을 보일 것으로 예측됩니다. 깊이를 구분한 레이어를 통해 배터리 잔량, 속도, 자율주행 모드가 운전자 바로 근처에 표시되는 한편, 방향 지시 화살표나 장애물 박스는 전방 10-20m 위치에 표시되므로 시선 재조정 시간을 단축할 수 있습니다.
BMW의 3D 헤드업 디스플레이는 듀얼 플레인 홀로그래피가 양산 환경에서 어떻게 작동하는지 보여주며, 운전자 및 모니터 카메라와 연동하여 머리 위치의 변화에 따라 영상을 조정합니다. 따라서 공급업체는 광학 기술에 대한 전문 지식과 실시간 시선 추적, GPU 기반 렌더링 기술을 결합해야 합니다. 전기차의 전력 예산 범위 내에서 이를 실현할 수 있는 기업은 향후 신차 적용에서 압도적인 점유율을 확보하며, 예측 기간 동안 3D 헤드업 디스플레이 시장 점유율을 끌어올릴 것입니다.
지역별 분석
아시아태평양은 2025년에 전 세계 매출의 38.90%를 차지하며, 중국의 전기차 생산 붐과 일본의 광전자기기 수출 강세에 힘입어 2031년까지 연평균 성장률(CAGR) 12.30%로 성장할 것으로 전망됩니다. Xpeng, NIO, Li Auto와 같은 현지 브랜드들은 경쟁이 치열해지는 국내 시장에서 차별화를 꾀하기 위해 대형 AR 이미지를 탑재하고 있으며, 이로 인해 가격대가 낮아짐에 따라 기능의 보급이 가속화되고 있습니다. 한국의 디스플레이 생태계는 웨이브 가이드와 마이크로LED를 대규모로 공급하며, 지역 자동차 제조업체의 비용 곡선을 낮추고 있습니다.
북미에서는 고급차 시장의 높은 보급률과 소프트웨어 정의 아키텍처의 조기 도입이 호재로 작용하고 있지만, 중국의 광학 부품에 대한 섹션 301 관세로 인해 입고 비용이 25% 증가함에 따라 유럽 및 동남아시아를 통한 이중 조달이 진행되고 있습니다. 충돌 경고 시각화에 관한 미국 연방 규정에서는 HUD에 적합한 시선 위치에 배치할 것을 의무화하고 있어, 각 OEM 업체들은 통합형 프로젝션으로의 전환을 서두르고 있습니다. 캐나다의 부품 공급업체들은 관세 관련 혼란에도 불구하고 조립 공장의 가동률을 유지하기 위해 이러한 프로그램에 발맞추고 있습니다.
유럽에서는 엄격한 안전 평가 기준과 조종석의 디지털화를 특징으로 삼는 고급 브랜드들이 밀접하게 연결되어 있습니다. 유로 NCAP의 2025년 참여 프로토콜에서는 AR 오버레이가 평가 대상으로 포함되어 있으며, 폭스바겐, 메르세데스-벤츠, BMW 등 각사는 전면 유리에 표시하는 기술 로드맵을 가속화하고 있습니다. 그러나 해당 지역에서는 첨단 광학 기기의 형식 인증 비용 급등 문제에도 직면해 있습니다. 중동 및 아프리카의 신흥 시장에서는 자율주행 셔틀의 운전 지원 수단으로 HUD 도입이 모색되고 있으나, 혹독한 기후 조건과 가격에 대한 민감성으로 인해 현재로서는 보급이 제한적입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 성장 촉진요인
제6장 시장 성장 억제요인
제7장 시장 규모와 성장 예측
제8장 경쟁 구도
제9장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the head-Up display market size is expected to grow from USD 2.96 billion in 2025 to USD 3.83 billion in 2026 and is forecast to reach USD 10 billion by 2031 at 21.16% CAGR over 2026-2031, underscoring a steep expansion curve for this cockpit technology.
This report is Segmented by HUD Type (Windshield-Based HUD, Combiner-Based HUD, Augmented Reality HUD, and Conventional HUD), Dimension Type (2D HUD, and 3D HUD), Vehicle Class (Commercial Vehicles, and Passenger Vehicles), Sales Channel (OEM-Fitted, and Aftermarket), Application (Automotive, Military and Civil Aviation, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Head-Up Display Market Trends and Insights
Rising Integration of Augmented Reality HUDs in Mid-Range Vehicles
Chinese and European automakers are pushing AR projection from luxury lines into vehicles priced between USD 30,000 and USD 50,000, resetting buyer expectations in the head-up display market. Waveguide optics now shrink projector volume to under 1 liter, freeing dashboard space and lowering material cost below the USD 300 price point that unlocks mass-market adoption. Xpeng's G7 launch in June 2025, using Huawei's AR-HUD, projects an 87-inch virtual image at more than 12,000 nits brightness, proof that premium specifications can arrive early in mid-segment crossovers. Hyundai and Zeiss are developing a full-windshield holographic HUD for mainstream Tucson and Santa Fe models, aiming for 2027 production and signaling that the technology curve will continue to bend toward volume platforms. As attachment rates rise, tier-1 suppliers, in the head-up display market, must balance optical innovation with aggressive cost engineering to secure program awards across multiple price tiers.
Stringent Safety Regulations Mandating Driver Information Systems
UN Regulation 171 specifies handover prompts and driver-availability confirmations that benefit from gaze-aligned visual alerts, making HUDs a compliance accelerant in Level 2 and Level 3 automation programs. In the United States, FMVSS 127 requires collision-warning symbols to reside within a tight sight-line envelope, a target naturally met by windshield projection. Euro NCAP's Driver Engagement Protocol, released in March 2025, awards higher ratings to vehicles that display automation status via augmented reality overlays, making safety scoring a competitive marketing lever. These mandates are arriving quickly, forcing OEMs to integrate HUD hardware during base-platform development rather than as an optional afterthought. Suppliers that can certify luminance, ghost-image, and eyebox parameters under ISO/TS 21957 now win preferred-vendor status in new model programs across three continents in HUD market.
Persistent High System Cost for Full-Windshield AR HUDs
Full-windshield projection demands holographic optical elements, laser diode arrays, and continuous driver-eye tracking, driving the bill of materials above USD 1,000 and restricting adoption to ultra-luxury models. BMW's Panoramic Vision, applied as a projection film across the entire windshield, remains an extra-cost option rather than standard equipment, illustrating OEM caution in absorbing these costs. Even with waveguides, production windshields must meet tight distortion limits, raising glass-sourcing expenses and extending validation schedules. The price barrier is especially severe in India, where ADAS penetration was only 8.3% in early 2025, leaving little budget headroom for premium cockpit features. Until component pricing falls sharply, mass-market vehicles will continue to rely on smaller windshield zones or combiner-based solutions.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated Adoption of Electric and Software-Defined Vehicles
- Component Cost Reduction through Waveguide and MicroLED Optics
- Growing Competition from Smart Glasses and Mixed Reality Headsets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Windshield-integrated projection held 56.00% of 2025 revenue share in the head-up display market, as OEMs favored its larger virtual image and cleaner dashboard layout. That dominance will continue, yet the augmented reality subset is forecast to log a 19.40% CAGR through 2031, adding sensor-anchored arrows, hazard framing, and lane cues that elevate situational awareness. The head-up display market size for windshield units will therefore rise in absolute terms even as AR gains mix, creating dual demand streams for both conventional and holographic designs
AR HUD demand is reinforced by BMW's plan to equip every Neue Klasse vehicle with a 3D overlay option by late 2025, setting a de facto standard for premium interiors. Tier-1 suppliers now quote sub-USD 300 bill-of-materials targets for waveguide designs, enabling mid-segment adoption without sacrificing margin. Combiner-type add-ons will linger in price-sensitive geographies, yet their share will erode as OEMs push integrated solutions that can be updated over the air and calibrated to ADAS sensors.
Two-dimensional imaging retained a 61.50% share in 2025 in the head-up display market, yet 3D HUDs are projected to compound at 21.30% annually as Level 2 and Level 3 automation expand. Depth-separated layers present battery charge, speed, and automation mode close to the driver, while turn arrows and obstacle boxes appear 10-20 m ahead, cutting refocus time.
BMW's 3D Head-Up Display demonstrates how dual-plane holography works in production, integrating with driver-monitor cameras to adapt imagery as head position shifts. Suppliers must therefore couple optics expertise with real-time gaze tracking and GPU-based rendering. Those that can do so within EV power budgets will earn an outsized share of upcoming model awards, lifting the head-up display market share for 3D solutions over the forecast window.
Complete Report Scope:
- By HUD Type
- Windshield-Based HUD
- Combiner-Based HUD
- Augmented Reality HUD
- By Dimension Type
- 2D HUD
- 3D HUD
- By Vehicle Class
- Commercial Vehicles
- Passenger Vehicles
- By Sales Channel
- OEM-Fitted
- Aftermarket
- By Application
- Automotive
- Military and Civil Aviation
- Others (Industrial, Wearable, and other Displays)
- Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East
- GCC
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific held 38.90% of global revenue in 2025 and is forecast to grow at a 12.30% CAGR through 2031, buoyed by China's electric-vehicle production boom and Japan's export strength in optoelectronics. Local brands like Xpeng, NIO, and Li Auto embed large AR images to stand out in a hypercompetitive domestic arena, accelerating feature diffusion down the price ladder. South Korea's display ecosystem supplies waveguides and MicroLEDs at scale, compressing cost curves for regional automakers.
North America benefits from high luxury penetration and early software-defined architectures, although Section 301 tariffs on Chinese optics add 25% landed cost, prompting dual sourcing from Europe and Southeast Asia. U.S. federal rules on collision-warning visualization mandate HUD-friendly sight-line placement, nudging OEMs toward integrated projection. Canada's parts suppliers align with these programs to keep assembly plants fully utilized despite tariff turbulence.
Europe marries stringent safety scoring with prestige brands that view cockpit digitalization as a hallmark. Euro NCAP's 2025 engagement protocol rewards AR overlays, pushing Volkswagen, Mercedes-Benz, and BMW to accelerate full-windshield roadmaps. Yet the region also grapples with higher homologation costs for advanced optics. Emerging markets in the Middle East and Africa explore HUD for autonomous shuttle pilots, but harsh climate conditions and price sensitivity keep uptake modest for now.
- Denso Corporation
- Nippon Seiki Co., Ltd.
- Panasonic Automotive Systems
- Visteon Corporation
- Continental AG
- Robert Bosch GmbH
- Valeo SE
- BAE Systems PLC
- Thales Group
- Garmin Ltd.
- Elbit Systems Ltd.
- Pioneer Corporation
- SaaB AB
- Hudway LLC
- Collins Aerospace
- LG Display Co., Ltd.
- Harman International
- WayRay AG
- Envisics Ltd.
- Texas Instruments Incorporated
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 NTRODUCTION
- 1.1 Study Assumptions
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry Supply-Chain Analysis
- 4.3 Porter's Five Forces Analysis
- 4.3.1 Threat of New Entrants
- 4.3.2 Bargaining Power of Buyers
- 4.3.3 Bargaining Power of Suppliers
- 4.3.4 Threat of Substitute Products
- 4.3.5 Intensity of Competitive Rivalry
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
5 MARKET DRIVERS
- 5.1 Rising Integration of Augmented Reality HUDs in Mid-Range Vehicles
- 5.2 Stringent Safety Regulations Mandating Driver Information Systems
- 5.3 Accelerated Adoption of Electric and Software-Defined Vehicles
- 5.4 Component Cost Reduction through Waveguide and MicroLED Optics
- 5.5 Monetization of HUD Software via Subscription-Based Feature Unlocks
- 5.6 Automotive Tier-1 Semiconductor Co-Design Partnerships Shortening HUD Development Cycles
6 MARKET RESTRAINTS
- 6.1 Persistent High System Cost for Full-Windshield AR HUDs
- 6.2 Limited Field of View and Windshield Compatibility Constraints
- 6.3 Tariff-Driven Optics and IC Supply Risks in North America
- 6.4 Growing Competition from Smart Glasses and Mixed Reality Headsets
7 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 7.1 By HUD Type
- 7.1.1 Windshield-Based HUD
- 7.1.2 Combiner-Based HUD
- 7.1.3 Augmented Reality HUD
- 7.2 By Dimension Type
- 7.2.1 2D HUD
- 7.2.2 3D HUD
- 7.3 By Vehicle Class
- 7.3.1 Commercial Vehicles
- 7.3.2 Passenger Vehicles
- 7.4 By Sales Channel
- 7.4.1 OEM-Fitted
- 7.4.2 Aftermarket
- 7.5 By Application
- 7.5.1 Automotive
- 7.5.2 Military and Civil Aviation
- 7.5.3 Others (Industrial, Wearable, and other Displays)
- 7.6 Geography
- 7.6.1 North America
- 7.6.1.1 United States
- 7.6.1.2 Canada
- 7.6.1.3 Mexico
- 7.6.2 South America
- 7.6.2.1 Brazil
- 7.6.2.2 Argentina
- 7.6.2.3 Rest of South America
- 7.6.3 Europe
- 7.6.3.1 United Kingdom
- 7.6.3.2 Germany
- 7.6.3.3 France
- 7.6.3.4 Rest of Europe
- 7.6.4 Asia-Pacific
- 7.6.4.1 China
- 7.6.4.2 Japan
- 7.6.4.3 South Korea
- 7.6.4.4 India
- 7.6.4.5 Rest of Asia-Pacific
- 7.6.5 Middle East
- 7.6.5.1 GCC
- 7.6.5.2 Rest of Middle East
- 7.6.6 Africa
- 7.6.6.1 South Africa
- 7.6.6.2 Rest of Africa
- 7.6.1 North America
8 COMPETITIVE LANDSCAPE
- 8.1 Strategic Moves
- 8.2 Market Share Analysis
- 8.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 8.3.1 Denso Corporation
- 8.3.2 Nippon Seiki Co., Ltd.
- 8.3.3 Panasonic Automotive Systems
- 8.3.4 Visteon Corporation
- 8.3.5 Continental AG
- 8.3.6 Robert Bosch GmbH
- 8.3.7 Valeo SE
- 8.3.8 BAE Systems PLC
- 8.3.9 Thales Group
- 8.3.10 Garmin Ltd.
- 8.3.11 Elbit Systems Ltd.
- 8.3.12 Pioneer Corporation
- 8.3.13 SaaB AB
- 8.3.14 Hudway LLC
- 8.3.15 Collins Aerospace
- 8.3.16 LG Display Co., Ltd.
- 8.3.17 Harman International
- 8.3.18 WayRay AG
- 8.3.19 Envisics Ltd.
- 8.3.20 Texas Instruments Incorporated
9 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 9.1 White-Space and Unmet-Need Assessment


