

|
시장보고서
상품코드
2123571
수술용 지혈대 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Surgical Tourniquets - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 수술용 지혈대 시장 규모는 2025년에 5억 7,428만 달러로 평가되었고 2026년 6억 1,707만 달러에서 2031년까지 8억 8,363만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 7.45%를 나타낼 전망입니다.
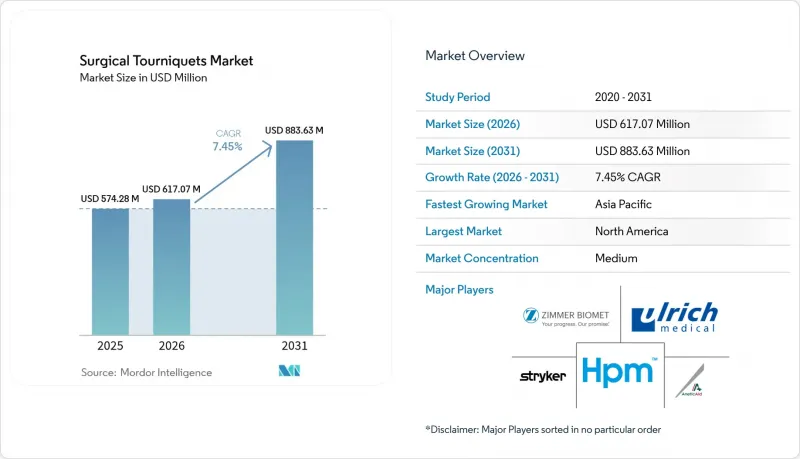
본 보고서는 제품 유형별(공압식 지혈대 시스템, 지능형 LOP 제어 시스템 등),용도별(하지 정형외과 수술, 상지 정형외과 수술 등), 최종 사용자별(병원 및 외상 센터, 외래수술센터(ASC) 등), 기술별(싱글 채널(1개 커프) 콘솔 등) 및 지역별(북미, 유럽, 아시아태평양, 기타)로 분류되어 있습니다.
전 세계 수술용 지혈대 시장 동향 및 인사이트
외상 및 교통사고로 인한 수술 건수 증가
특히 러시아·우크라이나 분쟁으로 인한 군사 부상자 데이터는 지혈대의 유효성을 입증하여 민간 응급의료(EMS) 분야에서의 채택을 촉진했습니다. 현장 조사에 따르면, 대량 사상자 상황에서 지혈대 착용 시간은 2분 미만이며, 이러한 능력은 전 세계 구급대원의 교육 과정에 점점 더 많이 포함되고 있습니다. ‘Combat Application Tourniquet’는 옷 위로 착용해도 일관되게 뛰어난 동맥 차단 효과를 발휘하여, 방호복을 착용하는 구급대원에게 매우 중요한 장점이 되고 있습니다. ‘STOP THE BLEED’ 캠페인을 통해 민간 부문에서의 보급이 가속화되고 있으며, 텍사스주의 카운티 응급의료기관에서는 2025년에 비압박성 출혈을 통제하기 위해 복부 대동맥 접합부용 장치를 도입했습니다. 4,095건의 민간 외상 사례에 걸친 증거에 따르면, 병원 도착 전에 지혈대를 사용한 경우 절단 위험을 높이지 않으면서 사망률을 52% 낮출 수 있는 것으로 나타났습니다. 이러한 분야를 아우르는 추세에 힘입어, 수술용 지혈대 시장은 수술실을 넘어 병원 도착 전 응급 의료 분야로 확대되고 있습니다.
선택적 정형외과 수술 및 관절 치환술 건수 증가
인도의 민간 병원 네트워크만 해도 2025 회계연도에 최대 2,500개의 병상을 증설할 예정이며, 11-12%의 수익 성장이 예상되어 이에 따라 관절 치환술 건수가 증가하고 있습니다. 고령화와 보험 적용 범위 확대가 수술 건수 증가를 뒷받침하는 한편, 의료 관광은 현재 아시아태평양 전체 병원 매출의 10-12%를 차지하고 있습니다. 연구 데이터에 따르면, 인공 슬관절 전치환술에서 지혈대 사용은 수술 중 출혈량을 줄이는 반면, 수술 후 내출혈을 약간 증가시키는 것으로 밝혀졌습니다. 그 결과, 외과의사들은 LOP(저산소압) 측정값을 바탕으로 공기압을 조절하여 조직 관련 합병증을 완화하는 압력 피드백 기능이 있는 콘솔을 선호하게 되었습니다. 또한, 실리콘 링의 설계는 수술 시야를 넓혀준다는 장점 덕분에 양쪽 무릎 수술에서 호평을 받고 있습니다.
신경·조직 손상과 관련된 소송 위험
메타분석에 따르면, 전방십자인대(ACL) 재건술에서 지혈대 사용은 수술 후 배액량을 100ml 증가시키고 단기적인 통증을 가중시키므로, 의료과실 소송에서 원고 측의 주장을 강화하는 요인이 되고 있습니다. 전신 마취 하에서 지혈대가 팽창하는 동안 심주기 효율이 현저히 저하되어, 수술 전후 기간의 위험 요인이 추가됩니다. 보험사는 현재 병원의 압력 피드백 콘솔 도입률을 바탕으로 보험료를 책정하고 있습니다. 판례에 따라 의료기관에 압력 지속 시간 기록이 점점 더 의무화되고 있으며, 감사 추적 기능을 자동으로 기록하는 장비의 도입이 확대되고 있습니다. 병원이 수술용 지혈대 시장에서 책임 리스크를 헤지하려는 가운데, 연장 보증 및 보상 조항을 함께 제공하는 공급업체가 유리한 입지를 차지하고 있습니다.
부문 분석
2025년, 수술용 지혈대 시장에서 신뢰할 수 있는 가압 제어와 외과의사들 사이에서 확고히 자리 잡은 선호도로 인해 공기식 장치가 53.88%의 점유율을 차지했습니다. 그러나 감염 관리 지침에 따라 수술실에서 일회용품의 사용이 장려됨에 따라, 일회용 멸균 커프는 연평균 성장률(CAGR) 8.51%로 성장하고 있습니다. 현재 재사용 가능한 커프는 교차 오염 사건을 추적하는 성능 감사의 대상이 되고 있어, 이러한 전환 추세를 더욱 가속화하고 있습니다.
팬데믹 기간 중 자원 절약 조치에 따라 일회용 커프로 전환한 병원에서는 멸균에 소요되는 인건비가 27% 절감된 것으로 보고되었습니다. 동시에, RFID가 내장된 스마트 커프는 스마트팜프와의 자동 페어링을 가능하게 하여, 압력 정확도 기록이 개별 환자와 확실하게 일치하도록 보장합니다. 방수 드레이프의 기술 혁신으로 인해 무릎 관절경 수술 시 피부 화상이 더욱 감소하고 있으며, 이는 환자 만족도 향상과 도입 가속화로 이어지고 있습니다.
2025년 수술용 지혈대 시장 규모 중 하지 정형외과 수술이 62.24%를 차지했습니다. 이는 무릎 관절 치환술 및 인공 고관절 치환술의 지속적인 성장에 힘입은 결과입니다. 그럼에도 불구하고, 외상 및 전장 의료 분야가 9.01%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 이는 사지 출혈 발생 후 2분 이내에 지혈대를 사용하도록 규정된 새로운 군용 현장 키트 및 응급 의료(EMS) 프로토콜 덕분입니다.
전투 부상자에 대한 조사를 계기로 골반 출혈용 복부 접합부 장치 등의 설계 개선이 진행되어 적용 범위가 확대되었습니다. 한편, 손목 재건술 및 미세혈관 피판술로 인해 상지 분야 수요는 안정적으로 유지되고 있으며, 성형외과 의사들 사이에서는 압력을 높이지 않으면서 절개 부위의 가시성을 높이기 위해 실리콘 링 시스템이 채택되고 있습니다.
지역별 분석
2025년 북미의 47.05% 시장 점유율은 첨단 외상 치료 시스템, 국방 조달 및 FDA 510(k) 신속 심사 등 조기 승인 절차에 힘입은 것이지만, 일부 정형외과 센터에서는 지혈대를 사용하지 않는 프로토콜로의 전환이 시작되고 있습니다. 그 결과, 지역별 매출은 소송을 우려하는 외과 의사들의 불안을 해소해 주는 적응형 가압 곡선을 갖춘 콘솔 쪽으로 기울고 있습니다. 텍사스주의 카운티 응급 의료 서비스(EMS)가 압박이 불가능한 출혈에 대해 접합부 지혈대를 채택하고 있다는 사실은 병원 도착 전 틈새 시장에서 지속적인 성장을 뒷받침하고 있습니다. 스트라이커(Striker)가 49억 달러에 이나리 메디컬(Inari Medical)을 인수한 것으로 상징되는 기업 통합은 출혈 제어 기술과 논리적으로 인접한 분야인 혈전 제거술로 경쟁의 폭을 넓히고 있습니다.
아시아태평양은 9.43%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있으며, 그 원동력은 인도 병원 네트워크 전반에서 시행되고 있는 17억 5,000만 달러 규모의 병상 확장 프로그램과 아세안(ASEAN) 전역에서 의료기기 승인을 원활하게 하는 규제 조화입니다. 의료 관광의 유입이 시술 건수를 끌어올리고 있는 한편, 167개국을 대상으로 한 전자 의료 비자 등 정부 주도의 노력으로 접근성이 더욱 확대되고 있습니다. 국내 생산이 시장 경쟁을 가속화하고 있습니다. 인도의 ‘메이크 인 인디아(Make in India)’ 프레임워크는 현지 조달을 장려하고 있어, 다국적 기업들은 합작 회사를 설립하거나 시장 점유율 하락의 위험에 직면해 있습니다.
유럽에서는 일관된 의료기기 규제와 프리미엄 LOP 콘솔에 대한 선호도 증가를 배경으로 꾸준한 수요 증가가 이어지고 있습니다. 울리히 메디컬(Ulrich Medical)은 2024년에 생산 확대를 위해 500만 유로를 투자하여 매출이 12% 증가한 1억 5,000만 유로에 달했다고 보고했으며, 이는 중견 기업도 전문적인 틈새 시장에서 성공할 수 있음을 보여줍니다. 중동 및 아프리카에서는 석유 수입이 외상 센터의 설비 갱신에 사용되고 있으며, 남미의 민간 병원 그룹은 거시경제의 변동이 여전히 역풍으로 작용하고 있음에도 불구하고 신중하게 스마트 콘솔을 단계적으로 도입하고 있습니다. 이러한 동향들이 맞물리면서 성장 기회는 각 지역에 분산되어 있으며, 공급업체들은 수술용 지혈대 시장에서 점유율을 확보하기 위해 민첩한 판매 채널 전략으로 이에 대응해야 합니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the surgical tourniquets market size was valued at USD 574.28 million in 2025 and estimated to grow from USD 617.07 million in 2026 to reach USD 883.63 million by 2031, at a CAGR of 7.45% during the forecast period (2026-2031).
This report is Segmented by Product Type (Pneumatic Tourniquet Systems, Intelligent LOP-Controlled Systems, and More), by Application (Lower-Limb Orthopedic Surgery, Upper-Limb Orthopedic Surgery, and More), by End User (Hospitals and Trauma Centers, Ambulatory Surgery Centers, and More), by Technology (Single-Channel (1-Cuff) Consoles, and More) and Geography (North America, Europe, Asia-Pacific, and More).
Global Surgical Tourniquets Market Trends and Insights
Rising Trauma & Road-Accident Surgeries
Military casualty data, notably from the Russia-Ukraine conflict, validated tourniquet efficacy and spurred civilian EMS adoption. Field studies show mass-casualty tourniquet placement times under two minutes, a capability increasingly embedded in paramedic curricula worldwide. The Combat Application Tourniquet consistently achieves superior arterial occlusion when applied over clothing, a critical advantage for first responders wearing protective gear. Civilian uptake accelerates via STOP THE BLEED campaigns, and county EMS agencies in Texas deployed abdominal aortic junctional devices in 2025 for non-compressible hemorrhage control. Evidence across 4,095 civilian trauma cases shows a 52% mortality reduction without higher amputation risk when tourniquets are used pre-hospital. This cross-sector momentum widens the surgical tourniquets market beyond operating rooms into pre-hospital care.
Growth in Elective Orthopedic & Joint-Replacement Volumes
Private hospital networks in India alone are adding up to 2,500 beds in fiscal 2025, with 11-12% revenue growth that lifts joint-replacement caseloads. Aging demographics and broader insurance coverage support higher procedure volumes, while medical tourism now contributes 10-12% of hospital top lines across Asia-Pacific. Study data reveal that tourniquet use in total knee arthroplasty cuts intraoperative blood loss but slightly increases postoperative bruising.Consequently, surgeons gravitate to pressure-feedback consoles that calibrate inflation to LOP readings, mitigating tissue-related complications. Silicone ring designs also gain favor because they extend surgical fields, a benefit in bilateral knee work.
Nerve-/Tissue-Damage Litigation Risk
Meta-analyses show tourniquet use during ACL reconstruction elevates postoperative drainage by 100 ml and increases short-term pain, sharpening plaintiff arguments in malpractice suits. Cardiac-cycle efficiency drops markedly during inflation under general anesthesia, adding peri-operative risk factors. Insurers are now pricing premiums against hospital adoption rates of pressure-feedback consoles. Legal precedents increasingly oblige facilities to log pressure duration, prompting procurement of devices with automated audit trails. Vendors that bundle extended warranties and indemnification clauses gain an edge as hospitals hedge liability in the surgical tourniquets market.
Other drivers and restraints analyzed in the detailed report include:
- Hospital & ASC Capacity Expansion in Emerging Markets
- Adoption of LOP-Smart Tourniquet Systems to Cut Nerve Injuries
- Shortage of Staff Trained in Optimal Pressure Management
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pneumatic devices controlled 53.88% of the surgical tourniquets market in 2025 owing to reliable inflation control and established surgeon preference. Disposable sterile cuffs, however, are growing at an 8.51% CAGR as infection-control guidelines push operating rooms toward single-use supplies. Re-usable cuffs now face performance audits that track cross-contamination events, amplifying the shift.
Hospitals that migrated to single-use cuffs during pandemic conservation mandates report 27% lower sterilization labor cost. Simultaneously, intelligent cuffs embedded with RFID facilitate automatic pairing with smart pumps, ensuring pressure accuracy logs match individual patients. Waterproof drape innovations further reduce skin burns in knee arthroscopy, improving patient satisfaction and accelerating adoption.
Lower-limb orthopedic surgery accounted for 62.24% of the surgical tourniquets market size in 2025, supported by sustained growth in knee and hip replacements. Nonetheless, trauma and battlefield care registers the highest CAGR at 9.01%, thanks to new military field kits and EMS protocols that stipulate tourniquet use within two minutes of extremity hemorrhage.
Combat casualty research sparked design improvements such as junctional abdominal devices for pelvic bleeding, broadening indication scope. Concurrently, upper-limb demand remains stable through wrist reconstruction and micro-vascular flap procedures, while plastic surgeons adopt silicone ring systems to expand incision visibility without raising pressure.
Complete Report Scope:
- By Product Type
- Pneumatic Tourniquet Systems
- Intelligent LOP-controlled Systems
- Elastic / Silicone-ring Tourniquets
- Disposable / Sterile Cuffs
- Re-usable Cuffs
- Accessories
- By Application
- Lower-Limb Orthopedic Surgery
- Upper-Limb Orthopedic Surgery
- Trauma & Battlefield Stabilisation
- Other Surgical Specialities
- By End User
- Hospitals & Trauma Centres
- Ambulatory Surgery Centres
- Military / Defence Medical Units
- Other End Users (Sports clinics, EMS)
- By Technology
- Single-Channel (1-cuff) Consoles
- Multi-Channel (2-4 cuff) Consoles
- Integrated Pressure-Feedback Software
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America's 47.05% share in 2025 rests on advanced trauma systems, defense procurement, and early approval pathways such as FDA 510(k) expedited reviews, but it also sees a nascent shift toward tourniquet-less protocols in select orthopedic centers. Regional sales therefore tilt toward consoles with adaptive pressure curves that reassure surgeons wary of litigation. Texas county EMS adoption of junctional tourniquets for non-compressible bleeds underscores continuing growth in pre-hospital niches. Corporate consolidation, illustrated by Stryker's USD 4.9 billion Inari Medical purchase, extends competitive breadth into thrombectomy-a logical adjacency to bleeding-control technologies.
Asia-Pacific records the fastest CAGR at 9.43%, fueled by USD 1.75 billion bed-expansion programs across Indian hospital networks and by regulatory harmonization that eases device approvals across ASEAN. Medical-tourism inflows fortify procedure volumes, while government initiatives such as e-medical visas for 167 countries further widen access. Domestic manufacturing drives price competition; India's Make-in-India framework encourages local sourcing, which presses multinationals to establish joint ventures or risk market share erosion.
Europe maintains steady uptake under cohesive medical-device regulations and growing preference for premium LOP consoles. Ulrich medical allocated EUR 5 million in 2024 to scale production, reporting a 12% revenue uplift to EUR 150 million-evidence that medium-sized players can prosper in specialized niches. Middle East and Africa funnel petro-revenues into trauma-center upgrades, and South America's private-hospital groups cautiously phase in smart consoles, though macroeconomic volatility remains a headwind. Collectively, these dynamics distribute growth pockets that vendors must navigate with agile channel strategies to capture share in the surgical tourniquets market.
- Stryker
- Zimmer Biomet
- ulrich medical
- Hammarplast Medical
- Anetic Aid
- VBM Medizintechnik
- Delfi Medical Innovations
- Daesung Maref
- HemaClear (OHK Medical Devices Inc.)
- DESSILLIONS & DUTRILLAUX
- Riester
- SAM Medical
- Tactical Medical Solutions
- CAT Resources (C-A-T)
- Dynarex
- Medline Industries Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising trauma & road-accident surgeries
- 4.2.2 Growth in elective Orthopedic & joint-replacement volumes
- 4.2.3 Expansion of hospitals & ASC capacity in emerging economies
- 4.2.4 Adoption of LOP-smart tourniquet systems to cut nerve injuries
- 4.2.5 Military demand for compact field tourniquets
- 4.2.6 Shift to blood-sparing outpatient arthroplasty protocols
- 4.3 Market Restraints
- 4.3.1 Nerve-/tissue-damage litigation risk
- 4.3.2 Shortage of staff trained in optimal pressure management
- 4.3.3 Move toward tourniquet-less arthroscopy & TKA techniques
- 4.3.4 Cost spike from single-use & re-processing regulations
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Pneumatic Tourniquet Systems
- 5.1.2 Intelligent LOP-controlled Systems
- 5.1.3 Elastic / Silicone-ring Tourniquets
- 5.1.4 Disposable / Sterile Cuffs
- 5.1.5 Re-usable Cuffs
- 5.1.6 Accessories
- 5.2 By Application
- 5.2.1 Lower-Limb Orthopedic Surgery
- 5.2.2 Upper-Limb Orthopedic Surgery
- 5.2.3 Trauma & Battlefield Stabilisation
- 5.2.4 Other Surgical Specialities
- 5.3 By End User
- 5.3.1 Hospitals & Trauma Centres
- 5.3.2 Ambulatory Surgery Centres
- 5.3.3 Military / Defence Medical Units
- 5.3.4 Other End Users (Sports clinics, EMS)
- 5.4 By Technology
- 5.4.1 Single-Channel (1-cuff) Consoles
- 5.4.2 Multi-Channel (2-4 cuff) Consoles
- 5.4.3 Integrated Pressure-Feedback Software
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Stryker Corporation
- 6.3.2 Zimmer Biomet Holdings Inc.
- 6.3.3 ulrich medical
- 6.3.4 Hammarplast Medical
- 6.3.5 Anetic Aid
- 6.3.6 VBM Medizintechnik
- 6.3.7 Delfi Medical Innovations
- 6.3.8 Daesung Maref
- 6.3.9 HemaClear (OHK Medical Devices Inc.)
- 6.3.10 DESSILLIONS & DUTRILLAUX
- 6.3.11 Riester
- 6.3.12 SAM Medical
- 6.3.13 Tactical Medical Solutions
- 6.3.14 CAT Resources (C-A-T)
- 6.3.15 Dynarex Corporation
- 6.3.16 Medline Industries Ltd.


