

|
시장보고서
상품코드
2123620
지혈대 시스템 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Tourniquet Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 지혈대 시스템 시장 규모는 2025년에 6억 110만 달러로 평가되었고, 2026년 6억 4,648만 달러에서 2031년까지 9억 3,027만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 7.55%를 나타낼 전망입니다.
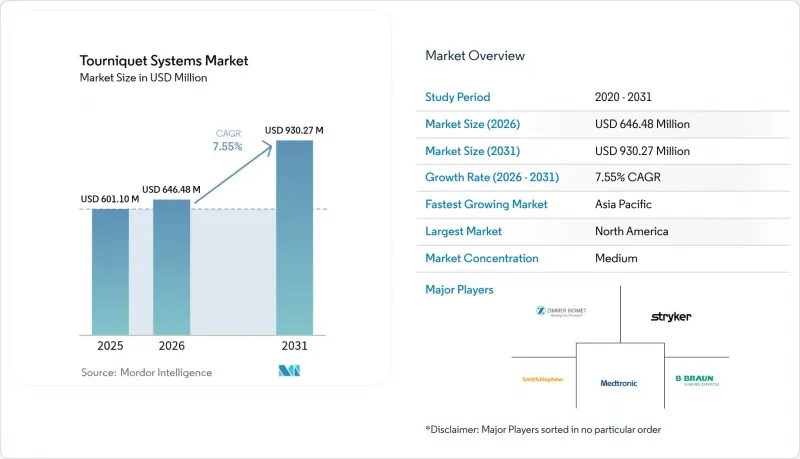
본 보고서는 구성 요소 유형별(지혈대 기구, 지혈대 커프), 용도별(하지 수술, 상지 수술, 기타), 최종 사용자별(병원, 기타), 소재별(나일론, 기타), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 지혈대 시스템 시장 동향 및 인사이트
전 세계적으로 급증하는 정형외과 및 외상 수술
고령화와 스포츠 의료에 대한 수요에 힘입어, 예정 수술 및 외상으로 인한 정형외과 수술 건수는 계속 증가하고 있습니다. 당일 시행되는 고관절 및 무릎 관절 치환술의 비율은 2017년 1%에서 2021년 30.5%로 상승했으며, 평균 입원 일수는 0.94일로 단축되어 신뢰성이 높은 사지 지혈 기구에 대한 의존도가 높아지고 있습니다. 전 세계 고관절·무릎 관절 임플란트 시장은 2023년에 전년 대비 7.2% 증가한 185억 달러에 달했습니다. 로봇 보조 수술의 보급으로 인해 명확한 수술 시야 확보가 더욱 중요해지고 있습니다. 지역별 격차는 여전히 현저하며, 미국의 우편번호 지역별로 하지 응급 절단률은 3.7%에서 90%까지 폭이 넓어, 효율적인 지혈대 도입이 필요한 의료 서비스가 미치지 못하는 지역이 존재함을 보여줍니다. 이러한 수술 동향이 맞물려 커프의 연간 교체 주기가 촉진되고, 마이크로프로세서 펌프로의 업그레이드가 추진됨에 따라 지혈대 시스템 시장이 뒷받침되고 있습니다.
사지 폐색압 스마트 지혈대 시스템의 급속한 보급
스마트 기기를 통해 임상 현장에서는 경험칙에 따른 수치에서 환자별로 최적화된 압력으로의 전환이 진행되고 있습니다. 스트라이커(Stryker)사의 ‘SmartPump 2.0’은 수술 전·후 데이터 스트림을 자동으로 기록하면서 더 낮은 폐색 임계값을 실현하고 있습니다. 또한, 지머 바이오메트(Zimmer Biomet)사의 ‘A.T.S. 5000’은 사지의 형태에 맞추어 가압을 조정하는 ‘개인 맞춤형 압력 기술’을 탑재하여 수술 후 통증 점수를 낮추고 있습니다. 비교 테스트 결과, 델피(Delphi)사의 수술용 등급 알고리즘은 100%의 자동 조절 정확도를 달성한 반면, 일반용 기기에서는 성능에 편차가 나타났습니다. 이러한 기능들은 병원의 품질 지표 및 보다 안전한 가압 범위를 요구하는 규제 당국의 요청과 부합하며, 스마트팜프는 지혈대 시스템 시장에서 가장 빠르게 성장하는 제품 부문으로서의 입지를 확고히 하고 있습니다.
수술 후 합병증(신경 손상·허혈)의 위험 증가
신경 마비는 과도한 지혈대 가압 및 장시간 착용과 관련된 주요 이상 반응으로 계속 남아 있습니다. 전 세계적 범위 검토에서는 허혈성 통증, 혈전색전증, 지혈대 후 증후군이 추가적인 우려 사항으로 확인되었으나, 증거에 기반한 프로토콜을 준수할 경우 그 발생률은 급격히 감소합니다. 현재 유럽 외상 지침에서는 마비 위험을 억제하기 위해 사용 시간 제한과 실시간 모니터링을 강조하고 있습니다. AORN의 2025년 실무 지침에서는 사지 둘레 측정, 커프 착용 상태 확인, 지속적인 압력 표시를 의무화하고 있으며, 이를 통해 의료 기관은 재사용 가능한 커프에 관한 방침을 재검토하도록 권장하고 있습니다. 소송에 대한 우려와 보험료 인상으로 인해 예산에 민감한 병원에서는 설비 투자가 지연될 가능성이 있으며, 이는 지혈대 시스템 시장의 성장 속도를 둔화시키는 요인이 되고 있습니다.
부문 분석
지혈대 커프는 2025년 매출의 88.20%를 차지했으며, 시술 건수와 가장 직접적으로 연계되는 소모품으로서 지혈대 시스템 시장의 기반을 이루고 있습니다. 정기적인 교체, 감염 관리용 일회용 정책, 사지별 다양한 구성으로 인해 커프는 구매 예산에 확실히 반영되어 있습니다. 스마트팜프의 도입은 현재로서는 틈새 시장이지만, 연평균 성장률(CAGR) 8.85%로 확대되고 있으며, 번들 계약에서는 어댑티브 펌프와 독자적으로 개발한 커프 제품 라인을 결합하여 판매 후 소모품 수익을 확보하려는 움직임이 점점 늘어나고 있습니다.
병원의 비용 분석에서는 재사용형 천 재질 커프와 관련된 멸균 작업의 부담 및 품질 편차 위험이 반복적으로 지적되고 있으며, 조달 동향은 라텍스 프리 일회용 나일론 또는 실리콘 재질 커프로 향하고 있습니다. 2024년 공급 제약 기간 동안, FDA는 커프의 제한적인 재사용을 승인했습니다. 이로 인해 기존 재고가 일시적으로 유지되었지만, 단일 공급원에 의존하는 공급망의 취약성이 부각되었습니다. 스마트 시스템에는 각 사이클을 전자 의료 기록(EMR)에 기록하는 디지털 자동 압력 센서가 내장되어 있어, 감사 추적 및 예방적 유지보수를 지원합니다. 이러한 데이터 기반의 실적이 보험사의 감사에 영향을 미치면서 구성 요소의 구성 비율은 변화할 것으로 예상되지만, 커프는 계속해서 수익의 기반이 되어 지혈대 시스템 시장의 장기적인 전망을 뒷받침할 것으로 보입니다.
하지 수술은 2025년 수술 건수의 67.90%를 차지했으며, 지혈대 시스템 시장 규모의 4억 815만 달러를 차지했습니다. 이는 상지에서의 사용에 비해 더 높은 가압 임계값과 더 긴 가압 시간을 활용하기 때문입니다. 인공 관절 치환술 증가, 전장에서의 외상, 당뇨병으로 인한 절단 등이 복합적으로 작용하여 수요를 높은 수준으로 유지하고 있으며, 각 요인은 모두 수년에 걸쳐 지속적인 추세를 보이고 있습니다.
상지 수술 건수는 절대 수로는 적지만, 손목 및 팔꿈치 부위의 최소 침습 수술 증가에 따라 2031년까지 연평균 성장률(CAGR) 9.05%로 확대되어 시장 평균을 상회할 것으로 예측됩니다. 비용 분석에 따르면, 탄성 스트랩은 수술 시야의 선명도를 저해하지 않으면서도 공압식 제품에 비해 손 수술 1건당 28.27달러의 비용 절감 효과를 가져옵니다. 이러한 인사이트로 인해, 특히 외래수술센터(ASC)에서 저렴한 기계식 루프의 틈새 시장 도입이 촉진되고 있습니다. 그 밖에도 응급의료(EMS)용 외상 키트와 하이브리드 혈관 수술은 ‘기타’ 범주에 분류되지만, 응급의료 종사자들이 휴대용 퀵 릴리스 밴드를 도입함에 따라 이 범주의 점유율은 안정적으로 유지되고 있습니다. 이러한 부문들이 결합되어 지혈대 시스템 시장은 수요가 많은 하지 부문와 높은 성장세를 보이는 상지 틈새 부문 사이에서 균형을 유지하고 있습니다.
지역별 분석
북미는 2025년 매출의 44.98%를 차지했으며, 이는 정형외과 수술 건수의 많음, 광범위한 보험 적용 범위, LOP 펌프의 조기 도입을 반영합니다. 미국의 병원 통합 및 집중 조달 계약은 공급업체의 사업 기반을 더욱 공고히 하고 있으며, 한편 국내 제조에 대한 보조금으로 생산 능력의 회복력이 강화되고 있습니다. 캐나다도 이러한 촉진요인의 대부분을 공유하고 있지만, 주별 감염 관리 지침에 따라 일회용 커프의 보급이 더욱 빠르게 진행되고 있습니다.
유럽은 엄격한 CE 마크 인증과 근거에 기반한 의료기기 선정을 촉진하는 지역 간 정형외과 레지스트리를 배경으로 꾸준한 성장을 유지하고 있습니다. 독일과 북유럽 국가에서는 스마트팜프의 보급률이 높은 반면, 남유럽에서는 비용을 중시하는 공압식 번들이 선호되고 있습니다. 또한, NATO 회원국들이 전술 키트를 보충함에 따라 해당 지역에서는 국방 비축 물자에서 수요도 서서히 증가하고 있습니다.
아시아태평양은 가장 성장세가 두드러진 지역으로, 수술 대기 현상이 해소되고 민간 보험 보급률이 상승함에 따라 연평균 성장률(CAGR)은 9.95%로 예측됩니다. 중국 내 현(縣) 단위의 외상 네트워크 확대와 인도에서 도로 교통사고로 인한 부상자 급증은 커프 소비를 뒷받침하고 있습니다. 일본 정형외과학회에서는 AI 연동형 가압 알고리즘 검사의 도입이 진행되고 있는 반면, 호주에서는 국방 부문 주도의 연구 개발이 민간 입찰 분야로도 파급되고 있습니다. 중동 및 아프리카와 남미는 절대 규모 면에서는 뒤처져 있지만, 두 자릿수 성장이 예상되는 부문이 존재합니다. 브라질의 디지털 건강 기록 전국 도입과 사우디아라비아의 ‘비전 2030’에 따른 병원 건설 계획에는 모두 스마트 지혈대 조달 조항이 포함되어 있습니다. 전력 공급이 불안정한 지역을 위한 배터리 불필요 공압식 유닛 등, 지역 특성에 맞춘 제품 적용을 통해 공급업체는 지혈대 시스템 시장의 사업 범위를 확대할 수 있게 됩니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the tourniquet systems market size was valued at USD 601.10 million in 2025 and estimated to grow from USD 646.48 million in 2026 to reach USD 930.27 million by 2031, at a CAGR of 7.55% during the forecast period (2026-2031).
This report is Segmented by Component Type (Tourniquet Instruments, Tourniquet Cuffs), Application (Lower-Limb Surgery, Upper-Limb Surgery, Others), End-User (Hospitals, and More), Material (Nylon, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Tourniquet Systems Market Trends and Insights
Surging Orthopedic & Trauma Surgeries Worldwide
Elective and trauma-based orthopedic volumes continue to climb, buoyed by aging populations and sports-medicine demand. Same-day hip and knee arthroplasties moved from 1% in 2017 to 30.5% in 2021, compressing average stays to 0.94 days and lifting reliance on reliable limb exsanguination tools. The global hip-knee implant sector grew 7.2% year-on-year to USD 18.5 billion in 2023, with robotic guidance amplifying the need for clear operative fields. Geographic variability remains stark; emergency lower-extremity amputation rates ranged from 3.7% to 90% across U.S. zip codes, signaling under-served segments that require efficient tourniquet deployment. Collectively, these procedure trends bolster annual replacement cycles for cuffs and drive upgrades to micro-processor pumps, sustaining the tourniquet systems market.
Rapid Adoption of Limb-Occlusion-Pressure Smart Tourniquet Systems
Smart devices shift practice from empirical values toward patient-specific pressures. Stryker's SmartPump 2.0 demonstrates lower occlusion thresholds while auto-documenting perioperative data streams . Zimmer Biomet's A.T.S. 5000 offers Personalized Pressure Technology that tailors inflation to limb morphology, reducing post-operative pain scores . Comparative testing showed Delfi's surgical-grade algorithms delivering 100% autoregulation accuracy versus variable performance among consumer devices. These capabilities resonate with hospital quality metrics and regulatory calls for safer pressure windows, positioning smart pumps as the fastest rising unit segment within the tourniquet systems market.
Higher Post-Operative Complication Risk (Nerve/Ischemia)
Nerve palsy remains the primary adverse event linked to excessive tourniquet pressure or duration. A global scoping review identified ischemic pain, thromboembolic events and post-tourniquet syndrome as additional concerns, though incidence drops sharply when evidence-based protocols are followed. European trauma guidelines now highlight time limits and real-time monitoring to curb paralysis risk. AORN's 2025 practice advisory mandates limb girth measurement, cuff fit checks and continuous pressure readouts, prompting facilities to reassess reusable cuff policies. Fear of litigation and higher insurance premiums can delay capital purchases among budget-sensitive hospitals, moderating the tourniquet systems market growth pace.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Military Procurement Amid Prolonged Conflicts
- Rising Prevalence of Diabetes-Related Amputations
- Shortage of Skilled Staff for Pressure Calibration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tourniquet cuffs generated 88.20% of 2025 revenue, anchoring the tourniquet systems market as the consumable element most directly tied to procedure counts. Recurring replacement, single-use infection-control policies and varied limb-specific configurations lock cuffs into purchasing budgets. Smart pump adoption, while currently niche, is advancing at a 8.85% CAGR, and bundled contracts increasingly pair adaptive pumps with proprietary cuff lines to lock in post-sale consumable income.
Hospital value analyses repeatedly highlight the sterilization labor and quality-variation risks linked to reusable fabrics, steering procurement toward latex-free disposable nylon or silicone cuffs. During 2024 supply constraints, the FDA endorsed limited cuff reuse, which temporarily propped up older stock yet underscored the fragility of single-source chains. Smart systems integrate digital auto-pressure sensors that log each cycle to the EMR, supporting audit trails and preventive maintenance. As these data credentials influence payer audits, the component mix is expected to shift, but cuffs will remain the revenue cornerstone, sustaining the long-term outlook for the tourniquet systems market.
Lower-extremity surgeries contributed 67.90% of 2025 procedures and USD 408.15 million of tourniquet systems market size, leveraging higher pressure thresholds and longer inflation times compared with arm applications. Arthroplasty growth, battlefield trauma and diabetic amputations converge to keep demand high, with each driver exhibiting durable multi-year trends.
Upper-limb procedures, although smaller in absolute numbers, are forecast to expand at 9.05% CAGR through 2031, outpacing market average as minimally invasive wrist and elbow work rises. Cost analyses show elastic straps saving USD 28.27 per hand surgery versus pneumatic alternatives without compromising field clarity. Such findings propel niche adoption of inexpensive mechanical loops, especially in ASCs. Elsewhere, EMS trauma kits and hybrid vascular cases fall into the "other" bucket that maintains a steady share as emergency clinicians integrate portable quick-release bands. Together, these segments keep the tourniquet systems market balanced between high-volume lower-limb and high-growth upper-limb niches.
Complete Report Scope:
- By Component Type
- Tourniquet Instruments
- Tourniquet Cuffs
- Pneumatic
- Non-pneumatic
- By Application
- Lower-limb Surgery
- Upper-limb Surgery
- Others
- By End-user
- Hospitals
- Ambulatory Surgical Centers
- Others
- By Material
- Nylon
- Silicone & Rubber
- Velcro & Textile
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America booked 44.98% of 2025 revenue, reflecting dense orthopedic procedure volumes, broad insurance coverage and early adoption of LOP pumps. U.S. hospital consolidation and centralized purchasing contracts further anchor supplier footprints, while domestic manufacturing subsidies bolster capacity resiliency. Canada mirrors many of these drivers but exhibits faster uptake of single-use cuffs due to provincial infection-control guidelines.
Europe maintained steady growth on the back of rigorous CE branding and pan-regional orthopedic registries that promote evidence-based device selection. Germany and the Nordic countries exhibit higher penetrations of smart pumps, whereas Southern Europe favors cost-sensitive pneumatic bundles. The region is also seeing incremental demand from defense stockpiles as NATO members replenish tactical kits.
Asia-Pacific represents the fastest growing cluster, posting a 9.95% CAGR projection as procedure backlogs clear and private insurance penetration rises. China's county-level trauma network expansion and India's surge in road-traffic injuries catalyze cuff consumption. Japanese orthopedic societies are piloting AI-linked pressure algorithms, while Australia's defense-driven R&D spills into civilian tenders. Middle East & Africa and South America trail in absolute size but offer double-digit growth pockets; Brazil's move to universal digital health records and Saudi Arabia's Vision 2030 hospital build-outs both embed smart tourniquet procurement clauses. Geo-specific product adaptations, such as battery-free pneumatic units for power-unstable regions, enable suppliers to extend the tourniquet systems market footprint.
- Delfi Medical Innovations Inc.
- Zimmer Biomet
- Hammarplast Medical
- Stryker
- Anetic Aid Ltd.
- Ulrich Medical
- OHK Medical Devices
- Rudolf Riester
- Dessillons & Dutrillaux
- VBM Medizintechnik
- B. Braun
- Smiths Group
- Medtronic
- North American Rescue LLC
- SAM Medical
- RevMedx Inc.
- TyTek Medical
- C.A.T Resources
- Tactical Medical Solutions Inc.
- Dunlap Medical Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Orthopedic & Trauma Surgeries Worldwide
- 4.2.2 Rapid Adoption Of Limb-Occlusion-Pressure (LOP) Smart Tourniquet Systems
- 4.2.3 Increasing Military Procurement Amid Prolonged Conflicts
- 4.2.4 Rising Prevalence Of Diabetes-Related Amputations
- 4.2.5 Growth Of Outpatient & Asc Orthopedic Procedures
- 4.2.6 Emergence Of Low-Cost Pneumatic Units For Emerging Markets
- 4.3 Market Restraints
- 4.3.1 Higher Post-Operative Complication Risk (Nerve/Ischemia)
- 4.3.2 Shortage Of Skilled Or Staff For Pressure Calibration
- 4.3.3 Sterilization Concerns With Reusable Cuffs
- 4.3.4 Regulatory Scrutiny Over Hazardous Pressure Thresholds
- 4.4 Value / Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Component Type
- 5.1.1 Tourniquet Instruments
- 5.1.2 Tourniquet Cuffs
- 5.1.2.1 Pneumatic
- 5.1.2.2 Non-pneumatic
- 5.2 By Application
- 5.2.1 Lower-limb Surgery
- 5.2.2 Upper-limb Surgery
- 5.2.3 Others
- 5.3 By End-user
- 5.3.1 Hospitals
- 5.3.2 Ambulatory Surgical Centers
- 5.3.3 Others
- 5.4 By Material
- 5.4.1 Nylon
- 5.4.2 Silicone & Rubber
- 5.4.3 Velcro & Textile
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.3.1 Delfi Medical Innovations Inc.
- 6.3.2 Zimmer Biomet Holdings Inc.
- 6.3.3 Hammarplast Medical AB
- 6.3.4 Stryker Corporation
- 6.3.5 Anetic Aid Ltd.
- 6.3.6 Ulrich Medical
- 6.3.7 OHK Medical Devices
- 6.3.8 Rudolf Riester GmbH
- 6.3.9 Dessillons & Dutrillaux
- 6.3.10 VBM Medizintechnik GmbH
- 6.3.11 B. Braun Melsungen AG
- 6.3.12 Smith & Nephew plc
- 6.3.13 Medtronic plc
- 6.3.14 North American Rescue LLC
- 6.3.15 SAM Medical
- 6.3.16 RevMedx Inc.
- 6.3.17 TyTek Medical
- 6.3.18 C.A.T Resources
- 6.3.19 Tactical Medical Solutions Inc.
- 6.3.20 Dunlap Medical Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


