

|
시장보고서
상품코드
2123722
토크 센서 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Torque Sensor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
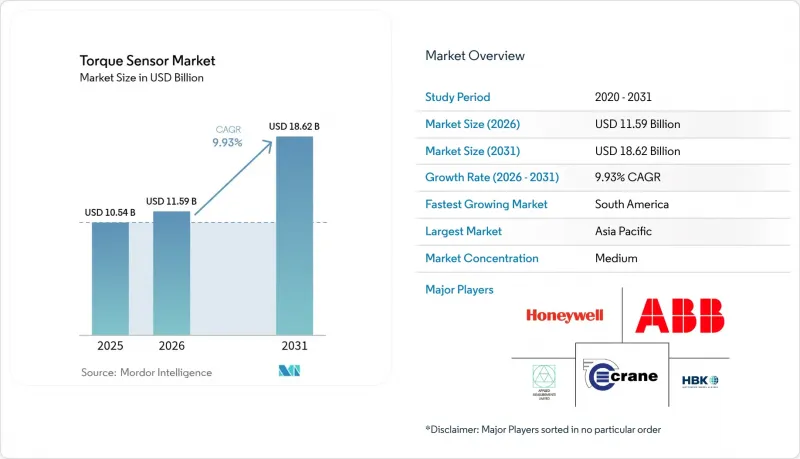
에 의하면, 2026년 세계의 토크 센서 시장 규모는 115억 9,000만 달러로 추정되고 있어 2025년 105억 4,000만 달러에서 확대되어, 2031년에는 186억 2,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 9.93%를 나타낼 전망입니다.
본 보고서는 제품 유형(반력 토크 센서, 회전 토크 센서), 기술(스트레인 게이지, 자기탄성, 기타), 용도(자동차, 항공우주 및 방위, 기타), 최종 사용자 산업(OEM 시험대 및 품질 보증, 공정 내 모니터링, 기타), 지역(북미, 기타)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 토크 센서 시장 동향 및 인사이트
전동 파워 스티어링(EPS) 시스템의 전동화
전동 파워 스티어링(EPS)에 대한 토크 모니터링 의무화로 인해 경기 침체기에도 수요는 견조한 추세를 보였습니다. 2024년에 발효된 유럽 규정에서는 자율 주행을 지원하기 위해 지속적인 조향 토크 피드백이 의무화되었으며, 모든 EPS 유닛에 최소 1개의 센서를 장착해야 합니다. 각 OEM 업체들은 기능 안전 목표를 충족하기 위해 이중 중복 설계를 채택했으며, 그 결과 차량당 센서 탑재 수가 실질적으로 두 배로 증가했습니다. Vitesco와 같은 공급업체들은 EPS의 토크 감지를 반자동 차선 유지 및 운전자 의도 예측을 실현하는 핵심 요소로 꼽고 있습니다. 동일한 데이터 채널이 OTA(Over-the-Air) 분석에서도 재사용되기 때문에 통합업체의 수명 주기 서비스 수익이 증가하고 있습니다. 기존의 유압식 스티어링 플랫폼이 단계적으로 폐지됨에 따라, 대상 자동차 기반은 돌이킬 수 없이 EPS 아키텍처로 전환되었습니다.
제조업 분야의 자동화 발전과 코봇
협동 로봇은 ISO 10218 안전 기준을 준수하기 위해 즉각적인 토크 감지가 필요하며, 이로 인해 코봇의 출하 대수와 센서 유닛 수 사이에 1대 1의 관계가 형성되었습니다. 2024년에는 전 세계 코봇 판매 대수가 기존 산업용 로봇을 넘어섰으며, 전자, 식품, 경량 조립 라인용 EMI 내성을 갖춘 다축 토크 센서에 대한 수요가 급증했습니다. 인증 지침에 따라 중복 감지가 의무화됨에 따라 결과적으로 각 로봇의 BOM(부품표) 가치가 실질적으로 상승했습니다. 2024년 폴란드 중소기업의 보급률은 26%에 그쳐, 유럽 제조업 전반에 막대한 잠재적 성장 여지가 있음을 보여줍니다. 스마트 워크셀이 섬유 및 농업 가공 공장으로 확산됨에 따라, 그 장기적인 영향은 개별 자동화의 범위를 넘어 확장되고 있습니다.
자동차 양산 프로그램의 가격 민감도
OEM의 비용 절감 목표에 따라 주류 EV 플랫폼의 센서 가격은 개당 50달러 전후에서 정체되었고, 공급업체는 보조 기능을 줄일 수밖에 없게 되었습니다. 배터리 팩 비용을 상쇄해야 할 필요성으로 인해 구동계 부품 하나하나에 대한 심사가 엄격해졌으며, 플랫폼 표준화로 인해 사양은 더욱 상품화되었습니다. 2024년 희토류 자석 공급 차질로 인해 이러한 딜레마가 더욱 심화되었고, 인도와 남미의 자동차 제조업체들은 정밀도 저하 위험을 감수하고 대체 소재 채택을 검토할 수밖에 없게 되었습니다. 이에 대응하여 공급업체들은 모듈식 전자 장치를 도입하여, 엔트리 모델용으로는 저비용 코어를 유지하면서도 프리미엄 등급용으로는 옵션으로 컨디셔닝 보드를 채택할 수 있도록 했습니다.
부문 분석
2025년, 회전식 유닛은 구동계, 풍력 터빈 및 공정 제어에 도입된 것을 배경으로 토크 센서 시장 점유율의 64.78%를 차지했습니다. 이들은 전기차 및 터빈의 폐쇄 루프 제어를 뒷받침하는 연속적인 현장 측정을 실현했습니다. 반응형은 시장 규모는 작지만, 기계 가공 및 배터리 셀 랩 공정에서 자동 시험대가 보급됨에 따라 연평균 성장률(CAGR) 11.32%를 기록했습니다. 디지털 텔레메트리 도입으로 슬립 링이 불필요해지고, 가혹한 산업 환경에서의 신뢰성이 향상됨에 따라 회전형 설계의 가치가 높아졌습니다.
회전식 센서는 엣지 컴퓨팅 노드로 진화하여, 예측 유지보수를 위해 데이터를 클라우드 대시보드로 스트리밍하게 되었습니다. 가공 공정에서는 공구의 마모를 나타내는 토크의 급격한 상승을 감지하기 위해 반응형 유닛이 채택되었으며, 항공우주 분야의 구조용 밀링 가공에서 ‘제로 결함’ 프로그램이 추진되었습니다. OEM 각사가 추적성 요건을 충족하기 위해 구형 조립 라인을 개조하는 움직임에 힘입어 토크 센서 시장은 혜택을 보고 있으며, 두 센서 카테고리가 병행하여 성장을 지속할 것으로 확실시되고 있습니다.
2025년, 스트레인 게이지(strain gauge)는 비용 면과 입증된 견고성으로 인해 지지를 받아 매출의 47.85%를 계속 차지했습니다. 한편, SAW 센서는 연평균 성장률(CAGR) 12.74%를 기록하며, EMI 내성 및 무선 데이터 전송이 가장 중요시되는 분야에서 점유율을 확대했습니다. 자기탄성식은 펌프 샤프트 등 밀폐형·비접촉 용도에 사용된 반면, 광섬유식은 나노라디안 단위의 분해능이 프리미엄 가격을 정당화하는 실험실 및 항공우주 분야의 교정 용도를 목표로 했습니다.
2024년 SAW 기술의 혁신을 통해 1,000°C까지의 내열성과 10µm의 변위 분해능이 실현되었습니다. 이러한 성능 덕분에 가스 터빈이나 심층 시추와 같은 가혹한 환경에서 시장 진입이 가능해졌습니다. 그 결과, 토크 센서 시장에서는 기술의 양극화가 나타났습니다. 즉, 범용화된 자동차용 스티어링에는 저비용의 스트레인 게이지가, 위험한 환경이나 미션 크리티컬한 틈새 시장에는 고부가가치의 SAW나 광학식 유닛이 채택되는 양상입니다.
지역별 분석
아시아태평양은 2025년 매출의 35.92%를 차지했으며, 자동차 조립, 반도체 제조, 로봇 기술 도입이 활발한 덕분에 계속해서 주도적인 위치를 유지했습니다. 중국은 EPS 출하량에서 1위를 차지했고, 일본은 고정밀 스트레인 게이지 기판을 공급했으며, 한국의 주요 전자 기업들은 배터리 및 디스플레이 생산 라인에 고해상도 토크 피드백을 도입했습니다. 인도가 희토류 자석 생산의 현지화를 추진하며 2026년까지 연간 500톤의 생산 능력을 목표로 하고 있어, 지역 전체의 원자재 리스크가 완화될 전망입니다.
북미에서는 항공우주 및 방위 분야 시스템 통합사업자들이 엔진 시험용으로 고온 광학 센서를 채택함에 따라, 프리미엄 틈새 시장으로서의 입지를 유지했습니다. 미국의 전기차(EV) 스타트업은 정교한 토크 제어 루프가 필요한 축류형 모터를 활용하여 SAW(표면탄성파) 및 자기탄성 장치에 대한 수요를 견인했습니다. 자동차 수출 거점으로서 멕시코의 역할이 확대됨에 따라, 스티어링 및 드라이브트레인용 센서에 대한 중규모의 비용 중심 수주가 증가했습니다.
유럽에서는 협동 로봇의 안전 기준 및 자동차 자율 주행 관련 규정에 토크 측정이 포함된다는 규제 요건에 따라 꾸준한 진전이 나타났습니다. 독일의 자동화 공급업체는 센서 게이트웨이를 프로그래머블 로직 컨트롤러(PLC)에 통합한 반면, 프랑스의 원자력 유지보수 계약업체는 가동 중단 기간을 단축하기 위해 무선 토크 헤드를 채택했습니다. 브라질을 필두로 한 남미에서는 OEM 업체들이 광범위한 시험대 계측 장비가 필요한 새로운 프레스 가공 라인과 파워트레인 라인을 도입함에 따라 10.98%라는 가장 높은 연평균 성장률(CAGR)을 기록했습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the global torque sensor market size in 2026 is estimated at USD 11.59 billion, growing from 2025 value of USD 10.54 billion with 2031 projections showing USD 18.62 billion, growing at 9.93% CAGR over 2026-2031.
This report is Segmented by Product Type (Reaction Torque Sensors, Rotational/Rotary Torque Sensors), Technology (Strain-Gauge, Magnetoelastic, and More), Application (Automotive, Aerospace and Defense, and More), End-User Industry (OEM Test-Stand and QA, In-Process Monitoring, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Torque Sensor Market Trends and Insights
Electrification of Power-Steering (EPS) Systems
Mandated torque monitoring for electric power-steering hardened demand even during economic slow-downs. European regulations issued in 2024 required continuous steering-torque feedback for autonomous-readiness, obligating every EPS unit to embed at least one sensor. OEMs adopted dual-redundant designs to satisfy functional-safety targets, effectively doubling sensor volumes per vehicle. Suppliers such as Vitesco cited EPS torque sensing as a core enabler for semi-autonomous lane-keeping and driver-intention prediction. The same data channel is reused in over-the-air analytics, increasing lifetime service revenue for integrators. As legacy hydraulic steering platforms sunset, the addressable automotive base shifted irreversibly toward EPS architectures.
Rising Automation and Cobots in Manufacturing
Collaborative robots required instantaneous torque detection to comply with ISO 10218 safety limits, creating a one-to-one relationship between cobot shipments and sensor units. Global cobot sales outpaced conventional industrial robots in 2024, inducing a steep ramp in EMI-resistant, multi-axis torque sensors destined for electronics, food and light-assembly lines. Certification guidelines enforced redundant sensing, effectively raising bill-of-materials value for each robot. Penetration remained only 26% among Polish SMEs in 2024, illustrating vast latent upside across European manufacturing. Long-term impact spans beyond discrete automation as smart work-cells propagate into textile and agri-processing plants.
Price Sensitivity in Volume Automotive Programs
OEM cost-down targets capped sensor pricing near USD 50 per unit in mainstream EV platforms, pressuring suppliers to strip auxiliary features. The need to offset battery-pack costs heightened scrutiny of every drivetrain component, with platform standardization further commoditizing specifications. Rare-earth magnet supply disruptions in 2024 exacerbated the dilemma, forcing Indian and South American automakers to weigh substitute materials that risked lower precision. Suppliers countered with modular electronics, allowing optional conditioning boards for premium trims while preserving a low-cost core for entry variants.
Other drivers and restraints analyzed in the detailed report include:
- Surge in E-Bike and Micromobility Production
- Growing Use in Axial-Flux Motors for EV Drivetrains
- Reliability Issues under Electromagnetic Interference
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rotational units captured 64.78% of torque sensor market share in 2025 on the strength of drivetrain, wind-turbine and process-control deployments. They offered continuous, in-situ measurement that supported closed-loop control in EVs and turbines. Reaction types, while smaller in base, posted an 11.32% CAGR as automated test-stands proliferated across machining and battery-cell wrap processes. Digital telemetry elevated rotational designs by removing slip rings, boosting reliability in harsh industrial settings.
Rotational sensors evolved into edge-computing nodes, streaming data to cloud dashboards for predictive maintenance. In-process machining adopted reaction units to catch torque spikes indicative of tool wear, advancing zero-defect programs in aerospace structural milling. The torque sensor market benefits as OEMs retrofit older assembly lines to meet traceability mandates, ensuring both sensor categories sustain parallel growth.
Strain-gauges retained 47.85% revenue in 2025, favored for cost and proven ruggedness. Yet, SAW sensors recorded a 12.74% CAGR and gained share where EMI immunity and wireless data mattered most. Magnetoelastic variants served sealed, non-contact duties in pump shafts, whereas optical fibers targeted lab and aerospace calibration where nano-radian resolution justified premium pricing.
SAW innovations in 2024 achieved temperature tolerance to 1,000 °C and 10 µm displacement resolution. Such capabilities unlocked extreme-environment markets like gas turbines and deep-well drilling. The torque sensor market thus witnessed technology bifurcation: low-cost strain-gauges for commoditized automotive steering, and high-value SAW or optical units for hazardous or mission-critical niches.
Complete Report Scope:
- By Product Type
- Reaction Torque Sensors
- Rotational / Rotary Torque Sensors
- By Technology
- Strain-Gauge
- Magnetoelastic
- Optical
- SAW (Surface Acoustic Wave)
- Others
- By Application
- Automotive
- Aerospace and Defense
- Industrial Manufacturing and Robotics
- Medical and Healthcare
- Energy and Power
- By End-User Industry
- OEM Test-Stand and QA
- In-Process Monitoring
- Research and Development
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific generated 35.92% of 2025 revenue and sustained leadership through dense automotive assembly, semiconductor fabrication and robotics adoption. China led EPS volumes, Japan supplied precision strain-gauge substrates, and South Korea's electronics majors deployed high-resolution torque feedback in battery and display lines. India's push to localize rare-earth magnet production, with 500-tonne annual capacity targeted by 2026, promised to moderate raw-material risk across the region.
North America maintained its premium niche as aerospace and defense integrators employed high-temperature optical sensors for engine testing. US EV start-ups leveraged axial-flux motors requiring sophisticated torque control loops, bolstering demand for SAW and magnetoelastic devices. Mexico's growing role as an automotive export hub amplified mid-volume, cost-sensitive orders for steering and drivetrain sensing.
Europe advanced steadily on regulatory mandates that embedded torque measurement into collaborative robot safety standards and vehicle autonomous-readiness rules. Germany's automation vendors integrated sensor gateways into programmable-logic controllers, while France's nuclear maintenance contractors adopted wireless torque heads to accelerate outage turnarounds. South America, led by Brazil, posted the fastest 10.98% CAGR as OEMs installed new stamping and powertrain lines requiring extensive test-stand instrumentation.
- ABB Ltd
- Honeywell International Inc.
- Hottinger Bruel & Kjaer (HBK - Spectris plc)
- TE Connectivity Ltd
- Kistler Instrumente AG
- Infineon Technologies AG
- Norbar Torque Tools Ltd
- Crane Electronics Ltd
- S. Himmelstein & Company Inc.
- Datum Electronics Ltd (Indutrade AB)
- Applied Measurements Ltd
- PCB Piezotronics Inc. (MTS)
- MagCanica Inc.
- Futek Advanced Sensor Technology Inc.
- Forsentek Co. Ltd
- Bota Systems AG
- ATI Industrial Automation (Novanta)
- Althen Sensors & Controls GmbH
- Sensor Technology Ltd (TorqSense)
- Burster Prazisionsmesstechnik GmbH
- Transense Technologies plc (SAWSense)
- Interface Inc.
- Mountz Inc.
- KTR Kupplungstechnik GmbH
- OPKON Optik Elektronik Kontrol San. A.S.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Electrification of Power-Steering (EPS) systems
- 4.2.2 Rising Automation and Cobots in Manufacturing
- 4.2.3 Surge in E-bike and Micromobility Production
- 4.2.4 Growing Use in Axial-Flux Motors for EV Drivetrains
- 4.2.5 On-board Torque Monitoring in Smart Wind Turbines
- 4.3 Market Restraints
- 4.3.1 Price Sensitivity in Volume Automotive Programs
- 4.3.2 Reliability Issues under Electromagnetic Interference
- 4.3.3 Supply Bottlenecks for High-Grade Magnetoelastic Alloys
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors
- 4.9 Industry Value-Chain Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Reaction Torque Sensors
- 5.1.2 Rotational / Rotary Torque Sensors
- 5.2 By Technology
- 5.2.1 Strain-Gauge
- 5.2.2 Magnetoelastic
- 5.2.3 Optical
- 5.2.4 SAW (Surface Acoustic Wave)
- 5.2.5 Others
- 5.3 By Application
- 5.3.1 Automotive
- 5.3.2 Aerospace and Defense
- 5.3.3 Industrial Manufacturing and Robotics
- 5.3.4 Medical and Healthcare
- 5.3.5 Energy and Power
- 5.4 By End-User Industry
- 5.4.1 OEM Test-Stand and QA
- 5.4.2 In-Process Monitoring
- 5.4.3 Research and Development
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Russia
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd
- 6.4.2 Honeywell International Inc.
- 6.4.3 Hottinger Bruel & Kjaer (HBK - Spectris plc)
- 6.4.4 TE Connectivity Ltd
- 6.4.5 Kistler Instrumente AG
- 6.4.6 Infineon Technologies AG
- 6.4.7 Norbar Torque Tools Ltd
- 6.4.8 Crane Electronics Ltd
- 6.4.9 S. Himmelstein & Company Inc.
- 6.4.10 Datum Electronics Ltd (Indutrade AB)
- 6.4.11 Applied Measurements Ltd
- 6.4.12 PCB Piezotronics Inc. (MTS)
- 6.4.13 MagCanica Inc.
- 6.4.14 Futek Advanced Sensor Technology Inc.
- 6.4.15 Forsentek Co. Ltd
- 6.4.16 Bota Systems AG
- 6.4.17 ATI Industrial Automation (Novanta)
- 6.4.18 Althen Sensors & Controls GmbH
- 6.4.19 Sensor Technology Ltd (TorqSense)
- 6.4.20 Burster Prazisionsmesstechnik GmbH
- 6.4.21 Transense Technologies plc (SAWSense)
- 6.4.22 Interface Inc.
- 6.4.23 Mountz Inc.
- 6.4.24 KTR Kupplungstechnik GmbH
- 6.4.25 OPKON Optik Elektronik Kontrol San. A.S.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


