|
시장보고서
상품코드
2123748
자동차용 엣지 컴퓨팅 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Edge Computing In Automotive - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
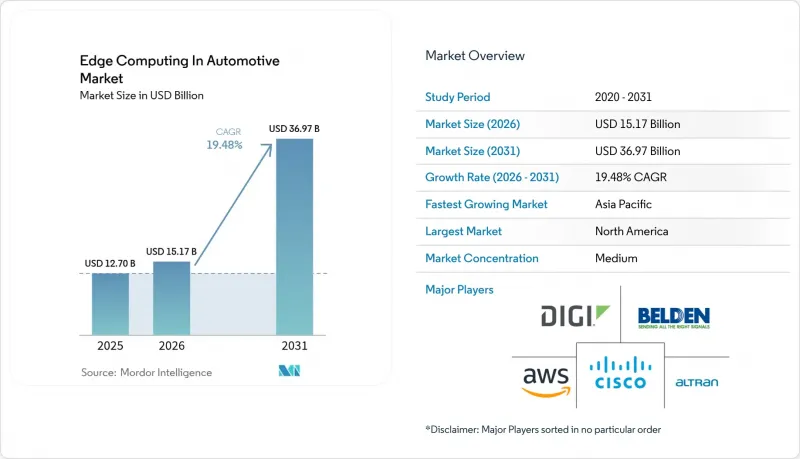
자동차용 엣지 컴퓨팅 시장 규모는 2026년에 151억 7,000만 달러로 추정되고 2025년 127억 달러에서 확대해, 2031년에는 369억 7,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 19.48%로 성장할 것으로 전망됩니다.
본 보고서는 구성 요소(하드웨어, 소프트웨어 등), 도입 모델(자동차용 엣지, 네트워크/MEC 엣지 등), 차종(승용차, 소형 상용차 등), 용도(커넥티드카(인포테인먼트 및 OTA), ADAS 및 자율주행, 교통 관리 및 V2I 등),및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 자동차용 엣지 컴퓨팅 시장 동향 및 인사이트
주요 동향 - 차량용 센서의 보급과 5G의 확산
현대 자동차에는 최대 200개의 센서가 탑재되어 있으며, 시간당 25GB의 데이터를 스트리밍하고 있습니다. 이 데이터 양은 기존 아키텍처로는 처리하기 어려울 정도로 방대합니다. 5G 무선 접속은 현재 10밀리초 미만의 지연을 실현하고 있으며, 이는 도이치 텔레콤과 노키아가 Car2MEC 시험에서 V2X 지연을 30밀리초 미만으로 단축함으로써 입증되었습니다. 따라서 자동차 제조업체들은 중요한 정보를 클라우드로 전송하기 전에 위험을 분류 및 압축하고, 이에 대응하기 위한 로컬 처리 기능을 탑재하고 있습니다. 그 결과, 중앙 집중형에서 분산형 컴퓨팅으로의 결정적인 전환이 일어나고 있으며, 이는 하드웨어 수요 증가를 뒷받침하고 자동차 시장에서 엣지 컴퓨팅의 급속한 연평균 성장률(CAGR)을 촉진하고 있습니다.
주류화 - 소프트웨어 정의 차량(SDV)으로의 OEM 전환
각 제조업체는 코드 업데이트와 디지털 기능을 중심으로 비즈니스 모델을 재구축하고 있습니다. 보쉬와 폭스바겐의 자회사인 카리아드(Cariad)는 2025년 출시 예정인 차량을 위한 AI 플랫폼을 공동 개발하기 위해 1,000명의 엔지니어를 배정했습니다. 상시 연결된 자동차에는 코드를 안전하게 검증하고 롤백하기 위한 보안 무선(OTA) 소프트웨어 배포 경로와 더불어 고성능 차량용 컴퓨팅이 요구됩니다. 이러한 워크플로는 서비스 수익원을 확대하며, 자동차 시장에서 엣지 컴퓨팅을 수익화의 핵심 축으로 자리매김하고 있습니다.
주류화 - 높은 초기 인프라 투자(CAPEX)
완벽한 엣지 스택에는 컴퓨팅 노드, 프라이빗 5G, 강화된 보안이 통합되어 있으며, 이러한 조합으로 인해 버라이즌과 아우디의 독일 테스트 사이트 예산은 1,000만 달러를 초과했습니다. 자본 집약적인 특성 때문에 중소 자동차 제조업체들은 시장 진입을 주저하고 있으며, 가격에 민감한 지역에서는 프로젝트가 정체되어 있습니다. 그 결과, 도입 단계에서는 즉각적인 안전 효과를 기대할 수 있는 기능이 우선시되고, 보다 광범위한 최적화는 비용 곡선이 하향될 때까지 미뤄지게 됩니다.
부문별 분석
2025년에는 하드웨어가 매출의 43.45%를 차지하며, 차량 내 환경에서 견고한 프로세서, AI 가속기 및 열 관리 솔루션의 중요한 역할이 부각되었습니다. 이 비율은 진동과 주변 온도 125°C를 견딜 수 있는 반도체 덕분에 자동차용 엣지 컴퓨팅 시장에서 가장 큰 점유율을 차지하고 있습니다. 금액 기준으로 볼 때, 자동차용 엣지 컴퓨팅 시장의 하드웨어 규모는 계속해서 확대될 전망이지만, 통합 업체들이 전 세계의 다양한 차량군을 대상으로 무선(OTA)을 통한 롤아웃을 관리하고 있기 때문에 서비스 부문은 24.89%라는 더 가파른 CAGR을 기록하고 있습니다. 자동차 제조업체들은 기능 안전, 사이버 보안, 실시간 스케줄링의 학습 곡선이 가파르기 때문에 턴키 서비스에 치중하고 있습니다. 인텔(Silicon Mobility 인수 후)과 같은 공급업체들은 칩에 미들웨어와 장기 업데이트 계약을 묶어 제공합니다. 이러한 변화로 인해 이익 마진은 순수한 하드웨어 사업에서 벗어나고 있으며, 플랫폼 벤더들은 클라우드 사업자와의 제휴를 통해 공동의 라이프사이클 솔루션을 제공해야 하는 상황에 놓여 있어 서비스 부문의 성장세가 더욱 가속화되고 있습니다.
차량용 컴퓨팅은 2025년 매출의 46.02%를 차지했으며, 이는 각 OEM 업체들이 자율형 신뢰성을 중시하고 있음을 보여줍니다. 그럼에도 불구하고, 스마트 시티 예산에 힘입어 단일 차량을 넘어선 상황 인식을 가능하게 하는 노변 장비가 도입됨에 따라 인프라 노드는 연평균 성장률(CAGR) 21.55%로 확대되고 있습니다. 이러한 성장은 공공 에지 자산 내 자동차 시장의 엣지 컴퓨팅 규모를 확대시켜, 통신 사업자와 지자체가 수익 분배 체계에 참여하도록 하는 계기가 되고 있습니다. 차량, 네트워크 및 도로변 프로세서가 연계되는 하이브리드 토폴로지가 등장하고 있습니다. Automotive Edge Computing Consortium은 비용과 지연 시간을 최적화하기 위해 이러한 분산형 컴퓨팅 프레임워크를 추진하고 있습니다. 자동차 제조업체는 현재 이종 도메인에 걸친 소프트웨어 인증을 수행해야 하며, 이로 인해 상호 운용성 툴체인이 고도화되고 표준화 활동이 촉진되고 있습니다.
지역별 분석
북미는 조기 5G 도입, 체계적인 주파수 정책, 그리고 OEM과 기술 기업 간의 긴밀한 파트너십에 힘입어 2025년에는 매출의 34.95%를 차지하며 1위를 차지했습니다. 테슬라, 제너럴 모터스, 포드는 인텔, 엔비디아, 퀄컴과 제휴하여 특정 용도용 프로세서와 테스트 체계를 공동 설계하고 있습니다. 버라이즌의 프라이빗 네트워크 프로그램은 이 지역이 저지연 자동차용 워크로드를 확장할 준비가 되어 있음을 보여줍니다. 주 및 연방 차원의 재정 지원 조치는 엣지 랩과 파일럿 회랑의 정착을 더욱 촉진하고 있습니다. 아시아태평양은 2031년까지 연평균 성장률(CAGR) 24.12%를 나타낼 것으로 예측됩니다. 중국은 전기차에 대한 보조금, 방대한 소비자 수, 도시 주도의 스마트 교통 계획을 결합하여 자동차 시장에서 엣지 컴퓨팅을 위한 비옥한 토대를 마련하고 있습니다. 화웨이가 내몽골에서 100대의 자율주행형 5G-A 광산 트럭을 도입한 것은 가혹한 환경 하에서의 산업용 등급 배포를 여실히 보여주고 있습니다. 일본과 한국은 첨단 반도체 노드를 공급하는 한편, 인도는 전 세계 OEM을 위한 차량용 소프트웨어를 개발하는 인재 허브로서의 입지를 확고히 하고 있습니다. 유럽은 고급 자동차 브랜드와 엄격한 안전 법규를 통해 성장세를 유지하고 있습니다. UNECE WP.29 및 GDPR(EU 개인정보보호규정)은 엄격한 사이버 보안과 데이터 현지화를 의무화하여 엣지 솔루션의 기준을 높이고 있습니다. 보쉬와 마이크로소프트는 현재 ISO 26262 기능 안전 표준을 준수하는 생성형 AI 툴체인을 공동 개발하고 있습니다. EU 전역에 걸친 디지털 전략과 국경을 초월한 5G 회랑을 통해 독일, 오스트리아, 이탈리아 간 자율주행 트럭의 원활한 로밍이 가능해집니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTHAccording to Mordor Intelligence, the edge computing in automotive market size in 2026 is estimated at USD 15.17 billion, growing from 2025 value of USD 12.7 billion with 2031 projections showing USD 36.97 billion, growing at 19.48% CAGR over 2026-2031.
This report is Segmented by Component (Hardware, Software and More), Deployment Model (On-Board Vehicle Edge, Network/MEC Edge and More), Vehicle Type (Passenger Cars, Light Commercial Vehicles and More), Application (Connected Cars (Infotainment and OTA), ADAS and Autonomous Driving, Traffic Management and V2I, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Edge Computing In Automotive Market Trends and Insights
Mainstream - Proliferation of Vehicle Sensors and 5G Rollouts
Modern cars host up to 200 sensors that stream 25 GB of data per hour, a volume that overwhelms legacy architectures. 5G radio access now delivers sub-10 ms latency, demonstrated when Deutsche Telekom and Nokia cut V2X delays below 30 ms in the Car2MEC trials. Carmakers therefore embed local processing to classify, compress, and react to hazards before forwarding essential insights to the cloud. The outcome is a decisive tilt from central to distributed compute, which underpins rising hardware demand and reinforces the edge computing in automotive market's rapid CAGR.
Mainstream - OEM Shift Toward Software-Defined Vehicles
Manufacturers rewrite their business models around code updates and digital features. Bosch and Volkswagen's Cariad arm assigned 1,000 engineers to co-develop AI platforms slated for 2025 vehicles. Always-connected cars now require secure, over-the-air software pipes plus high-performance in-vehicle compute to validate and roll back code safely. These workflows enlarge service revenue pools and elevate the edge computing in automotive market as a core monetization pillar.
Mainstream - High Upfront Infrastructure Capex
Complete edge stacks bundle compute nodes, private 5G, and hardened security, a combination that pushed Verizon and Audi's German test site budget past USD 10 million. Capital intensity deters smaller OEMs and stalls projects in price-sensitive regions. Consequently, deployments prioritize functions that yield immediate safety payback while broader optimization waits for cost curves to drop.
Other drivers and restraints analyzed in the detailed report include:
- Under-the-radar - Curb-side Micro-edge Nodes by Cities
- Under-the-radar - Battery-friendly In-vehicle AI Accelerators Cut TCO
- Mainstream - Cyber-security and Data-sovereignty Risks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware captured 43.45% revenue in 2025, underscoring the essential role of rugged processors, AI accelerators, and thermal solutions inside vehicles. This slice translates to the largest edge computing in automotive market share thanks to silicon that tolerates vibration and 125 °C ambient. In dollar terms the edge computing in automotive market size for hardware will still climb, yet services enjoy a steeper 24.89% CAGR as integrators manage over-the-air rollouts for mixed global fleets. Automakers gravitate toward turnkey services because the learning curve for functional safety, cybersecurity, and real-time scheduling is steep. Suppliers such as Intel-after absorbing Silicon Mobility-bundle chips with middleware and long-term update contracts. The shift channels margin away from pure-play hardware and pushes platform vendors to partner with cloud operators for joint lifecycle offerings, reinforcing service momentum.
On-board compute retained 46.02% of 2025 revenue, underlining OEM confidence in self-contained reliability. Still, infrastructure nodes are tracking a 21.55% CAGR as smart-city budgets finance roadside boxes that extend awareness beyond a single car. This growth enlarges the edge computing in automotive market size for public edge assets and invites telecom carriers and municipalities into revenue-sharing schemes. Hybrid topologies are emerging whereby vehicle, network, and curb-side processors cooperate. The Automotive Edge Computing Consortium promotes such split-compute frameworks to optimize cost and latency. Carmakers must now certify software across heterogeneous domains, elevating interoperability toolchains and driving standards activity.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Deployment Model
- On-board Vehicle Edge
- Network/MEC Edge
- Infrastructure Edge (Road-side and Smart City)
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Off-highway and Specialty Vehicles
- By Application
- Connected Cars (Infotainment and OTA)
- ADAS and Autonomous Driving
- Traffic Management and V2I
- Fleet and Logistics Optimisation
- Smart Cities Services
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Colombia
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Indonesia
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Israel
- Africa
- South Africa
- Nigeria
- Egypt
- Middle East
- North America
Geography Analysis
North America led with 34.95% revenue in 2025, supported by early 5G rollouts, orderly spectrum policy, and tight OEM-tech partnerships. Tesla, General Motors, and Ford pair with Intel, NVIDIA, and Qualcomm to co-design application-specific processors and testing regimes. Verizon's private-network program underscores the region's readiness to scale low-latency automotive workloads. Funding incentives at state and federal levels further anchor edge labs and pilot corridors. Asia-Pacific is forecast to register a 24.12% CAGR to 2031. China merges electric-vehicle subsidies, vast consumer volumes, and city-led smart-transport schemes, creating a fertile edge computing in automotive market. Huawei's launch of 100 autonomous 5G-A mine trucks in Inner Mongolia illustrates industrial-grade deployment under harsh conditions. Japan and South Korea supply advanced semiconductor nodes, while India positions talent hubs that write in-vehicle software for global OEMs. Europe maintains momentum through premium marques and strict safety law. UNECE WP.29 and GDPR force rigorous cybersecurity and data-localization, raising the baseline for edge solutions. Bosch and Microsoft now co-produce generative-AI toolchains that comply with ISO 26262 functional-safety standards. Pan-EU digital strategies and cross-border 5G corridors allow continuous roaming for autonomous trucks between Germany, Austria, and Italy.
- Amazon Web Services, Inc.
- Cisco Systems, Inc.
- Huawei Technologies Co., Ltd.
- Hewlett Packard Enterprise Development LP
- IBM Corporation
- Intel Corporation
- NVIDIA Corporation
- Qualcomm Technologies, Inc.
- Ericsson AB
- Siemens AG
- Robert Bosch GmbH
- Continental AG
- Verizon Communications Inc.
- Vodafone Group Plc
- Belden Inc.
- Digi International Inc.
- Litmus Automation Inc.
- Azion Technologies Ltd.
- Altran Technologies SA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Mainstream Proliferation of Vehicle Sensors And 5G Rollouts
- 4.2.2 Mainstream OEM Shift Toward Software-Defined Vehicles
- 4.2.3 Mainstream Regulatory Support for V2X Safety Mandates
- 4.2.4 Mainstream Rising IoT Data Traffic Per Car
- 4.2.5 Deployment of Curb-Side Micro-Edge Nodes by Cities
- 4.2.6 Battery-Friendly In-Vehicle AI Accelerators Cut TCO
- 4.3 Market Restraints
- 4.3.1 Mainstream High Upfront Infrastructure Capex
- 4.3.2 Mainstream Cyber-Security and Data-Sovereignty Risks
- 4.3.3 Scarcity of Automotive-Grade Edge Silicon Supply
- 4.3.4 Fragmented MEC Interoperability Standards
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers/Consumers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Deployment Model
- 5.2.1 On-board Vehicle Edge
- 5.2.2 Network/MEC Edge
- 5.2.3 Infrastructure Edge (Road-side and Smart City)
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Light Commercial Vehicles
- 5.3.3 Heavy Commercial Vehicles
- 5.3.4 Off-highway and Specialty Vehicles
- 5.4 By Application
- 5.4.1 Connected Cars (Infotainment and OTA)
- 5.4.2 ADAS and Autonomous Driving
- 5.4.3 Traffic Management and V2I
- 5.4.4 Fleet and Logistics Optimisation
- 5.4.5 Smart Cities Services
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Colombia
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Indonesia
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Israel
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amazon Web Services, Inc.
- 6.4.2 Cisco Systems, Inc.
- 6.4.3 Huawei Technologies Co., Ltd.
- 6.4.4 Hewlett Packard Enterprise Development LP
- 6.4.5 IBM Corporation
- 6.4.6 Intel Corporation
- 6.4.7 NVIDIA Corporation
- 6.4.8 Qualcomm Technologies, Inc.
- 6.4.9 Ericsson AB
- 6.4.10 Siemens AG
- 6.4.11 Robert Bosch GmbH
- 6.4.12 Continental AG
- 6.4.13 Verizon Communications Inc.
- 6.4.14 Vodafone Group Plc
- 6.4.15 Belden Inc.
- 6.4.16 Digi International Inc.
- 6.4.17 Litmus Automation Inc.
- 6.4.18 Azion Technologies Ltd.
- 6.4.19 Altran Technologies SA
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment