|
시장보고서
상품코드
2123986
요검사 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Urinalysis - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
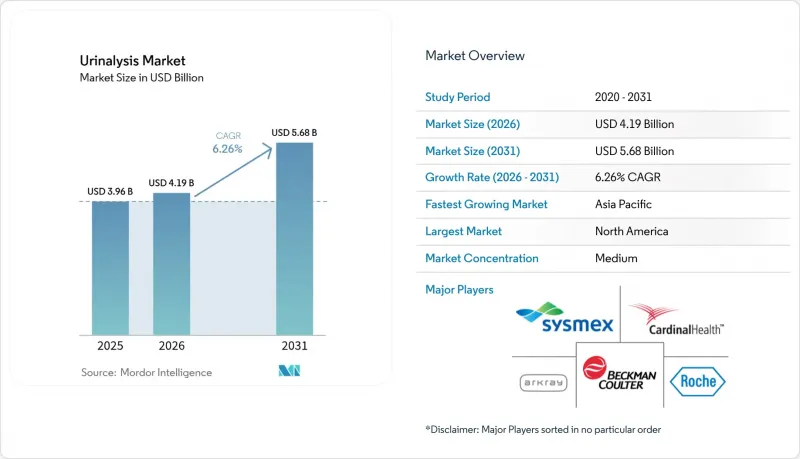
에 의하면, 요검사 시장 규모는 2025년에 39억 6,000만 달러로 평가되었고 2026년 41억 9,000만 달러에서 2031년까지 56억 8,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.26%를 나타낼 전망입니다.
본 보고서는 제품별(소모품, 장비(자동 분석기, 반자동 분석기), 현장진단(POC) 장비) ,검사 유형별(생화학적 요검사, 침전물 분석, 임신·불임 검사 등), 최종 사용자별(병원 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 요검사 시장 동향 및 인사이트
만성 신장 질환 유병률 증가
세계적으로 약 7억 8,800만 명이 만성 신장 질환(CKD)을 앓고 있으며, 2024년에는 미국 성인의 14%가 이 질환으로 진단받았습니다. 따라서 당뇨병 환자나 고혈압 환자에 대해서는 분기별 또는 반년에 한 번씩 단백뇨 및 혈뇨 선별 검사를 실시하는 것이 표준이 되었습니다. 병원과 진단 체인은 시간당 240-480개의 검체를 처리할 수 있는 분석 기기에 의존하고 있으며, 이를 통해 인건비를 절감하고 당일 내 임상적 개입을 가능하게 하고 있습니다. 인도의 2급 및 3급 도시에서 ‘허브 앤 스포크(hub-and-spoke)’ 방식이 급속히 확대됨에 따라 집중 검사 시설로 유입되는 검체 수가 더욱 증가하고 있습니다. 의무적인 후속 검사가 실시될 때마다 시약에 대한 지속적인 수익은 증가하지만, 공적 보험 기관이 검사당 요금을 고정하고 있는 경우, 환급액에 상한선이 설정된다는 과제에 직면하고 있습니다.
당뇨병 환자 수 증가로 인해 정기적인 요검사가 필요해지고 있습니다.
국제당뇨병연맹(IDF)에 따르면, 2024년 성인 당뇨병 환자 수는 5억 3,700만 명이며, 2030년까지 6억 4,000만 명을 넘어설 것으로 예측됩니다. 요검사는 당뇨병성 신증의 초기 단계에서 미량 알부민뇨를 검출하는 동시에, 혈당 조절이 불충분한 환자의 당뇨를 모니터링합니다. 공적 보험 기관은 말기 합병증을 예방하기 위한 선별 검사를 권장하고 있지만, 인도의 ‘아유슈만 바라트’ 프로그램에서는 민간 병원에 대한 보험 지급액이 불충분하기 때문에 저비용 약국이나 가정용 검사 키트로의 전환이 진행되고 있습니다. 혈당 및 알부민 측정용 스트립과 블루투스 지원 리더기를 결합한 제품을 제공하는 업체들은 남아시아 및 중동 전역의 지역 보건 센터에서 계약을 수주하고 있습니다.
신흥 시장의 보상액 격차
공적 보험 프로그램의 경우, 시약 원가보다 낮은 환급액이 책정되는 경우가 많아 민간 투자를 저해하고 있습니다. 2025년 마하라슈트라 주에서 실시된 조사에 따르면, 민간 병원의 불과 13%만이 ‘아유슈만 바라트’의 환급률을 수용하고 있어, 환자들은 공공 의료기관을 이용하거나 본인 부담금을 지불할 수밖에 없는 실정입니다. WHO는 저·중소득국이 의료 예산의 5% 미만을 진단 검사에 지출하고 있다고 지적하고 있습니다. 공급업체들은 저비용 검사 스트립으로의 전환을 추진하고 있지만, 이익률은 여전히 낮고 유통은 여전히 세분화된 상태입니다.
부문 분석
2025년, 요검사 시장 매출의 49.82%를 소모품이 차지하고 있으며, 특정 분석 기기에 맞추어 보정된 독자 사양의 시약 스트립으로 인한 락인 효과가 두드러지고 있습니다. 자동 분석기는 핵심 검사실을 위한 완전 자동 워크셀과 하루 60-240건의 검사를 처리하는 반자동 탁상형 기기로 분류됩니다. 요검사용 소모품 시장은 집중 조달에 따른 가격 압박으로 검사당 이익률이 압박받고 있음에도 불구하고 꾸준한 성장이 예상됩니다. 2024년 입찰에서 중국 병원들은 완전 자동 분석기에 평균 5만 3,300위안(7,400달러)을 지불했으며, 시약 및 서비스 계약이 포함된 국내 브랜드를 선호하는 것으로 나타났습니다.
약국 및 재택치료 프로그램에서 스마트폰 연동형 리더기 및 마이크로플루이딕스 카트리지 도입이 확대됨에 따라, 포인트 오브 케어(POC) 기기는 2031년까지 연평균 성장률(CAGR) 7.06%로 성장할 것으로 전망됩니다. 기기 부문의 매출은 스트립 분석과 디지털 현미경, AI 기반 입자 인식을 통합한 ‘CLINITEK Novus’ 및 ‘DxU Iris’ 플랫폼에 대한 설비 투자의 혜택을 받고 있습니다. 반자동 분석 장비는 예산이 제한적인 인도와 라틴아메리카의 2급 병원에서 여전히 중요한 역할을 하고 있습니다. 동물병원 및 반려동물 병원은 틈새 시장이지만, 반려동물 사육 마릿수가 증가함에 따라 소모품에 대한 수요가 서서히 높아지고 있습니다.
지역별 분석
북미는 확립된 보험 환급 체계와 AI 침전물 분석 플랫폼의 조기 도입으로 인해 2025년 요검사 시장 점유율의 36.78%를 차지했습니다. FDA가 2024년에 발표한 사이버 보안 지침에 따라 510(k) 신청 절차가 명확해졌으며, 제품화가 가속화되었습니다. 인력 부족으로 인해 병원들은 자동화를 추진하고 있으며, 이는 고처리량 분석 장비에 대한 설비 투자와 연동되고 있습니다. 캐나다에서는 주 차원의 선별 검사 정책을 통해 투자가 이루어지고 있는 반면, 멕시코에서는 당뇨병 모니터링에 특화된 민간 검사 기관 체인이 증가하고 있습니다. 보험 환급액 삭감이 수익을 억제하고 있지만, 예방 의료 검사 건수 증가가 가격 하락을 일부 상쇄하고 있습니다.
아시아태평양은 가장 성장세가 두드러지는 지역으로, 2026년부터 2031년까지 연평균 성장률(CAGR) 9.28%가 예상됩니다. 중국의 중앙 집중식 조달로 인해 Youlite, Dirui, Mindray가 제조한 국산 분석기에 대한 수요가 이동하고 있으며, 이들 기업이 제공하는 통합 시약은 2024년 계약액의 73.61%를 차지했습니다. 일본은 성숙한 시장을 유지하고 있으며, 2023년 Eiken Chemical 매출의 11%를 요검사 스트립이 차지했습니다. 또한, 2024년 후생노동성 가이드라인에서는 의료기기로서의 소프트웨어(SaM)에 대한 보험 환급이 지지되고 있습니다. 호주와 한국에서는 견고한 원격의료 인프라를 배경으로 커넥티드 홈 기기의 도입이 급속히 진행되고 있습니다.
유럽은 국민건강보험 제도와 ISO 15189의 시행으로 인해 중요한 시장 점유율을 차지하고 있습니다. 독일과 영국은 자동 분석기 도입을 주도하고 있으나, GDPR(EU 개인정보보호규정)로 인해 클라우드 연결형 기기의 규정 준수 장벽이 높아지고 있습니다. 동유럽의 병원들은 EU 의료 기금 보조금을 통해 현대화가 진행되고 있으나, 예산 제약으로 인해 고성능 분석기의 보급은 제한적입니다. 라틴아메리카 및 중동 및 아프리카는 시장 점유율은 작지만, 민간 병원의 진단 역량이 확대됨에 따라 꾸준한 성장을 보이고 있습니다. 다만, 환율 변동과 보험 환급 제도의 분절화가 지속적인 위험 요인으로 작용하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.07According to Mordor Intelligence, the urinalysis market size was valued at USD 3.96 billion in 2025 and is estimated to grow from USD 4.19 billion in 2026 to reach USD 5.68 billion by 2031, at a CAGR of 6.26% during the forecast period (2026-2031).
This report is Segmented by Product (Consumables, Instruments [Automated Analyzers, Semi-Automated Analyzers], Point-Of-Care Devices), Test Type (Biochemical Urinalysis, Sediment Analysis, Pregnancy & Fertility Testing, and More), End User (Hospitals, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Urinalysis Market Trends and Insights
Rising Prevalence of Chronic Kidney Diseases
Worldwide, an estimated 788 million people live with CKD, and 14% of U.S. adults carried a diagnosis in 2024. Quarterly or semi-annual urine screening for proteinuria and hematuria has therefore become standard for diabetics and hypertensives. Hospitals and diagnostic chains rely on analyzers that process 240-480 samples per hour, reducing labor costs and enabling same-day clinical intervention. Rapid hub-and-spoke expansion in India's tier-2 and tier-3 cities channels additional volumes to centralized labs. Recurring reagent revenue rises with every mandated follow-up but faces reimbursement caps when public insurers fix per-test fees.
Growing Diabetic Population Necessitating Routine Urine Testing
The International Diabetes Federation counted 537 million adults with diabetes in 2024 and expects the figure to top 640 million by 2030. Urinalysis detects microalbuminuria early in diabetic nephropathy and monitors glycosuria in uncontrolled patients. Public insurers favor preventive testing to avoid late-stage complications, yet India's Ayushman Bharat program under-reimburses private hospitals, prompting a shift toward lower-cost pharmacy and home testing. Vendors pairing glucose and albumin strips with Bluetooth readers have secured contracts in community health centers across South Asia and the Middle East.
Reimbursement Gaps Across Emerging Markets
Public insurance programs often reimburse below the cost of reagents, discouraging private investment. Only 13% of private hospitals in a 2025 Maharashtra survey accepted Ayushman Bharat rates, pushing patients toward public facilities or cash payments. WHO noted that low- and middle-income countries spend less than 5% of their health budgets on diagnostics. Suppliers pivot to low-cost strips, but margins remain tight and distribution fragmented.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Automated, High-Throughput Platforms
- Integration of AI-Powered Image Analysis for Sediment Examination
- Shortage of Skilled Laboratory Technicians
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Consumables generated 49.82% of urinalysis market revenue in 2025, underscoring the lock-in created by proprietary reagent strips calibrated for specific analyzers. Automated analyzers split into fully automatic workcells serving core laboratories and semi-automatic benchtop units addressing 60-240 daily tests. The urinalysis market for consumables is projected to grow steadily, even as pricing pressure from centralized procurement compresses per-test margins. Hospitals in China paid an average of RMB 53,300 (USD 7,400) for fully automatic analyzers during 2024 tenders, favoring domestic brands that bundled reagents and service contracts.
Point-of-care devices grow at a 7.06% CAGR through 2031 as pharmacies and home-health programs adopt smartphone-linked readers and microfluidic cartridges. Instruments segment revenue benefits from capital purchases of CLINITEK Novus and DxU Iris platforms, which integrate strip analysis with digital microscopy and AI particle recognition. Semi-automated analyzers remain relevant in tier-2 hospitals across India and Latin America, where budgets are tight. Veterinary clinics and companion-animal hospitals are a niche but expanding outlet, adding incremental demand for consumables as pet ownership rises.
Complete Report Scope:
- By Product
- Consumables (Reagents & Strips)
- Instruments
- Automated Analyzers
- Semi-Automated Analyzers
- Point-of-Care Devices
- By Test Type
- Biochemical Urinalysis
- Sediment Analysis
- Pregnancy & Fertility Testing
- Drug-of-Abuse Testing
- Infectious Disease Detection
- By End User
- Hospitals
- Diagnostic Laboratories
- Home-Care Settings
- Academic & Research Institutes
- Veterinary Clinics
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 36.78% of the urinalysis market share in 2025, owing to established reimbursement pathways and early uptake of AI sediment platforms. The FDA's 2024 cybersecurity guidance clarified 510(k) routes, speeding commercial launches. Workforce shortages drive hospitals to automate, aligning with capital spend on high-throughput analyzers. Canada invests through provincial screening initiatives, whereas Mexico increases private-sector laboratory chains focused on diabetes monitoring. Reimbursement cuts temper revenue, but rising preventive-health volumes partly offset price erosion.
Asia-Pacific is the fastest-growing region, with a 9.28% CAGR projected for 2026-2031. China's centralized tenders shifted volumes toward domestically produced analyzers from Youlite, Dirui, and Mindray, whose integrated reagent offers secured 73.61% of 2024 contract value. Japan maintains a mature market with 11% of Eiken Chemical's 2023 revenue from urinalysis strips, and the 2024 MoH guidebook supports software-as-a-medical-device reimbursement. Australia and South Korea are quickly adopting connected home devices due to their robust telemedicine infrastructure.
Europe holds a significant stake thanks to universal coverage and the enforcement of ISO 15189. Germany and the United Kingdom lead automated-analyzer uptake, while GDPR raises compliance hurdles for cloud-connected devices. Eastern European hospitals modernize under EU health-fund grants, yet constrained budgets limit premium analyzer penetration. Latin America and the Middle East & Africa contribute smaller portions but register steady growth as private hospitals expand diagnostics capacity, although currency volatility and fragmented reimbursement pose ongoing risks.
- Abbott Laboratories
- Acon Laboratories
- Arkray
- Bio-Rad Laboratories
- Beckton Dickinson
- Cardinal Health
- Danaher
- DIRUI Industrial Co., Ltd.
- EKF Diagnostics Holdings plc
- Roche
- HORIBA
- IDEXX
- Medica Corporation
- Mindray Bio-Medical Electronics Co., Ltd.
- QuidelOrtho
- Shenzhen Mindel Medical Co., Ltd.
- Siemens Healthineers
- Sysmex
- Thermo Fisher Scientific
- Trinity Biotech plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence of Chronic Kidney Diseases
- 4.2.2 Growing Diabetic Population Necessitating Routine Urine Testing
- 4.2.3 Shift Toward Automated, High-Throughput Urinalysis Platforms
- 4.2.4 Integration of AI-Powered Image Analysis for Sediment Examination
- 4.2.5 Expansion of Self-Testing & Tele-Urinalysis Kits
- 4.2.6 Increasing Adoption of Urinary Biomarkers for Oncology Screening
- 4.3 Market Restraints
- 4.3.1 Reimbursement Gaps Across Emerging Markets
- 4.3.2 Shortage of Skilled Laboratory Technicians
- 4.3.3 Data-Privacy Concerns in At-Home Connected Devices
- 4.3.4 Supply-Chain Vulnerability in Reagent-Grade Chemicals
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Product
- 5.1.1 Consumables (Reagents & Strips)
- 5.1.2 Instruments
- 5.1.2.1 Automated Analyzers
- 5.1.2.2 Semi-Automated Analyzers
- 5.1.3 Point-of-Care Devices
- 5.2 By Test Type
- 5.2.1 Biochemical Urinalysis
- 5.2.2 Sediment Analysis
- 5.2.3 Pregnancy & Fertility Testing
- 5.2.4 Drug-of-Abuse Testing
- 5.2.5 Infectious Disease Detection
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Diagnostic Laboratories
- 5.3.3 Home-Care Settings
- 5.3.4 Academic & Research Institutes
- 5.3.5 Veterinary Clinics
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 ACON Laboratories, Inc.
- 6.3.3 ARKRAY Inc.
- 6.3.4 Bio-Rad Laboratories Inc.
- 6.3.5 Beckman Coulter Inc.
- 6.3.6 Cardinal Health, Inc.
- 6.3.7 Danaher Corporation
- 6.3.8 DIRUI Industrial Co., Ltd.
- 6.3.9 EKF Diagnostics Holdings plc
- 6.3.10 F. Hoffmann-La Roche Ltd
- 6.3.11 HORIBA, Ltd.
- 6.3.12 Idexx Laboratories, Inc.
- 6.3.13 Medica Corporation
- 6.3.14 Mindray Bio-Medical Electronics Co., Ltd.
- 6.3.15 QuidelOrtho Corporation
- 6.3.16 Shenzhen Mindel Medical Co., Ltd.
- 6.3.17 Siemens Healthineers AG
- 6.3.18 Sysmex Corporation
- 6.3.19 Thermo Fisher Scientific Inc.
- 6.3.20 Trinity Biotech plc
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment