

|
시장보고서
상품코드
2124062
피하 피임 임플란트 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Subdermal Contraceptive Implants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
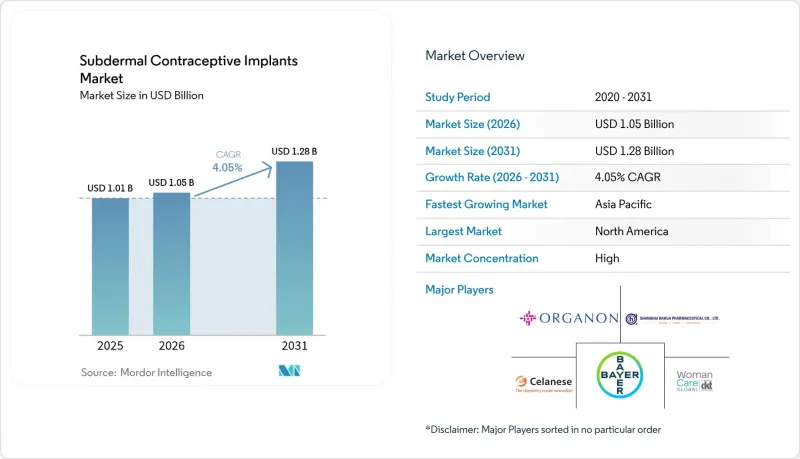
에 의하면, 피하 피임 임플란트 시장 규모는 2025년에 10억 1,000만 달러로 평가되었고, 2026년 10억 5,000만 달러에서 2031년까지 12억 8,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.05%를 나타낼 전망입니다.
본 보고서는 유형별(싱글로드형 임플란트, 더블로드형 임플란트, 기타), 호르몬별(에토노게스트렐, 레보노르게스트렐), 최종 사용자별(병원, 산부인과 클리닉, 가족계획·생식건강센터 등), 지역별(북미, 유럽,아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 피하 피임 임플란트 시장 동향 및 인사이트
예기치 않은 임신율 상승과 LARC에 대한 수요
2024년 전 세계 의도파관 않은 임신 건수는 총 1억 2,100만 건에 달했고, 전체 임신의 48%를 차지하고 있으며, 저·중소득 국가에서는 여전히 2억 5,700만 명의 여성이 현대적인 피임법을 이용하지 못하고 있습니다. 장기 작용형 가역 피임법(LARC)은 이미 현대적 피임법 이용의 21%를 차지하고 있으며, 2019년의 16%에서 증가했습니다. 이는 이용자들이 매일 복용해야 하는 부담이 없는 ‘한 번 삽입하면 그 후로는 신경 쓸 필요가 없는’ 피임법을 선호하기 때문입니다. 각국의 보건부는 현재,피임 예산의 최대 50%를 임플란트나 자궁 내 피임 장치(IUD)에 할당하고 있으며, 기부 가격 15달러인 임플란트 1개가 1회당 1.50달러인 경구 피임약을 36주기 분 복용하는 것보다 3년 동안 더 많은 임신을 예방할 수 있다는 점을 인식하고 있습니다. 사춘기 청소년과 미산부 사이에서 이용이 확대되고 있어, 기존의 임상적 상식에 변화를 가져오는 동시에 잠재적 이용자층을 넓혀가고 있습니다. 이러한 동향이 예측 기간 및 그 이후에도 피하 피임 임플란트 시장에 대한 지속적인 수요를 뒷받침하고 있습니다.
정부의 가족 계획 정책 및 보조금
인도의 ‘미션 파리발 비카스(Mission Parivar Vikas)’는 5만 명의 보조 조산사를 양성하고 이용자 부담을 면제함으로써, 2024 회계연도에 210만 건의 임플란트 삽입을 달성했습니다. 인도네시아의 보편적 의료 보장(UHC)에서는 의료 제공업체가 LARC(장기 작용형 피임법)를 선택하도록 장려하기 위해 1회 삽입당 25달러를 상환하고 있으며, 이는 주사제의 상환액의 3배에 해당합니다. 그 결과, 2024년에는 180만 개의 임플란트가 조달되었습니다. 필리핀은 아시아개발은행으로부터 1억 2,000만 달러의 대출을 확보하여 지방 보건 시설을 통해 150만 개의 임플란트를 배포하고, 2028년까지 현대적 피임법의 보급률을 10퍼센트 포인트 높이는 것을 목표로 하고 있습니다. 이러한 노력은 제조업체의 투자 회수 기간을 단축하고 현지 생산을 촉진함으로써 피하 피임 임플란트 시장의 중기적 성장을 뒷받침하고 있습니다.
부작용에 대한 우려 및 소송
3,200건의 상해 청구를 포함한 집단 소송에 따라, 오르가논과 바이엘은 2024년에 합의금으로 1억 5,000만 달러를 충당금으로 계상했습니다. 영국 규제 당국은 현재 48시간 이내에 초음파 검사를 통해 확인하도록 의무화하고 있으며, 이로 인해 건당 50달러의 규정 준수 비용이 추가로 발생하고 있습니다. 의료 과실 보험료의 급등으로 인해 미국 12개 주의 외래 진료 센터가 임플란트 서비스 제공을 중단할 수밖에 없게 되었으며, 지방 지역의 대기 시간은 8주까지 늘어났습니다. 개선된 어플리케이터 덕분에 위치 이상 사례는 획기적으로 감소했으나, 진행 중인 소송이 의료 제공업체의 의욕을 꺾고 있어 피하 피임 임플란트 시장의 연평균 성장률(CAGR)에 큰 부담으로 작용하고 있습니다.
부문 분석
더블 로드형 레보노르게스트렐 이식형 피임 기구는 2031년까지 연평균 성장률(CAGR) 5.09%로 확대될 것으로 예측되며, 이 지표에서 피하 피임 임플란트 시장 전체 규모를 상회하는 성장이 예상됩니다. 이러한 시스템은 단일 막대형 제네릭 제품의 가격이 12-15달러인 반면, 조달 입찰 단가가 8-10달러라는 장점이 있습니다. 상하이 다화(Shanghai Dahua)의 ‘Sino-implant(II)’는 2024년에 나이지리아와 450만 개 규모의 계약을 체결하며, 예산이 제한된 환경에서도 성장세를 보이고 있음을 보여주었습니다. 단일 로드형 에토노게스트렐 제제는 여전히 프리미엄 부문을 지배하고 있으며, 오르가논의 확립된 교육 네트워크와 의료 과실 위험 완화 조치 덕분에 2025년에도 66.82%의 시장 점유율을 유지하고 있습니다. 2027년 이후 바이오시밀러가 출시되면, 로드 형태 간의 가격 차이는 축소될 것이며, 편의성과 관련된 특징이 피하 피임 임플란트 시장 내경쟁 구도를 재편할 가능성이 있습니다.
비용과 성능의 상충 관계는 시술의 물류에도 영향을 미치고 있습니다. 로드 2개를 삽입하려면 4mm의 절개와 더 긴 시술 시간이 필요하며, 이로 인해 감염 위험이 약간 높아집니다. 그러나 공공 프로그램에서는 미미한 편의성보다 예산에 미치는 영향을 우선시하고 있으므로, 입찰 시장에서 지배적인 지위는 앞으로도 유지될 전망입니다. 벤처 캐피털로부터 자금을 지원받고 있는 생분해성 폴리머 임플란트는 현재 시장 점유율이 2% 미만이지만, 2024년에 4,500만 달러의 자금 조달에 성공하여 향후 제거가 필요 없는 플랫폼으로의 전환이 진행될 것임을 시사하고 있습니다. 이러한 요인들이 종합적으로 조달 결정을 이끌어내고, 피하 피임 임플란트 업계의 다양한 성장 경로를 뒷받침할 것입니다.
지역별 분석
북미는 메디케이드 확대 및 민간 보험사의 LARC 본인 부담금 폐지에 힘입어 2025년 매출의 45.08%를 차지했습니다. 현재 Tier 1 품질 지표로 자리 잡은 산후 즉시 시술 프로토콜에 따라, 2024년 미국의 이식 건수는 180만 건에 달했으며, 이는 가임기 여성 1,000명당 11건에 해당합니다. 2027년부터 특허 만료에 따라 바이오시밀러가 등장함에 따라 평균 판매 가격은 하락할 전망이지만, 본인 부담금 감소가 이용 증가를 촉진하여 피하 피임 임플란트 시장 전체의 규모를 확대시킬 것입니다.
아시아태평양은 가장 성장세가 두드러지는 지역으로, 2031년까지 연평균 성장률(CAGR)은 7.13%로 예측됩니다. 이는 인도, 인도네시아, 필리핀이 주도하는 것으로, 이 3개국의 총 수요는 2028년까지 650만 개를 넘어설 전망입니다. 중국은 2024년에 레보노르게스트렐의 국내 생산을 승인했으며, 2027년까지 연간 50만 건의 이식을 목표로 하고 있습니다. 또한 2020년 이후 농촌 지역 여성들의 현대적 피임법 이용률이 12% 감소한 상황을 개선하는 것을 목표로 하고 있습니다. 급속한 도시화, 스마트폰 보급, 그리고 정부 보조금 등이 맞물려 시장 침투를 가속화하고 있으며, 아시아태평양이 전 세계 피하 피임 임플란트 시장 점유율 구도를 재편하는 데 있어 매우 중요한 역할을 하고 있음이 부각되고 있습니다.
미국에서는 2024 회계연도 임플란트 이식 건수가 42만 건으로 정체되어 있어, 시장이 성숙기에 접어들었음을 알 수 있습니다. 그렇지만 소송을 계기로 안전 기준이 강화됨에 따라, 이식 현황을 추적하는 디지털 도구에 새로운 기회가 생길 가능성이 있습니다. 중동 및 아프리카을 합치면 2025년 출하량의 12%를 차지하며, 에티오피아,케냐, 나이지리아, 탄자니아에서 유엔인구기금(UNFPA) 및 미국국제개발처(USAID)의 조달을 배경으로 연평균 성장률(CAGR) 6.2%로 성장할 전망입니다. 이들 시장에서는 미충족 수요가 25%를 초과하고 있습니다. 매출 점유율 8%를 차지하는 남미는 재정 긴축에 직면해 있습니다. 브라질에서는 예산이 백신 접종 캠페인에 배정됨에 따라 2024년 공공 공급량이 9% 감소했으며, 이는 피하 피임 임플란트 업계가 거시경제에 얼마나 민감한지를 여실히 보여주고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the subdermal contraceptive implants market size was valued at USD 1.01 billion in 2025 and is estimated to grow from USD 1.05 billion in 2026 to reach USD 1.28 billion by 2031, at a CAGR of 4.05% during the forecast period (2026-2031).
This report is Segmented by Type (Single-Rod Implants, Double-Rod Implants, Others), Hormone (Etonogestrel, Levonorgestrel), End User (Hospitals, Gynecology & Obstetrics Clinics, Family Planning & Reproductive Health Centers, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Subdermal Contraceptive Implants Market Trends and Insights
Rising Unintended Pregnancy Rates & Demand for LARC
Global unintended pregnancies totaled 121 million in 2024, representing 48% of all pregnancies, and 257 million women in low- and middle-income countries still lack access to modern methods. Long-acting reversible options already account for 21% of modern method use, up from 16% in 2019, because users prefer "set-and-forget" protection without daily adherence burdens. Ministries of health now channel up to 50% of contraceptive budgets to implants and intrauterine devices, recognizing that a single USD 15 donor-priced implant averts more pregnancies over three years than 36 cycles of oral pills costing USD 1.50 each. Uptake among adolescents and women with no prior births is rising, challenging earlier clinical norms and expanding the overall addressable pool. These dynamics underpin enduring demand for the subdermal contraceptive implants market during and beyond the forecast horizon.
Favorable Government Family-Planning Initiatives & Subsidies
India's Mission Parivar Vikas trained 50,000 auxiliary nurse midwives and achieved 2.1 million insertions in fiscal 2024 after waiving user fees. Indonesia's universal health coverage reimburses USD 25 per insertion, triple the rate for injectables, to nudge providers toward LARC, resulting in 1.8 million implants procured in 2024. The Philippines secured USD 120 million in Asian Development Bank financing to distribute 1.5 million implants through rural health units, aiming to increase modern prevalence by 10 percentage points by 2028. These initiatives shorten manufacturers' payback periods and spur localized production, thereby fueling medium-term growth in the subdermal contraceptive implants market.
Adverse-Event Concerns & Litigation
Consolidated lawsuits covering 3,200 injury claims prompted Organon and Bayer to reserve USD 150 million for settlements in 2024. The U.K. regulator now requires ultrasound confirmation within 48 hours, adding USD 50 compliance cost per case. Rising malpractice premiums forced 12 U.S. states' ambulatory centers to discontinue implant services, lengthening rural wait times to eight weeks. Although redesigned applicators cut malposition dramatically, ongoing litigation tempers provider enthusiasm and weighs on the subdermal contraceptive implants market CAGR.
Other drivers and restraints analyzed in the detailed report include:
- Superior Efficacy & Cost-Effectiveness of Implants
- Miniaturized Ultra-Thin Single-Insertion Devices
- High Upfront Cost in Out-of-Pocket Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Double-rod levonorgestrel implants are projected to expand at a 5.09% CAGR through 2031, outpacing the overall subdermal contraceptive implants market size for this metric. These systems benefit from unit prices of USD 8-10 in donor tenders, versus USD 12-15 for single-rod generics. Shanghai Dahua's Sino-implant (II) secured a 4.5-million-unit contract with Nigeria in 2024, demonstrating momentum in budget-constrained settings. Single-rod etonogestrel devices still dominate premium segments, maintaining 66.82% market share in 2025 owing to Organon's entrenched training network and malpractice offsets. As biosimilars launch post-2027, price gaps between rod formats will narrow, and convenience features could re-shape the competitive hierarchy within the subdermal contraceptive implants market.
The cost-performance trade-off also influences procedural logistics: double-rod insertion requires a 4-millimeter incision and longer chair time, which mildly elevates infection risk. Yet public programs prioritize budget impact over marginal convenience, ensuring continued tender dominance. Venture-backed biodegradable polymer implants, currently under 2% share, attracted USD 45 million in 2024 funding, hinting at a future pivot toward removal-free platforms. Collectively, these factors will guide procurement decisions and sustain diversified growth avenues within the subdermal contraceptive implants industry.
Complete Report Scope:
- By Type
- Single-Rod Implants
- Double-Rod Implants
- Others
- By Hormone
- Etonogestrel
- Levonorgestrel
- By End User
- Hospitals
- Gynecology & Obstetrics Clinics
- Family Planning & Reproductive Health Centers
- Ambulatory Surgical Centers
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 45.08% of 2025 revenue, buoyed by Medicaid expansion and commercial insurers' removal of cost-sharing for LARC. Immediate postpartum protocols, now a Tier 1 quality metric, lifted U.S. insertions to 1.8 million in 2024, equal to 11 implants per 1,000 women of reproductive age. Patent cliffs from 2027 will invite biosimilars, likely trimming average selling prices but boosting overall subdermal contraceptive implants market size as lower out-of-pocket costs spark incremental uptake.
Asia-Pacific is the fastest-growing region, projected at a 7.13% CAGR to 2031, driven by India, Indonesia, and the Philippines, where collective demand will top 6.5 million units by 2028. China approved domestic levonorgestrel production in 2024 and targets 500,000 annual insertions by 2027, aiming to reverse a 12% drop in modern method use among rural women since 2020. Rapid urbanization, smartphone penetration, and government subsidies together accelerate market penetration, underscoring Asia-Pacific's pivotal role in reshaping the global subdermal contraceptive implants market share landscape.
The U.K.'s flat volume of 420,000 implants in fiscal 2024 illustrates maturity. Nonetheless, litigation-driven safety mandates could create opportunities for digital insertion-tracking tools. Middle East & Africa combined accounted for 12% of 2025 volume and will grow at a 6.2% CAGR on the back of UNFPA and USAID procurement in Ethiopia, Kenya, Nigeria, and Tanzania, markets where unmet need surpasses 25%. South America, with 8% revenue share, grapples with fiscal austerity; Brazil's public distribution fell 9% in 2024 as budgets pivoted to vaccination campaigns, underscoring macroeconomic sensitivities within the subdermal contraceptive implants industry.
- Afaxys Pharma
- Bayer
- Cipla
- The Cooper Companies
- Celanese
- DKT WomanCare Global
- Endoceutics Inc.
- Exeltis Healthcare
- Gedeon Richter Plc
- Glenmark Pharma Ltd.
- Helm AG
- HLL Lifecare Ltd.
- Hologic
- Lupin
- Meril Life Sciences
- Mylan Laboratories Ltd.
- Organon
- Pregna International Ltd.
- Richter-Helm BioLogics GmbH
- Shanghai Dahua Pharmaceutical Co. Ltd.
- Theramex HQ UK Ltd.
- Viatris
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Unintended Pregnancy Rates & Demand For LARC
- 4.2.2 Favorable Government Family-Planning Initiatives & Subsidies
- 4.2.3 Superior Efficacy & Cost-Effectiveness of Implants
- 4.2.4 Growing NGO Procurement in Emerging Markets
- 4.2.5 Miniaturized Ultra-Thin Single-Insertion Devices
- 4.2.6 Digital Insertion-Tracking Apps Boost Provider Confidence
- 4.3 Market Restraints
- 4.3.1 Adverse-Event Concerns & Litigation
- 4.3.2 High Upfront Cost in Out-of-Pocket Markets
- 4.3.3 Cold-Chain Constraints in Tropical Regions
- 4.3.4 Religious Activist Opposition to Hormonal Contraception
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Type
- 5.1.1 Single-Rod Implants
- 5.1.2 Double-Rod Implants
- 5.1.3 Others
- 5.2 By Hormone
- 5.2.1 Etonogestrel
- 5.2.2 Levonorgestrel
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Gynecology & Obstetrics Clinics
- 5.3.3 Family Planning & Reproductive Health Centers
- 5.3.4 Ambulatory Surgical Centers
- 5.3.5 Other End Users
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 Afaxys Pharma
- 6.3.2 Bayer AG
- 6.3.3 Cipla Ltd.
- 6.3.4 CooperSurgical Inc.
- 6.3.5 Celanese
- 6.3.6 DKT WomanCare Global
- 6.3.7 Endoceutics Inc.
- 6.3.8 Exeltis Healthcare
- 6.3.9 Gedeon Richter Plc
- 6.3.10 Glenmark Pharma Ltd.
- 6.3.11 Helm AG
- 6.3.12 HLL Lifecare Ltd.
- 6.3.13 Hologic Inc.
- 6.3.14 Lupin Ltd.
- 6.3.15 Meril Life Sciences
- 6.3.16 Mylan Laboratories Ltd.
- 6.3.17 Organon & Co.
- 6.3.18 Pregna International Ltd.
- 6.3.19 Richter-Helm BioLogics GmbH
- 6.3.20 Shanghai Dahua Pharmaceutical Co. Ltd.
- 6.3.21 Theramex HQ UK Ltd.
- 6.3.22 Viatris Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


