

|
시장보고서
상품코드
2124111
양극재 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cathode Materials - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
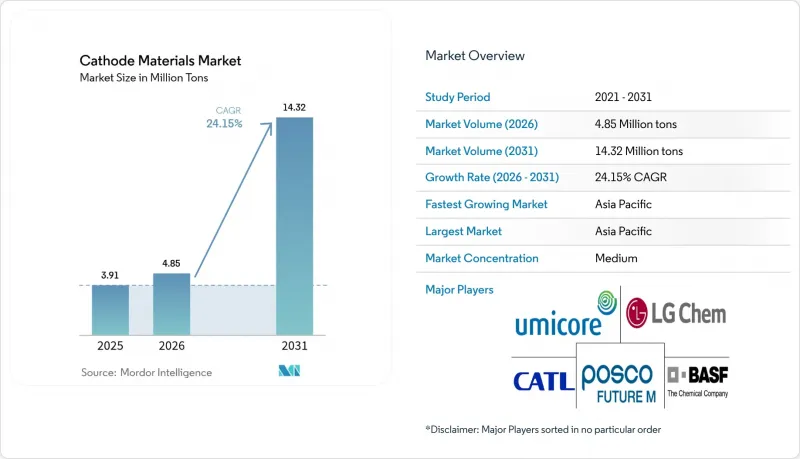
에 의하면, 양극재 시장 규모는 2025년에 391만 톤으로 평가되었고, 2026년 485만 톤에서 2031년까지 1,432만 톤에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 24.15%를 나타낼 전망입니다.
본 보고서는 소재별(인산철 리튬, 산화코발트 리튬, 산화망간 리튬 등), 배터리 유형별(리튬 이온, 납산, 나트륨 이온, 흐름 전지), 최종 사용자 산업별(자동차, 소비자 가전 등), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 수량(톤) 기준으로 제시되어 있습니다.
세계의 양극재 시장 동향 및 인사이트
전기차(EV) 생산 대수의 급증
세계 전기차(EV) 생산 대수는 2025년에 1,380만 대에 도달하였고, 2028년까지 2,200만 대를 넘어설 것으로 예측됩니다. 60kWh 배터리 팩 1개당 8-12kg의 활물질이 사용되므로, 이러한 추세는 양극재 수요를 끌어올리는 요인이 될 것입니다. BYD는 2026년에 400만 대의 플러그인 하이브리드 차량을 생산하여 2024년 생산 대수를 두 배로 늘릴 계획이며, 이는 아시아 전역에서의 규모 확대를 뒷받침하고 있습니다. CATL의 ‘Qilin’과 같은 대용량 셀로의 전환으로 인해 전극 코팅이 두꺼워지면서, 차량 1대당 양극재 탑재량이 증가합니다. 차량의 전동화도 수요를 더욱 끌어올리고 있으며, 그 일례로 UPS가 2025년에 LFP를 탑재한 배송용 밴 1만 대를 발주한 것을 들 수 있습니다. 상용차의 사용 주기는 LFP의 내구성을 활용하기 때문에 양극재 시장에 경기 변동에 좌우되지 않는 안정성을 가져다줍니다.
정부의 인센티브와 배기가스 규제
미국의 ‘인플레이션 억제법’ 제45X조에서는 국산 셀에 대해 1kW시당 10달러, 모듈에 대해 45달러의 보조금이 지급되도록 되어 있으며, 이에 따라 미국 국내에서 총 550GWh의 생산 능력을 갖춘 18곳의 기가팩토리 건설이 발표되었습니다. 유럽에서는 ‘배터리 규정’에 따라 2027년까지 탄소 발자국 공개가 의무화되고, 2030년까지 기준치가 상향 조정될 예정이며, 풍력에너지를 80% 조달하고 있는 유미코어(Umicore)사의 니사 공장 등 재생에너지와 연계된 양극재 공장이 우위를 점하고 있습니다. 중국은 신에너지차 구매세 면제 조치를 2027년까지 연장하여 세계 최대의 전기차 시장에서 수요를 유지하고 있습니다. 인도가 첨단 배터리 생산을 위해 도입한 24억 달러 규모의 ‘생산 연계형 인센티브’는 릴라이언스 인더스트리즈와 라제쉬 익스포트를 유치하며, 남아시아를 양극재 소비의 새로운 거점으로 자리매김하고 있습니다.
중국 내 공급망 집중
2024년, 중국은 전 세계 수산화 리튬의 78%, 황산망간의 93%를 정제했으며, 국내 공급업체가 국내 수요를 우선시할 경우 유럽과 미국의 자동차 제조업체들은 공급 위험에 노출될 것입니다. 포드는 리튬 부족 사태 당시 중국의 전구체 파트너사가 출하처를 변경함에 따라, 2024년 ‘F-150 라이트닝’의 주행 거리 연장 모델 출시를 4개월 연기했습니다. 미국의 국방 평가 보고서는 대만 해협에서 분쟁이 발생할 경우 양극재 공급이 차단될 가능성이 있다고 경고하고 있습니다. 한편, 폭스바겐의 PowerCo와 같은 유럽 기업들은 NMC 전구체의 82%를 중국에 의존하고 있습니다. 연간 20kt 규모의 전구체 공장 건설에는 1억 5,000만 달러와 30개월이 소요되기 때문에 공급원 다각화는 지연되고 있습니다. ‘위구르인 강제노동 방지법’ 준수에 따라 자동차 제조업체들은 다단계 공급망을 추적할 의무를 지게 되어 관리상의 부담이 증가하고 있습니다.
부문 분석
인산철 리튬은 2025년 출하량의 41.10%를 차지한 것으로 평가되었으며, 2031년까지 연평균 24.97%의 성장률을 보일 것으로 전망됩니다. 이는 테슬라와 BYD가 양산 모델에서 코발트와 니켈을 배제한 점을 반영한 것입니다. BYD의 ‘블레이드 팩(Blade Pack)’은 NMC 622와의 에너지 밀도 차이를 15%까지 좁혀, 보다 광범위한 보급을 촉진하고 있습니다. 프리미엄 브랜드에서는 여전히 고니켈 NMC가 채택되고 있습니다. BMW의 ‘Neue Klasse’는 285 Wh/kg의 NMC 811을 채택하고 있으며, 주행 거리 500km가 필수 조건이 되는 분야에서 이 화학 성분을 자리매김하고 있습니다. 리튬·니켈·코발트·알루미늄(LiNiCoAl)은 장거리용 배터리 팩 시장에서 틈새 시장이지만 수익성이 높은 부분을 차지하고 있으나, 코발트 가격 하락으로 인해 그 이익률 우위는 점차 약화되고 있습니다. 이산화납은 여전히 시동용 배터리에 사용되고 있지만, 12V 리튬 배터리로의 대체가 진행됨에 따라 시장 점유율을 내주게 될 것입니다. 가격에 민감한 아시아 시장에서 나트륨 이온 차량이 출시됨에 따라 인산철나트륨의 점유율은 상승하여 양극재 시장의 범위를 넓혀갈 것입니다.
지역별 분석
아시아태평양은 2025년에 시장 점유율의 79.10%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 26.34%로 성장할 전망입니다. 이는 채굴, 가공, 셀 제조에 걸친 깊은 통합을 반영합니다. 중국은 비용 측면에서의 우위와 독자적인 공정 기술을 통해 이 생태계의 핵심을 담당하며, 지속적인 혁신의 속도를 가능하게 하고 있습니다. 한국과 일본은 고정밀 제조 기술과 첨단 소재 배합을 상호 보완적으로 제공함으로써 이 지역의 우위를 강화하고 있습니다. 인도네시아의 150억 달러 규모 제련 투자와 베트남의 10년간 면세 조치에 힘입어, 동남아시아는 전구체 및 조립의 거점으로서 역할을 수행하며 양극재 시장의 동쪽으로의 중심 이동을 더욱 공고히 하고 있습니다.
북미에서도 국내 공장의 리스크를 경감시키는 섹션 45X 세액 공제를 배경으로 수요가 확대되고 있습니다. 미국의 생산은 BASF 오하이오 공장과 알베마르 킹스마운틴 공장에 의해 뒷받침되고 있으며, POSCO FUTURE M과 탈론 메탈스가 설비를 가동하면 캐나다의 생산 능력은 3배로 확대될 것입니다. 멕시코에서는 간펑과 티안치(Tianqi)의 20억 달러 투자 유입으로 USMCA 기준을 충족하는 니어쇼어링 회랑이 형성되고 있습니다. 이러한 움직임으로 납기 기간이 단축되고, 양극재 시장공급망이 아시아 이외의 지역으로 다각화되고 있습니다.
유럽 역시 유럽 배터리 얼라이언스(European Battery Alliance)가 현지 생산에 자금을 지원함으로써 두각을 나타내고 있습니다. 2024년 독일의 생산량은 BASF 슈바르츠하이데와 우미코어 니사의 기여로 증가했으며, 한편 영국에서는 JLR을 대상으로 타타 케미칼스가 추진하는 연간 4만 톤 규모의 LFP 프로젝트를 통해 생산이 재개되었습니다. 남미에서는 리튬 자원이 풍부한 칠레와 아르헨티나가 수산화리튬을 수출하며, 2만 2,000톤의 양극 전구체를 공급하고 있습니다. 또한 모로코의 부 아자 광산은 유럽 거점에 황산코발트를 공급하고 있습니다. 중동 및 아프리카의 점유율은 낮지만, 전략적 원자재를 보유하고 있어 전구체 수출국으로서의 지위를 확립할 가능성이 있습니다. 이러한 지리적 다각화가 더해져 지역적 충격으로부터 양극재 시장을 보호하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.11According to Mordor Intelligence, the cathode materials market size was valued at 3.91 Million tons in 2025 and is estimated to grow from 4.85 Million tons in 2026 to reach 14.32 Million tons by 2031, at a CAGR of 24.15% during the forecast period (2026-2031).
This report is Segmented by Material (Lithium Iron Phosphate, Lithium Cobalt Oxide, Lithium Manganese Oxide, and More), Battery Type (Lithium-Ion, Lead-Acid, Sodium-Ion, and Flow Batteries), End-User Industry (Automotive, Consumer Electronics, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Cathode Materials Market Trends and Insights
Surging EV Production Volumes
Global electric-vehicle output climbed to 13.8 million units in 2025 and is predicted to exceed 22 million by 2028, a trajectory that lifts cathode demand because every 60 kWh pack embeds 8-12 kg of active material. BYD plans to double 2024 volumes by manufacturing 4 million plug-ins in 2026, underscoring scale expansion across Asia. The switch to larger-format cells such as CATL's Qilin increases cathode loading per vehicle by thickening electrode coatings. Fleet electrification adds another layer, illustrated by UPS ordering 10,000 LFP-powered delivery vans in 2025. Commercial-vehicle duty cycles favor LFP longevity, providing counter-cyclical stability for the cathode materials market.
Government Incentives and Emissions Regulations
Section 45X of the U.S. Inflation Reduction Act grants USD 10 per kilowatt-hour for domestic cells and USD 45 for modules, triggering 18 U.S. gigafactory announcements totaling 550 GWh of capacity. In Europe, the Battery Regulation mandates carbon-footprint declarations by 2027 and tightens thresholds by 2030, advantaging cathode plants tied to renewable power such as Umicore's Nysa site, which sources 80% wind energy. China extended new-energy vehicle purchase-tax exemptions to 2027, sustaining demand in the world's largest EV arena. India's USD 2.4 billion Production-Linked Incentive for advanced cells lures Reliance Industries and Rajesh Exports, positioning South Asia as a new pole of cathode consumption.
Supply-Chain Concentration in China
China refined 78% of global lithium hydroxide and 93% of manganese sulfate in 2024, exposing Western automakers to delivery risk when domestic suppliers reprioritize local needs. Ford postponed its F-150 Lightning extended-range launch by four months in 2024 after a Chinese precursor partner diverted shipments during a lithium shortage. U.S. defense assessments warn that a Taiwan Strait conflict could choke cathode flows, while European players like Volkswagen's PowerCo rely on China for 82% of NMC precursor. Building a 20 kt/yr precursor plant costs USD 150 million and 30 months, which slows diversification. Compliance with the Uyghur Forced Labor Prevention Act obliges automakers to trace multi-tier suppliers, adding administrative overhead.
Other drivers and restraints analyzed in the detailed report include:
- Battery-Pack Cost Decline from Scale Learning
- Localization of Cathode Supply Chains in US and EU
- Solid-State Batteries Lower Cathode Mass/kWh
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Lithium iron phosphate accounted for 41.10% of 2025 volume and is anticipated to expand at 24.97% through 2031, reflecting Tesla and BYD adoptions that eliminated cobalt and nickel from mass-market models. BYD's Blade pack narrowed the energy-density gap with NMC 622 to 15%, supporting broader acceptance. Premium brands still specify high-nickel NMC: BMW's Neue Klasse uses NMC 811 at 285 Wh/kg, positioning the chemistry where 500-km range is non-negotiable. Lithium-nickel-cobalt-aluminum holds niche but profitable ground in long-range packs, although sliding cobalt prices erode its margin advantage. Lead dioxide continues in starter batteries yet will cede share as 12-V lithium replacements scale. Sodium iron phosphate's slice will rise as sodium-ion cars launch in price-sensitive Asian markets, broadening the cathode materials market canvas.
Complete Report Scope:
- By Material
- Lithium Iron Phosphate
- Lithium Cobalt Oxide
- Lithium-Nickel Manganese Cobalt
- Lithium Manganese Oxide
- Lithium Nickel Cobalt Aluminium Oxide
- Lead Dioxide
- Other Materials (Sodium Iron Phosphate, Oxyhydroxide, and Graphite)
- By Battery Type
- Lithium-Ion
- Lead-Acid
- Sodium-ion
- Flow batteries
- By End-user Industry
- Automotive
- Consumer Electronics
- Power Tools
- Energy Storage
- Other End-user Industries (Medical Devices, Aerospace, etc)
- By Geography
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Indonesia
- Vietnam
- Thailand
- Malaysia
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- NORDIC Countries
- Turkey
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific commanded 79.10% of the market share in 2025 and is on a 26.34% CAGR trajectory to 2031, reflecting deep integration across mining, processing, and cell manufacturing. China anchors this ecosystem through cost advantages and proprietary process expertise, enabling sustained innovation velocity. South Korea and Japan provide complementary high-precision manufacturing and advanced material formulations, reinforcing regional dominance. Indonesia's USD 15 billion in smelting investment and Vietnam's decade-long tax holidays ensure Southeast Asia doubles as both precursor and assembly hub, reinforcing the cathode materials market's eastward gravity.
North America demand is also growing on the back of Section 45X credits that de-risk domestic plants. The United States production is supported by BASF Ohio and Albemarle Kings Mountain, with Canadian capacity tripling once POSCO FUTURE M and Talon Metals commission assets. Mexico's USD 2 billion influx from Ganfeng and Tianqi creates a near-shoring corridor that meets USMCA thresholds. These moves shrink delivery times and diversify the cathode materials market supply chain beyond Asia.
Europe is also rising as the European Battery Alliance bankrolls local output. Germany's production in 2024 climbed with BASF Schwarzheide and Umicore Nysa, while the U.K. rebooted via Tata Chemicals' 40,000 t/yr LFP project to serve JLR. South America's lithium-rich Chile and Argentina export hydroxide feeding 22,000 tons of cathode precursor, and Morocco's Bou-Azzer mine supplies cobalt sulfate to European sites. Middle-East and Africa hold lower share but own strategic raw materials that could reposition them as precursor exporters. Collectively, geographic diversification sustains the cathode materials market against regional shocks.
- BASF
- Contemporary Amperex Technology Co., Limited
- Ecopro BM
- Eramet (Sandouville)
- Guangxi CNGR Advanced Material
- Himadri Speciality Chemical Ltd
- Huayou Cobalt Co., Ltd.
- IBU-tec
- LANDF CORP
- LG Chem
- MITSUI MINING & SMELTING CO.,LTD.
- NICHIA CORPORATION
- Nippon Chemical Industrial Co., Ltd.
- POSCO FUTURE M
- Shenzhen Dynanonic Co., Ltd.
- Showa Denko Materials
- Sumitomo Metal Mining Co., Ltd.
- Targray
- Umicore
- XTC New Energy Materials
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging EV Production Volumes
- 4.2.2 Government Incentives and Emissions Regulations
- 4.2.3 Battery-Pack Cost Decline from Scale Learning
- 4.2.4 Localization of Cathode Supply Chains in US and EU
- 4.2.5 Sodium-Ion and LMFP Commercialization Expanding Demand
- 4.3 Market Restraints
- 4.3.1 Supply-Chain Concentration in China
- 4.3.2 Solid-State Batteries Lower Cathode Mass/kWh
- 4.3.3 Processing Hurdles for High-Mn Chemistries
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Material
- 5.1.1 Lithium Iron Phosphate
- 5.1.2 Lithium Cobalt Oxide
- 5.1.3 Lithium-Nickel Manganese Cobalt
- 5.1.4 Lithium Manganese Oxide
- 5.1.5 Lithium Nickel Cobalt Aluminium Oxide
- 5.1.6 Lead Dioxide
- 5.1.7 Other Materials (Sodium Iron Phosphate, Oxyhydroxide, and Graphite)
- 5.2 By Battery Type
- 5.2.1 Lithium-Ion
- 5.2.2 Lead-Acid
- 5.2.3 Sodium-ion
- 5.2.4 Flow batteries
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Consumer Electronics
- 5.3.3 Power Tools
- 5.3.4 Energy Storage
- 5.3.5 Other End-user Industries (Medical Devices, Aerospace, etc)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 South Korea
- 5.4.1.4 India
- 5.4.1.5 Indonesia
- 5.4.1.6 Vietnam
- 5.4.1.7 Thailand
- 5.4.1.8 Malaysia
- 5.4.1.9 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 NORDIC Countries
- 5.4.3.7 Turkey
- 5.4.3.8 Russia
- 5.4.3.9 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 BASF
- 6.4.2 Contemporary Amperex Technology Co., Limited
- 6.4.3 Ecopro BM
- 6.4.4 Eramet (Sandouville)
- 6.4.5 Guangxi CNGR Advanced Material
- 6.4.6 Himadri Speciality Chemical Ltd
- 6.4.7 Huayou Cobalt Co., Ltd.
- 6.4.8 IBU-tec
- 6.4.9 LANDF CORP
- 6.4.10 LG Chem
- 6.4.11 MITSUI MINING & SMELTING CO.,LTD.
- 6.4.12 NICHIA CORPORATION
- 6.4.13 Nippon Chemical Industrial Co., Ltd.
- 6.4.14 POSCO FUTURE M
- 6.4.15 Shenzhen Dynanonic Co., Ltd.
- 6.4.16 Showa Denko Materials
- 6.4.17 Sumitomo Metal Mining Co., Ltd.
- 6.4.18 Targray
- 6.4.19 Umicore
- 6.4.20 XTC New Energy Materials
7 Market Opportunities and Future Outlook
- 7.1 White-space and unmet-need assessment


