

|
시장보고서
상품코드
2124152
전자기기 제조 서비스 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Electronics Manufacturing Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
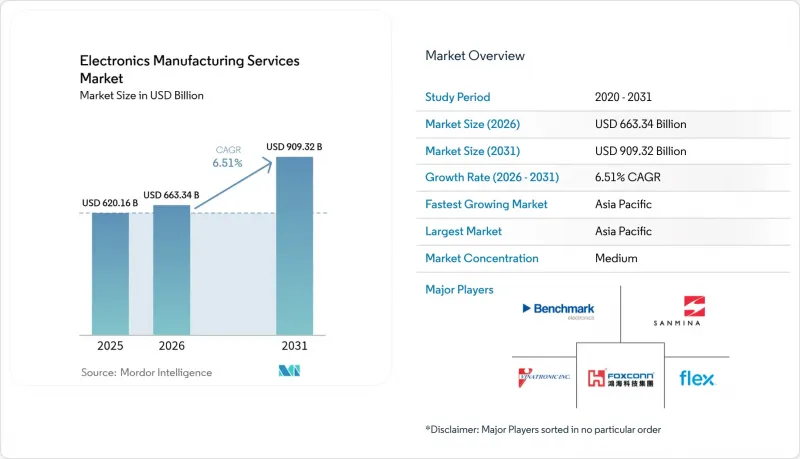
에 의하면, 전자기기 제조 서비스 시장 규모는 2025년에 6,201억 6,000만 달러, 2026년에 6,633억 4,000만 달러가 되어, 2031년까지 9,093억 2,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년까지 CAGR 6.51%로 성장할 전망입니다.
본 보고서는 서비스 유형(전자기기 제조 서비스(PCB 조립, 시제품 제작 등), 테스트 및 개발 구현 서비스 등), 비즈니스 모델(CM, ODM 등), 제조 공정(SMT, THT 등), 최종 사용자(모바일 기기, 가정용 전자기기, 조명 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 전자기기 제조 서비스 시장 동향 및 인사이트
핵심 경쟁력에 집중하기 위해 OEM 기업들이 아웃소싱을 추진하고 있음
각 전자 기업들은 반도체 로드맵 및 AI 모델 훈련에 주력하는 한편, 기계 가공 및 기판 수준 작업의 확대되는 부분을 외부 업체에 이관하고 있습니다. 애플이 최첨단 패키지 조립을 외부에 위탁한 것은 고정비가 높은 공장이 자본 집약적이라는 점을 여실히 보여주며, 수직 통합형 거대 기업조차도 전자기기 제조 서비스 시장에서 가치를 발견하고 있는 이유를 보여줍니다. 스마트폰이나 웨어러블 기기의 제품 수명 주기가 18개월 미만이라는 점은 이러한 전환을 가속화하고 있습니다. 사내 제조 시설로는 급속한 모델 변경에 유연하게 대응하기 어렵기 때문입니다. 중소규모의 산업용·의료용 브랜드들은 납땜에 그치지 않고 펌웨어 기록 및 규제 관련 서류 작성까지 아웃소싱을 확대하고 있으며, 이로 인해 엔지니어링 역량을 중시하는 공급업체가 범용적인 업무를 처리하는 업체보다 8-12포인트 높은 이익률을 확보하는 양극화된 시장이 형성되고 있습니다.
공급망의 니어쇼어링 및 리쇼어링 가속화
관세 불확실성과 수출 규제를 배경으로, 2025년에는 멕시코, 폴란드, 베트남에서의 공장 건설 발표 건수가 23% 급증했습니다. 멕시코는 중국 연안 지역과 비교해 16%의 인건비 우위뿐만 아니라, USMCA(미국·멕시코·캐나다 협정)에 따른 무관세 지위를 바탕으로 파워 일렉트로닉스 및 산업용 제어 기기의 주요 거점으로 선정되고 있습니다. 동유럽은 EU의 관세 조화로 인해 문에서 문까지 운송 시간이 4일 미만으로 단축됨에 따라, 의료기기의 하위 조립 생산 거점으로 자리 잡고 있습니다. 베트남은 10년에 걸친 법인세 면제 조치를 제공함으로써 스마트폰 및 음향 모듈의 생산 라인을 확보하고 있습니다. 한편, 태국과 말레이시아는 반도체 백엔드 분야의 강점을 활용하여 칩렛 인 패키지(Chiplet-in-Package) 프로그램 유치에 주력하고 있습니다.
반도체 및 수동 부품의 비용 변동성 증가
자동차용 다층 세라믹 커패시터의 현물 가격은 2025년 1분기부터 4분기에 걸쳐 35-50% 변동하여, 장기 공급 계약을 체결하지 않은 전자기기 제조 서비스(EMS) 시장 진출기업들의 경우, 매출 총이익률을 최대 120베이시스포인트까지 끌어내리는 결과를 초래했습니다. 마이크로컨트롤러의 리드타임은 12주에서 26주로 대폭 늘어났으며, 수탁 제조업체는 2개월 분의 추가 재고를 충당할 자금을 마련해야 했고, 생산 능력 확충에 사용되어야 할 운전 자금을 동결할 수밖에 없게 되었습니다. 연간 매출액이 50억 달러 이상인 Tier 1 공급업체는 우선적인 할당량을 확보할 수 있는 협상력을 보유하고 있는 반면, 지역 기업들은 20-40%의 현물 프리미엄을 지불해야 하여 가전제품 프로그램에 대한 입찰 경쟁력이 약화되고 있습니다. 엔지니어들이 품귀 현상이 발생한 수동 부품을 피하기 위해 부품표(BOM) 재설계에 분주했던 결과, 제품 출시 시기가 4-8주 지연되면서 전자 제조 서비스 시장의 수익 인식에 차질이 생겼습니다.
부문 분석
전기 기계 조립 및 박스 빌드는 연평균 성장률(CAGR) 6.83%로 확대될 것으로 예측되며, 이는 전자기기 제조 서비스 시장 전체의 성장률 6.51%를 상회할 전망입니다. 자동차 및 산업 분야의 구매자들은 케이블,케이스, 최종 테스트를 하나의 발주서로 처리할 것을 요구하고 있으며, 이를 통해 프로젝트 리드타임을 2-3주 단축하고 있습니다. 2025년에도 PCB 조립은 전자기기 제조 서비스 시장에서 43.32%의 점유율을 유지했으나, 소비자용 제품 수주에서는 매출총이익률이 6% 미만으로 떨어졌습니다. 엔지니어링 서비스는 각 프로그램당 30-50% 더 높은 수익을 창출하고 있습니다. 이는 각 브랜드가 제조 적합성 설계(DFM) 검증 및 FDA와 IEC 감사를 위한 규제 관련 서류를 필요로 하기 때문입니다.
의료 및 자동차 분야의 리콜 비용이 1억 달러를 초과할 가능성이 있어, 테스트 및 개발에 대한 예산 배분은 현재 증가 추세에 있습니다. 주문 생산(CTO)에 따른 주문 처리나 공급업체 관리 재고(VMI)와 같은 물류 관련 부가 서비스는 공급이 부족한 부품 상황을 가시화하여 고객의 전환 비용을 높입니다. 48시간 내 납기를 실현하는 프로토타이핑을 통해 계약업체는 부품 명세서(BOM)가 확정되기 전에 설계 채택을 확정할 수 있습니다. 이러한 부가가치 요소들이 결합됨에 따라, 1차 공급업체는 그렇지 않으면 일반 상품화될 가능성이 있는 핵심 서비스에서 이익률을 유지할 수 있게 됩니다. 따라서 전자기기 제조 서비스 시장은 케이스 조립에 대한 고도의 노하우와 엔지니어링 및 공급망 조정 능력을 융합할 수 있는 공급업체로 기울고 있습니다.
2025년 매출액 중 수탁 제조가 62.46%를 차지했으나, 하이브리드형 및 턴키형 모델은 2031년까지 매년 7.02%씩 증가할 것으로 예측됩니다. 조달 역량을 갖추지 못한 스타트업 기업들은 부품 조달 위험을 회피할 수 있기 때문에 8-12%의 가격 프리미엄이 붙는 경우에도 턴키 계약을 채택하고 있습니다. 대부분의 자동차 및 산업용 브랜드는 하이브리드 구조를 선택하고 있으며, 자사 고유의 펌웨어를 제공하는 한편, 위탁 업체가 전원 스테이지나 통신 보드의 설계를 담당합니다. 이러한 협력을 통해 지적 재산을 보호하면서도 외부의 규모의 경제 효과를 활용할 수 있게 됩니다.
공동 개발 계약에서는 수년에 걸친 생산량 확약을 대가로 금형 비용을 분담함으로써 이러한 협력을 더욱 심화하고 있습니다. 이 구조를 통해 고객은 18-24개월 후까지의 로드맵을 공개할 수밖에 없게 되어, 벤더 락인이 강화되는 동시에 공장의 가동률이 안정화됩니다. ODM(Original Design Manufacturer)은 커넥터, 배터리, 음향 부품을 묶음 판매함으로써 이 모델을 가전 분야로도 확대하고 있으며, 이로 인해 순수한 수탁 조립 업체가 이용할 수 있는 전자기기 제조 서비스(EMS) 시장 규모가 축소되고 있습니다. 그 결과, 현재는 시간당 단가보다 엔지니어링의 깊이와 자본 접근성이 더 중요시되고 있습니다. 이러한 상황에서는 수익을 훼손하지 않으면서 수탁 생산, 하이브리드, 설계 중심 프로그램 사이를 유연하게 전환할 수 있는 공급업체가 유리해집니다.
지역별 분석
아시아태평양은 2025년에 전 세계 전자기기 제조 서비스 시장 점유율의 56.48%를 차지하며, 2031년까지 연평균 성장률(CAGR) 6.63%로 성장할 것으로 전망됩니다. 중국이 가장 큰 수익 기반을 제공하며, 일본은 정밀한 자동차 및 산업용 모듈을 전문으로 하고, 한국은 디스플레이 및 메모리 관련 제품 제조 분야에서 계속해서 지배적인 위치를 유지했습니다. 인도의 ‘생산 연계 인센티브(PLI)’ 프로그램은 증분 매출의 4-6%를 환급해 주어 새로운 스마트폰 및 가전제품 생산 라인을 유치했습니다. 한편, 베트남의 10년간 법인세 면제 조치는 오디오 모듈 및 프리미엄 스마트폰용 최종 조립 시설을 유치했습니다. 동남아시아 국가들 또한 반도체의 백엔드 공정과 기판 조립을 연결하는 ‘칩렛(chiplet)’ 통합 프로젝트에 입찰할 수 있도록 패키징 설비를 업그레이드했습니다.
니어쇼어링으로 인해 북미의 활동 양상은 일변했으며, 멕시코는 USMCA에 따른 관세 인하, 중국 연안 지역에 비해 16% 낮은 인건비, 그리고 텍사스의 설계 센터까지 트럭으로 2일이면 도착하는 운송 경로 덕분에 신규 생산 능력의 대부분을 확보했습니다. 미국은 지적 재산의 안전성이 40-60%의 비용 프리미엄을 상쇄하는 항공우주, 방위, 의료기기용 다품종 소량 생산 라인을 유지했습니다. 캐나다 온타리오주·퀘벡주 회랑 지역에서는 자동차용 텔레매틱스와 견고한 산업용 게이트웨이에 주력하고 있으며, 이중언어 구사 엔지니어 인력과 디트로이트 및 중서부 지역으로의 납기 요건을 충족하는 적시(JIT) 물류를 활용하고 있습니다. 유럽에서는 폴란드, 체코, 루마니아가 의료기기 및 자동차용 하위 어셈블리 생산 거점을 확보했습니다. 이는 EU 관세 제도의 일관성 덕분에 같은 주 내 재고 보충이 가능하기 때문입니다. 한편, 독일, 프랑스, 영국은 항공기 안전에 필수적인 전자기기 및 방위용 전자기기의 생산을 국내 공장에서 유지하고 있습니다.
남미, 중동 및 아프리카는 전자기기 제조 서비스 시장 규모에서 차지하는 비중은 작지만, 특정 분야에서 성장세를 보이고 있습니다. 브라질의 통신 분야 현지 조달 규제와 재생에너지용 인버터 프로그램이 지역 수요를 뒷받침하고 있으며, 계약업체들은 국내 유통업체와의 합작 투자를 통해 현지화를 추진하도록 장려받고 있습니다. 남아프리카공화국에서 계통 연계형 태양광 인버터 및 스마트 계량기 도입이 추진됨에 따라, 가혹한 환경 하에서 콘포멀 코팅에 숙련된 공급업체에게 유리한 틈새 시장인 박스 빌드 수주가 증가하고 있습니다. 절대적인 규모는 여전히 작지만, 이러한 시장은 수익원을 다각화하고 지정학적 위험을 분산하고자 하는 공급업체에게 미래의 진출 기회를 제공합니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the electronics manufacturing services market size is projected to be USD 620.16 billion in 2025, USD 663.34 billion in 2026, and reach USD 909.32 billion by 2031, growing at a CAGR of 6.51% from 2026 to 2031.
This report is Segmented by Service Type (Electronic Manufacturing Services [PCB Assembly, Prototyping, and More], Test and Development Implementation Services, and More), Business Model (CM, ODM, and More), Manufacturing Process (SMT, THT, and More), End-User (Mobile Devices, Consumer Electronics, Lighting, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Electronics Manufacturing Services Market Trends and Insights
OEMs Outsourcing to Focus on Core Competencies
Electronics brands are doubling down on silicon roadmaps and AI model training, shifting an expanding slice of mechanical and board-level work to external contractors. Apple's choice to farm out state-of-the-art package assembly underscores the capital-intensive nature of high-fixed-cost factories and illustrates why even vertically integrated giants see value in the Electronics manufacturing services market. Product lifecycles below 18 months in smartphones and wearables heighten this migration, because internal fabs struggle to flex to rapid model changes. Smaller industrial and medical brands extend outsourcing beyond soldering into firmware flashing and regulatory dossiers, creating a two-tier field where engineering-rich providers capture margins 8-12 points higher than commodity handlers.
Accelerated Near- and Re-Shoring of Supply Chains
Tariff uncertainty and export controls sparked a 23% jump in 2025 plant announcements across Mexico, Poland, and Vietnam. Mexico's 16% labor-cost edge versus coastal China plus USMCA duty-free status make it the preferred hub for power electronics and industrial controls. Eastern Europe secures medical-device subassemblies because EU customs harmonization trims door-to-door transit to under four days. Vietnam locks smartphone and acoustic module lines by offering decade-long corporate-tax holidays, while Thailand and Malaysia co-opt semiconductor back-end prowess to court chiplet in-package programs.
Rising Semiconductor and Passive Component Cost Volatility
Spot prices for automotive-grade multilayer ceramic capacitors swung 35-50% between Q1 2025 and Q4 2025, crushing gross margins by up to 120 basis points for Electronics manufacturing services market participants that lacked long-term allocation deals. Microcontroller lead times ballooned from 12 to 26 weeks, compelling contractors to fund two additional months of inventory and freeze working capital that could have financed capacity upgrades. Tier-1 vendors with USD 5 billion or more in annual revenue wield leverage to secure priority allocation, whereas regional firms pay 20-40% spot premiums, weakening bids on consumer electronics programs. Launch windows slipped four-to-eight weeks as engineers scrambled to redesign bills of material around scarce passives, derailing revenue recognition in the Electronics manufacturing services market.
Other drivers and restraints analyzed in the detailed report include:
- Surge in EV Power-Electronics Requiring Advanced PCB Assembly
- Proliferation of IIoT Edge Devices Driving HDI and Advanced Packaging
- Competition from ODMs and OEM In-House Lines in Smartphones
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Electromechanical assembly and box build are forecast to expand at a 6.83% CAGR, outpacing the 6.51% headline growth of the Electronics manufacturing services market. Automotive and industrial buyers want one purchase order that covers cables, enclosures, and final test, trimming project lead time by two to three weeks. PCB assembly still held a 43.32% Electronics manufacturing services market share in 2025, but gross margins slipped below 6% on consumer-grade orders. Engineering services generate 30-50% higher revenue per program because brands need design-for-manufacturability checks and regulatory files for FDA and IEC audits.
Testing and development now command a growing budget slice as recalls in medical and automotive segments can climb past USD 100 million. Logistics add-ons such as configure-to-order fulfillment and vendor-managed inventory grant line-of-sight into constrained components, raising switching costs for customers. Prototyping with 48-hour turnarounds helps contractors lock in design wins before BOMs are frozen. Together, these value-added layers let tier-1 vendors defend margins in a core service that might otherwise commoditize. The Electronics manufacturing services market therefore tilts toward suppliers able to blend box build depth with engineering and supply-chain orchestration.
Contract manufacturing captured 62.46% of 2025 revenue, yet hybrid and turnkey models are projected to climb 7.02% each year through 2031. Start-ups without procurement muscle embrace turnkey deals even at 8-12% price premiums because they sidestep component sourcing risk. Automotive and industrial brands choose hybrid structures, supplying proprietary firmware while contractors design power stages and communication boards. This collaboration protects intellectual property and still harnesses external economies of scale.
Joint-development agreements deepen that alignment by sharing tooling costs in return for multi-year volume pledges. The structure forces customers to reveal roadmaps 18-24 months ahead, tightening vendor lock-in and stabilizing factory utilization. Original design manufacturers extend the model in consumer electronics by bundling connectors, batteries, and acoustics, which compresses the Electronics manufacturing services market size available to pure contract assemblers. Consequently, engineering depth and capital access now matter more than hourly labor rates. The landscape favors providers that can pivot among contract, hybrid, and design-rich programs without diluting returns.
Complete Report Scope:
- By Service
- Electronic Manufacturing Services
- PCB Assembly
- Electromechanical Assembly/Box Build
- Prototyping
- Other Electronic Manufacturing Services
- Engineering Services
- Test and Development Implementation
- Logistics Services
- Other Services
- Electronic Manufacturing Services
- By Business Model
- Contract Manufacturing (CM)
- Original Design Manufacturing (ODM)
- Hybrid / Turnkey / Other Business Models
- By Manufacturing Process
- Surface Mount Technology (SMT)
- Through-Hole Technology (THT)
- Advanced Packaging / Hybrid Processes
- By End-user
- Mobile Devices (Smartphones and Tablets)
- Consumer Electronics
- Computer (PCs/Desktop/Laptops)
- Industrial
- Automotive
- Communication
- Lighting
- Medical
- Other End-users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- South-east Asia
- Rest of Asia-Pacific
- South America
- Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 56.48% of global Electronics manufacturing services market share in 2025 and is projected to grow at a 6.63% CAGR through 2031. China provided the largest revenue base, Japan specialized in precision automotive and industrial modules, and South Korea remained dominant in display and memory-adjacent builds. India's Production Linked Incentive program, which reimburses 4-6% of incremental sales, attracted fresh smartphone and appliance lines, while Vietnam's ten-year corporate tax holidays drew acoustic modules and final assembly for premium handsets. Southeast Asian nations also upgraded packaging equipment so they can bid for chiplet integration projects that bridge semiconductor back-end and board assembly.
Near-shoring has reshaped North American activity, with Mexico capturing the bulk of new capacity thanks to USMCA tariff relief, a 16% labor-cost edge over coastal China, and two-day truck routes to Texas design centers. The United States kept high-mix, low-volume lines for aerospace, defense, and medical devices where intellectual-property security offsets a 40-60% cost premium. Canada's Ontario-Quebec corridor concentrated on automotive telematics and rugged industrial gateways, leveraging bilingual engineering talent and just-in-time logistics that meet Detroit and Midwest delivery windows. In Europe, Poland, Czech Republic, and Romania landed medical-device and automotive subassemblies because EU customs alignment allows same-week replenishment, while Germany, France, and the United Kingdom preserved flight-critical and defense electronics in domestic plants.
South America and the Middle East and Africa contributed smaller slices of Electronics manufacturing services market size but show targeted momentum. Brazil's telecommunications local-content rules and renewable-energy inverter programs anchor regional demand, encouraging contractors to localize through joint ventures with domestic distributors. South Africa's push for grid-tied solar inverters and smart-meter rollouts nurtures niche box-build orders that reward suppliers skilled in harsh-environment conformal coating. Although absolute numbers remain modest, these pockets diversify revenue streams and provide future landing zones for providers eager to spread geopolitical risk.
- Hon Hai Precision Industry Co., Ltd. (Foxconn)
- Pegatron Corp.
- Flex Ltd.
- Jabil Inc.
- Luxshare Precision Industry Co., Ltd.
- Wistron Corp.
- Sanmina Corp.
- Celestica Inc.
- Benchmark Electronics Inc.
- Plexus Corp.
- Compal Electronics Inc.
- Inventec Corp.
- Universal Scientific Industrial Co., Ltd. (USI)
- BYD Electronics (International) Co., Ltd.
- Shenzhen Kaifa Technology Co., Ltd.
- Asteelflash Group
- Kimball Electronics Inc.
- Sumitronics Corp.
- Nortech Systems Inc.
- Creation Technologies Ltd.
- Integrated Micro-Electronics Inc.
- Zollner Elektronik AG
- New Kinpo Group (Cal-Comp)
- SIIX Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 OEMs Outsourcing to Focus on Core Competencies
- 4.2.2 Accelerated Near-/Re-shoring of Supply Chains to Mexico, Eastern Europe and ASEAN
- 4.2.3 Surge in EV Power-Electronics Requiring Advanced PCB Assembly Capabilities
- 4.2.4 Proliferation of IIoT Edge Devices Driving HDI and Advanced Packaging EMS Demand
- 4.2.5 Government Tax Incentives for Domestic EMS Facilities in India and Vietnam
- 4.2.6 AI-Driven Digital MES Improving First-Pass Yield and Reducing Rework Costs
- 4.3 Market Restraints
- 4.3.1 Rising Semiconductor and Passive Component Cost Volatility
- 4.3.2 IP Protection Concerns Limiting Outsourcing in EU Aerospace and Defense
- 4.3.3 Competition from ODMs and OEM In-house Lines in Smartphones
- 4.3.4 Environmental Compliance (RoHS III, REACH) Raising Capex for Legacy Facilities
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.6.1 Surface-Mount Technology Roadmap
- 4.6.2 High-Density Interconnect and Embedded Component PCB
- 4.6.3 Advanced Packaging and System-in-Package
- 4.6.4 Digital MES, AI Quality Inspection and Cobotics
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service
- 5.1.1 Electronic Manufacturing Services
- 5.1.1.1 PCB Assembly
- 5.1.1.2 Electromechanical Assembly/Box Build
- 5.1.1.3 Prototyping
- 5.1.1.4 Other Electronic Manufacturing Services
- 5.1.2 Engineering Services
- 5.1.3 Test and Development Implementation
- 5.1.4 Logistics Services
- 5.1.5 Other Services
- 5.1.1 Electronic Manufacturing Services
- 5.2 By Business Model
- 5.2.1 Contract Manufacturing (CM)
- 5.2.2 Original Design Manufacturing (ODM)
- 5.2.3 Hybrid / Turnkey / Other Business Models
- 5.3 By Manufacturing Process
- 5.3.1 Surface Mount Technology (SMT)
- 5.3.2 Through-Hole Technology (THT)
- 5.3.3 Advanced Packaging / Hybrid Processes
- 5.4 By End-user
- 5.4.1 Mobile Devices (Smartphones and Tablets)
- 5.4.2 Consumer Electronics
- 5.4.3 Computer (PCs/Desktop/Laptops)
- 5.4.4 Industrial
- 5.4.5 Automotive
- 5.4.6 Communication
- 5.4.7 Lighting
- 5.4.8 Medical
- 5.4.9 Other End-users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 South Korea
- 5.5.3.4 India
- 5.5.3.5 South-east Asia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.5 Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Hon Hai Precision Industry Co., Ltd. (Foxconn)
- 6.4.2 Pegatron Corp.
- 6.4.3 Flex Ltd.
- 6.4.4 Jabil Inc.
- 6.4.5 Luxshare Precision Industry Co., Ltd.
- 6.4.6 Wistron Corp.
- 6.4.7 Sanmina Corp.
- 6.4.8 Celestica Inc.
- 6.4.9 Benchmark Electronics Inc.
- 6.4.10 Plexus Corp.
- 6.4.11 Compal Electronics Inc.
- 6.4.12 Inventec Corp.
- 6.4.13 Universal Scientific Industrial Co., Ltd. (USI)
- 6.4.14 BYD Electronics (International) Co., Ltd.
- 6.4.15 Shenzhen Kaifa Technology Co., Ltd.
- 6.4.16 Asteelflash Group
- 6.4.17 Kimball Electronics Inc.
- 6.4.18 Sumitronics Corp.
- 6.4.19 Nortech Systems Inc.
- 6.4.20 Creation Technologies Ltd.
- 6.4.21 Integrated Micro-Electronics Inc.
- 6.4.22 Zollner Elektronik AG
- 6.4.23 New Kinpo Group (Cal-Comp)
- 6.4.24 SIIX Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


