

|
시장보고서
상품코드
2125747
북미의 전자기기 제조 서비스 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America Electronics Manufacturing Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
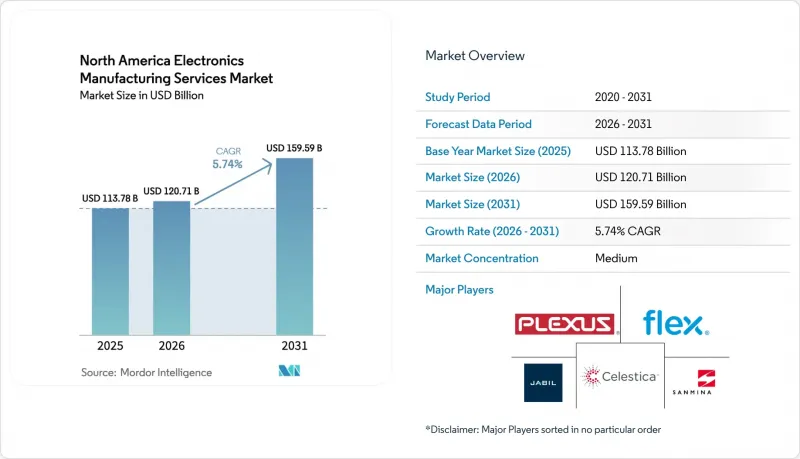
에 의하면, 북미 전자기기 제조 서비스 시장 규모는 2025년에 1,972억 2,000만 달러로 평가되었고 2026년 2,079억 8,000만 달러에서 2031년까지 2,839억 1,000만 달러에 이를 것으로 추정되고 있어 예측 기간(2026-2031년) CAGR은 6.42%를 나타낼 전망입니다.
본 보고서는 서비스 유형(엔지니어링 서비스, 물류 서비스 등), 비즈니스 모델(수탁 제조(CM), 오리지널 디자인 제조(ODM) 등), 제조 공정(표면실장기술(SMT) 등), 최종 사용자(산업용, 자동차용 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
북미 전자기기 제조 서비스 시장 동향 및 인사이트
‘CHIPS and Science Act’에 따른 강력한 리쇼어링 장려책
2025년 말까지 40건의 제조 및 패키징 프로젝트에 총 364억 달러의 보조금이 지급됨에 따라, 하류 전자기기 조립 투자 열풍이 일어났습니다. 수탁 제조업체들은 OEM 제조업체에 리드 타임을 단축하고 물류 위험을 경감하는 ‘웨이퍼에서 기판까지’의 통합 공급망을 제공하기 위해 팹 근처에 새로운 표면 실장 라인을 병설하고 있습니다. 2025년 중반에 발표된 자빌(Jabil)사의 5억 달러 규모 노스캐롤라이나주 프로젝트는 AI 및 고성능 컴퓨팅 수요를 흡수하기 위해 박스 빌드 역량과 첨단 패키징 노드를 연계하는 전략의 전형적인 사례입니다. ‘리쇼어링 이니셔티브’ 데이터에 따르면, 2023년에 발표된 미국의 제조업 고용은 28만 7,299건에 달했으며, 전기 및 전자 기기가 리팩토링 목록의 최상위를 차지하고 있습니다. 섹션 48D에 따른 세액 공제는 프로젝트의 경제성을 더욱 향상시켜, 설령 최종 시장 수요가 일시적으로 둔화되더라도 2028년까지 지속적인 설비 투자 주기를 이끌어낼 것입니다. 따라서 정책 주도형 생산 능력 확충에 힘입어 북미 전자기기 제조 서비스 시장은 시장 동향을 상회하는 성장 궤도를 유지할 것으로 예측됩니다.
EV 및 ADAS 플랫폼에서의 자동차용 전자기기 수요 가속화
전기차(EV)의 파워트레인은 내연기관 차량에 비해 3-5배의 인쇄회로기판 면적이 필요합니다. 한편, ADAS의 센서 퓨전 모듈은 중소규모의 생산량으로 신속한 반복 개발이 요구되지만, 아시아 거점에서는 이를 비용 효율적으로 지원하기 어렵습니다. 폭스콘이 2025년 6월에 발표한 ‘EV.OS’ 플랫폼은 아시아의 최상위 전자기기 제조 서비스(EMS) 제공업체조차 현지 OEM 제조업체와의 공동 개발을 위해 북미 거점이 필요함을 보여줍니다. 미국 국가도로교통안전국(NHTSA)이 2029년형 모델까지 모든 신형 경차에 자동 긴급 제동(AEB) 장치의 탑재를 의무화하는 제안을 내놓음에 따라, 레이더 및 비전 하드웨어가 양산 차량에 탑재될 예정이며,멕시코 및 미국의 자동차 산업 벨트 전역에서 인쇄회로기판(PCB) 수요가 증가할 것으로 전망됩니다. 덴소와 로옴의 실리콘 카바이드 인버터 프로그램과 같은 전략적 제휴는 설계의 복잡성을 높이며, 칩 공급업체 및 시제품 개발 연구소와의 근접성이 경쟁상 필수 조건이 되고 있습니다. 이러한 요인들은 2031년까지 자동차용 전자기기 매출이 연평균 성장률(CAGR) 7.54%를 나타낼 것이라는 전망을 뒷받침하고 있습니다.
Tier 2/3 EMS 공급업체의 숙련된 인력 부족
2025년 현재, 미국 제조업 근로자의 평균 연령은 56.5세에 달하며, 은퇴자 수가 신규 인력 공급을 초과하고 있어 납땜, 검사, 공정 엔지니어링 분야의 인력 부족 현상이 나타나고 있습니다. 1차 기업들은 자체 IPC 인증 아카데미를 운영하고 있지만, 지방 클러스터에 위치한 소규모 공장들은 자동차 조립 공장이 제시하는 임금 수준에 맞설 수 없습니다. 노스캐롤라이나주, 텍사스주, 애리조나주에서 시작된 커뮤니티 칼리지의 견습 프로그램은 각 주에서 연간 500명 미만의 졸업생만을 배출하고 있어, 2028년까지 예정된 40건의 CHIPS법 프로젝트를 감당하기에는 불충분합니다. 그 결과, 신규 생산 능력 확장이 자본 예산 예상보다 지연되고 있으며, 이는 북미 EMS 시장의 실질 공급량을 감소시켜 견조한 수요에도 불구하고 성장을 둔화시키고 있습니다.
부문 분석
전기 기계 조립 및 박스 빌드는 방위 분야의 주 계약업체와 의료기기 OEM이 엔지니어링 자원을 절약하기 위해 최종 통합을 외주화하고 있는 것을 배경으로, 연평균 성장률(CAGR) 6.72%로 매출이 가장 빠르게 증가했습니다. OEM 업체들이 시스템 수준의 전체 테스트, 규제 관련 문서 작성 및 열 설계의 공동 설계를 신뢰할 수 있는 파트너에게 위탁함에 따라, 이 부문은 현재 북미 EMS 시장에서 점점 더 큰 점유율을 차지하고 있습니다. 인쇄 회로 기판(PCB) 조립은 2025년 시장 규모의 42.76%를 차지하고 있지만, 시장은 성숙기에 접어들었고 수요는 범용 부품의 실장에서 고신뢰성 클래스 3 제품으로의 전환이 진행되고 있습니다. 제조 적합성 설계(DFM), 고장 모드 영향 분석(FMEA) 및 부품 노후화 모니터링에 중점을 둔 엔지니어링 서비스는 공급업체와의 유대를 강화하고 전환 비용을 높이고 있습니다. 산업용 IoT 및 저궤도(LEO) 위성 하드웨어에서 혼합 신호 요소가 증가함에 따라 자동 테스트 장비(ATU) 프로그래밍 수요가 확대되고, 프로토타이핑 및 테스트 조립 사업이 활기를 띠고 있습니다. Jabil의 Hanley Energy 인수는 물류 및 전력 공급 노하우가 현재 주요 공급업체의 차별화 요소가 되고 있음을 보여줍니다. 표면 실장 라인은 여전히 널리 보급되어 있지만, 컨포멀 코팅, 포팅, 환경 스트레스 스크리닝을 제공하는 시스템 통합 기업들은 항공우주 및 방위 분야에서 높은 가격을 실현하고 있으며, 이로 인해 박스 빌드 전문 업체들의 이익이 더욱 확대되고 있습니다.
AI 서버 수요의 전환점으로 인해 케이스, 콜드 플레이트, 케이블 어셈블리에 대한 전문 지식의 중요성이 높아지면서 박스 빌드의 매출 점유율을 더욱 끌어올리고 있습니다. 2025년 11월 에볼브 테크놀로지(Evolv Technology)와 계약을 체결한 펠릭서스(Plexus)와 같은 Tier 2 업체들은 신속한 시스템 통합이 메가캡 기업 이외의 업체들에게도 비즈니스 기회를 창출할 수 있음을 보여주고 있습니다. 2026년부터 2031년까지 북미 EMS 시장의 박스 빌드 사업 규모는 400억 달러에 육박할 것으로 예상되며, 이는 전체 지역 시장 가치의 약 4분의 1에 해당합니다. 이는 턴키 방식의 수주가 순수한 기판 수준의 수주를 대체하고 있기 때문입니다.
수탁 제조는 2025년에 64.58%의 점유율을 유지하고 있으며, 이는 산업용 자동화, 통신, 자동차 전자기기 분야에서 수년간 이어져 온 계약을 반영한 것입니다. 그러나 각 OEM 업체들이 자재 조달, 설계 검증, 규정 준수 관련 서류에 대해 ‘단일 청구서를 통한 책임 명확화’를 요구하고 있기 때문에 하이브리드 및 턴키 모델은 연평균 성장률(CAGR) 6.81%로 성장을 지속하고, 있습니다. AI 서버 조립 분야에서는 하이퍼스케일러가 성능 요건을 지정하고, 고대역폭 메모리 및 기판 조달 위험을 전자기기 제조 서비스(EMS) 파트너에게 맡기고 있습니다. 또한, 할당량에 대한 예기치 못한 상황을 피하기 위해 5-8%의 프리미엄을 지불하고 있습니다. 하이브리드 계약은 의료기기의 신제품 도입(NPI)에서도 주류를 이루고 있으며, OEM이 금형을 공동 소유하는 한편, 계약업체가 FDA 감사를 관리하고 있습니다. ODM(Original Design Manufacturing)은 북미 전자기기 제조 서비스 업체들에게 여전히 틈새 시장으로 남아 있으며, 소비자용 주변기기나 통신사 브랜드의 IoT 노드에 집중되어 있지만, 클라우드 어플라이언스 벤더들은 사내 하드웨어 팀에 대한 의존도를 최소화하기 위해 설계 지원을 점점 더 많이 도입하고 있습니다.
자빌(Jabil)의 노스캐롤라이나주 AI 캠퍼스는 이러한 하이브리드 모델의 전형적인 사례입니다. 고객은 펌웨어를 보유하며, 자빌은 자동화 설비에 공동 투자하고 테스트 지그를 소유함으로써, 위탁 생산 업체로는 실현할 수 없는 속도 면에서의 우위를 제공합니다. 킴볼 전자기기(Kimball Electronics)는 자동차 업계 상위 3개 고객사에 대한 매출 집중도가 30%를 초과한다고 밝혔으며, 이는 기존의 수탁 제조 방식에는 고객 의존 위험이 수반됨을 시사합니다. 각 OEM 업체들이 한계 비용보다 공급 탄력성을 우선시하는 가운데, 턴키 계약은 자동차 및 방위 분야에 더욱 확산되어 2031년에 이르기까지 수익 구조를 재편해 나갈 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, North America electronics manufacturing services market size was valued at USD 197.22 billion in 2025 and is estimated to grow from USD 207.98 billion in 2026 to reach USD 283.91 billion by 2031, at a CAGR of 6.42% during the forecast period (2026-2031).
This report is Segmented by Service Type (Engineering Services, Logistics Services, and More), Business Model (Contract Manufacturing (CM), Original Design Manufacturing (ODM), and More), Manufacturing Process (Surface Mount Technology (SMT), and More), End-User (Industrial, Automotive, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
North America Electronics Manufacturing Services Market Trends and Insights
Robust Reshoring Incentives from the CHIPS and Science Act
Awards totaling USD 36.4 billion across 40 fabrication and packaging projects by late 2025 ignited a downstream wave of electronics assembly investments. Contract manufacturers colocate new surface-mount lines near fabs to offer OEMs integrated wafer-to-board supply chains that shorten lead times and mitigate logistics risk. Jabil's USD 500 million North Carolina project, announced in mid-2025, typifies the strategy of aligning box-build capacity with advanced packaging nodes to capture AI and high-performance computing demand. Reshoring Initiative data showing 287,299 U.S. manufacturing jobs announced in 2023 place electrical equipment and electronics at the top of the repatriation list. Tax credits under Section 48D further improve project economics, driving a sustained capex cycle through 2028 even if end-market demand temporarily softens. Policy-driven capacity additions are therefore expected to keep the North America electronics manufacturing services market on an above-trend growth trajectory.
Accelerating Demand for Automotive Electronics in EV and ADAS Platforms
Electric-vehicle powertrains use three to five times more circuit-board real estate than internal-combustion equivalents, while ADAS sensor-fusion modules require quick-turn iterations at small and mid volumes that Asian sites struggle to support cost-effectively. Foxconn's June 2025 EV.OS platform illustrates that even top Asian electronics manufacturing service providers now need North American hubs for co-development with local OEMs. U.S. National Highway Traffic Safety Administration proposals mandating automatic emergency braking on all new light vehicles by model year 2029 will embed radar and vision hardware into mass-market cars, boosting demand for printed circuit boards across Mexico and the U.S. automotive belts. Strategic collaborations such as DENSO and ROHM's silicon-carbide inverter program intensify design complexity, making proximity to chip suppliers and prototyping labs a competitive necessity. These factors underpin the 7.54% CAGR outlook for automotive electronics revenue through 2031.
Skilled Labor Shortages Across Tier-2/3 EMS Providers
The average U.S. manufacturing worker's age reached 56.5 years in 2025, and retirements outpace incoming talent, making soldering, inspection, and process-engineering roles scarce. Tier-1 firms run their own IPC certification academies, but smaller shops in rural clusters cannot match wage offers from automotive assembly plants. Community-college apprenticeship programs launched in North Carolina, Texas, and Arizona graduate fewer than 500 students per state each year, which is inadequate for the 40 CHIPS Act projects scheduled through 2028. Consequently, new capacity ramps more slowly than capital budgets anticipate, reducing effective supply in the North America EMS market and tempering growth despite healthy demand.
Other drivers and restraints analyzed in the detailed report include:
- Growing Need for Rapid NPI Turn-Around in Regulated Medical Devices
- Expansion of AI-Server and High-Speed Computing Hardware Production
- Margin Pressure from Asian High-Volume Contract Manufacturers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Electromechanical assembly and box build generated the fastest revenue growth, rising at a 6.72% CAGR, driven by defense primes and medical-device OEMs outsourcing final integration to save engineering bandwidth. The segment now captures growing portions of the North America EMS market as OEMs delegate full system-level testing, regulatory documentation, and thermal-solution co-design to trusted partners. Printed-circuit-board assembly still accounted for 42.76% of the 2025 value but shows maturity, with demand shifting from commodity placement to high-reliability Class 3 builds. Engineering services focused on design-for-manufacturability, failure-mode-and-effects analysis, and obsolescence monitoring deepen supplier embeddedness and raise switching costs. Prototyping and test implementation businesses flourish as mixed-signal content in industrial IoT and low-earth-orbit (LEO) satellite hardware multiplies the need for automated-test-equipment programming. Jabil's Hanley Energy acquisition illustrates how logistics and power-delivery know-how now differentiate leading providers. Surface-mount lines remain ubiquitous; nonetheless, system-integration shops offering conformal coating, potting, and environmental stress screening capture premium pricing in aerospace and defense, pulling further profit toward box-build specialists.
Demand inflection in AI servers heightens the importance of enclosure, cold-plate, and cable-assembly expertise, further lifting box-build wallet share. Tier-2 players such as Plexus, which won the Evolv Technology contract in November 2025, underscore that quick-turn system integration creates opportunity outside megacaps. Over 2026-2031, the North America EMS market size for box-build work is forecast to approach USD 40 billion, roughly one-quarter of the regional value, as turnkey bookings displace purely board-level awards.
Contract manufacturing maintained a 64.58% share in 2025, reflecting deep legacy agreements in industrial automation, telecom, and automotive electronics. Yet hybrid and turnkey models post a 6.81% CAGR because OEMs want single-invoice accountability for materials procurement, design verification, and compliance paperwork. In AI-server assembly, hyperscalers specify performance envelopes and delegate sourcing risk for high-bandwidth memory and substrates to their electronics manufacturing services partner, paying a 5-8% premium to reduce allocation surprises. Hybrid agreements also dominate new medical-device NPIs, where OEMs co-own tooling but the contractor manages FDA audits. Original design manufacturing remains a niche for North America electronics manufacturing services participants, concentrated in consumer peripherals and carrier-branded IoT nodes, yet cloud appliance vendors increasingly adopt design assistance to minimize reliance on in-house hardware teams.
Jabil's North Carolina AI campus typifies the hybrid model: customers retain firmware, while Jabil co-invests in automation and owns test fixtures, delivering speed advantages that consignment shops cannot match. Kimball Electronics discloses over 30% revenue concentration across its top three auto clients, signaling that traditional contract manufacturing carries customer-dependency risk. As OEMs prioritize supply resilience over marginal cost, turnkey agreements penetrate deeper into automotive and defense, reshaping revenue mix through 2031.
Complete Report Scope:
- By Service Type
- Electronics Manufacturing Services
- PCB Assembly
- Electromechanical Assembly/Box Build
- Prototyping
- Other Electronics Manufacturing Services
- Engineering Services
- Test and Development Implementation Services
- Logistics Services
- Other Service Types
- Electronics Manufacturing Services
- By Business Model
- Contract Manufacturing (CM)
- Original Design Manufacturing (ODM)
- Hybrid / Turnkey / Other Business Models
- By Manufacturing Process
- Surface Mount Technology (SMT)
- Through-Hole Technology (THT)
- Advanced Packaging / Hybrid Processes
- By End-user
- Mobile Devices (Smartphones and Tablets)
- Consumer Electronics
- Computer (PCs/Desktop/Laptops)
- Industrial
- Automotive
- Communication
- Lighting
- Medical
- Other End-users
- By Geography
- North America
- United States
- Canada
- Mexico
- North America
List of Companies Covered in this Report:
- Jabil Inc.
- Flex Ltd.
- Celestica Inc.
- Sanmina Corporation
- Plexus Corp.
- Benchmark Electronics, Inc.
- Kimball Electronics, Inc.
- Creation Technologies LP
- SigmaTron International, Inc.
- Nortech Systems Incorporated
- Hon Hai Precision Industry Co., Ltd.
- Pegatron Corporation
- Compal Electronics Inc.
- Quanta Computer Inc.
- Wistron Corporation
- BYD Electronic (International) Company Limited
- Luxshare Precision Industry Co., Ltd.
- Zollner Elektronik AG
- Asteelflash SAS
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Robust Reshoring Incentives from the CHIPS and Science Act
- 4.2.2 Accelerating Demand for Automotive Electronics in EV and ADAS Platforms
- 4.2.3 Growing Need for Rapid NPI Turn-Around in Regulated Medical Devices
- 4.2.4 Expansion of AI-Server and High-Speed Computing Hardware Production
- 4.2.5 Defense Mandatory ITAR Compliance Driving On-Shore Box-Build Contracts
- 4.2.6 Low-Earth-Orbit Satellite Constellation Builds Requiring Quick-Turn PCB Assembly
- 4.3 Market Restraints
- 4.3.1 Skilled Labor Shortages Across Tier-2/3 EMS Providers
- 4.3.2 Margin Pressure from Asian High-Volume Contract Manufacturers
- 4.3.3 Accelerating PFAS and RoHS Regulatory Compliance Costs
- 4.3.4 Wave of Baby-Boomer Engineering Retirements Eroding Institutional Know-How
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intra-Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Electronics Manufacturing Services
- 5.1.1.1 PCB Assembly
- 5.1.1.2 Electromechanical Assembly/Box Build
- 5.1.1.3 Prototyping
- 5.1.1.4 Other Electronics Manufacturing Services
- 5.1.2 Engineering Services
- 5.1.3 Test and Development Implementation Services
- 5.1.4 Logistics Services
- 5.1.5 Other Service Types
- 5.1.1 Electronics Manufacturing Services
- 5.2 By Business Model
- 5.2.1 Contract Manufacturing (CM)
- 5.2.2 Original Design Manufacturing (ODM)
- 5.2.3 Hybrid / Turnkey / Other Business Models
- 5.3 By Manufacturing Process
- 5.3.1 Surface Mount Technology (SMT)
- 5.3.2 Through-Hole Technology (THT)
- 5.3.3 Advanced Packaging / Hybrid Processes
- 5.4 By End-user
- 5.4.1 Mobile Devices (Smartphones and Tablets)
- 5.4.2 Consumer Electronics
- 5.4.3 Computer (PCs/Desktop/Laptops)
- 5.4.4 Industrial
- 5.4.5 Automotive
- 5.4.6 Communication
- 5.4.7 Lighting
- 5.4.8 Medical
- 5.4.9 Other End-users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Jabil Inc.
- 6.4.2 Flex Ltd.
- 6.4.3 Celestica Inc.
- 6.4.4 Sanmina Corporation
- 6.4.5 Plexus Corp.
- 6.4.6 Benchmark Electronics, Inc.
- 6.4.7 Kimball Electronics, Inc.
- 6.4.8 Creation Technologies LP
- 6.4.9 SigmaTron International, Inc.
- 6.4.10 Nortech Systems Incorporated
- 6.4.11 Hon Hai Precision Industry Co., Ltd.
- 6.4.12 Pegatron Corporation
- 6.4.13 Compal Electronics Inc.
- 6.4.14 Quanta Computer Inc.
- 6.4.15 Wistron Corporation
- 6.4.16 BYD Electronic (International) Company Limited
- 6.4.17 Luxshare Precision Industry Co., Ltd.
- 6.4.18 Zollner Elektronik AG
- 6.4.19 Asteelflash SAS
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


