

|
시장보고서
상품코드
2124394
멀티 터치 어트리뷰션 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Multi-Touch Attribution - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
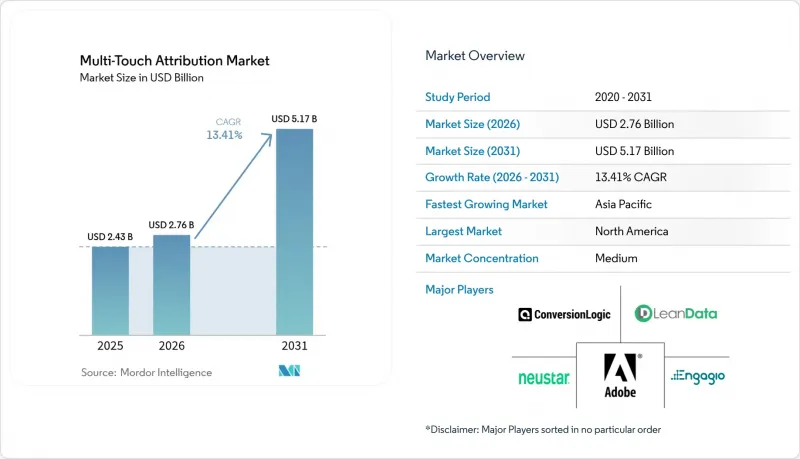
에 의하면, 2026년 멀티 터치 어트리뷰션 시장 규모는 27억 6,000만 달러로 추정되며, 2025년 24억 3,000만 달러에서 성장하여 2031년에는 51억 7,000만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 13.41%를 기록할 전망입니다.
본 보고서는 어트리뷰션 모델별(알고리즘/데이터 기반, 선형, 시간 감쇠형 등), 구성 요소별(솔루션, 서비스), 도입 형태별(클라우드, 온프레미스), 조직 규모별(중소기업, 대기업), 최종 사용자 산업별(소매 및 전자상거래, BFSI, IT 및 통신 등), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 멀티 터치 어트리뷰션 시장 동향 및 인사이트
쿠키 없는 브라우저의 부상으로 퍼스트파티 데이터 전략 가속화
써드파티 쿠키의 폐지에 따라 기업들은 고객 데이터 플랫폼을 기반으로 한, 동의에 기반한 데이터 인프라 구축을 서둘러야 하는 상황에 놓여 있습니다. 신원 확인, 차등 프라이버시, 보안 컴퓨테이션을 통합하는 브랜드들은 고객 생애 가치 향상과 고객 획득 비용 절감을 보고하고 있습니다. 데이터 흐름이 확률론적에서 결정론적으로 전환됨에 따라, 지역 개인정보 보호법을 준수하면서 해시 처리된 이메일 주소, 로열티 ID, 클린룸 출력을 통합할 수 있는 어트리뷰션 엔진에 대한 수요가 증가하고 있습니다. 기본 제공되는 동의 관리 기능과 견고한 거버넌스를 통합한 벤더들은 특히 규제가 엄격한 업계에서 대규모 계약을 수주하고 있습니다.
아시아에서 옴니채널 소매의 확산이 복잡한 고객 여정을 촉진
현재 아시아태평양의 소매업체들은 슈퍼 앱과 통합 지갑 내에서 앱 내, 라이브 스트리밍, 오프라인 매장의 접점을 융합하여 복잡한 전환 경로를 만들어내고 있습니다. Z세대 쇼핑객들은 원활한 경험을 기대하고 있으며, 이로 인해 소매업체들은 소셜 미디어에서의 발견, QR 코드를 통한 활성화, 매장에서의 구매를 단일 그래프로 매핑하는 어트리뷰션 도입을 불가피하게 하고 있습니다. 조기 도입 기업들에 따르면, 라스트 클릭 방식에서 퍼널 업스트림의 참여도에 가중치를 부여할 수 있는 알고리즘 모델로 전환한 결과, 마케팅 효율이 두 자릿수 개선을 보였습니다고 합니다.
개인정보 보호 규제로 인한 신호 손실이 데이터 수집을 저해
GDPR(EU 개인정보보호규정) 및 CPRA와 같은 규제로 인해 쿠키, 크로스사이트 추적, 사용자 프로파일링이 제한되고 있습니다. 마케터들은 데이터 세트의 축소, 모델링된 전환에 대한 의존도 증가, 그리고 더욱 엄격해진 동의 획득 워크플로우에 직면해 있습니다. 많은 기업이 클린룸이나 가산 노이즈 기술에 투자하여 대응하고 있지만, 옵트아웃 비율이 상승하면 어트리뷰션 정확도는 여전히 떨어집니다. 규정 준수에 드는 비용이 혁신 예산을 압박하고 있으며, 끊임없는 정책 변경이 계획 수립에 불확실성을 야기하고 있습니다.
부문 분석
알고리즘 및 데이터 기반 프레임워크는 2025년에 34.25%의 점유율을 차지했으며, 2031년까지 연평균 성장률(CAGR) 14.05%로 확대되어 규칙 기반 접근 방식에서 머신러닝 접근 방식으로의 명확한 전환을 보여줄 것입니다. 이러한 모델은 수십억 개의 접점을 분석하여 전환에 대한 기여도를 동적으로 할당함으로써, 끊임없는 규칙 미세 조정을 불필요하게 하고 예측 정확도를 향상시킵니다. 선형, 시간 감쇠, U자형 접근 방식은 과도기적 요구 사항이나 단일 채널 캠페인에서는 여전히 채택되고 있지만, 확률론적이고 AI를 활용한 계산을 통해 광고 비용 대비 효과(ROAS)가 향상된다는 사실을 마케터들이 실감함에 따라 점차 그 입지를 내주고 있습니다. Meridian, Mix Modeler 및 유사한 솔루션은 진정한 로프트를 벤치마킹하는 인과 추론을 통합하고 있으며, 셀프 서비스형 인터페이스를 통해 기술적 지식이 없는 팀도 코딩 없이 테스트를 시작할 수 있습니다.
브랜드들이 더 신속한 인사이트와 크로스 디바이스 상의 상세한 분석을 요구하는 가운데, 알고리즘 엔진에 대한 지속적인 투자가 멀티 터치 어트리뷰션 시장을 주도할 것입니다. 고급 조사 기법과 개인정보 보호 기술 레이어를 결합함으로써 기업들은 규정 준수(컴플라이언스)와 성과 간의 균형을 맞추며 도입의 모멘텀을 더욱 강화하고 있습니다. 초기 시범 프로젝트에서 라스트 클릭 방식을 알고리즘 모델로 대체한 브랜드들은 불필요한 지출을 두 자릿수 비율로 줄이고, 그동안 과소평가되었던 채널로 예산을 재배분하고 있는 것으로 나타났습니다.
이 솔루션은 멀티 터치 어트리뷰션 시장을 정의하는 핵심적인 데이터 수집, 모델링, 시각화 스택을 제공함으로써 2025년 매출의 69.10%를 계속 차지했습니다. 그러나 기업들이 전략 컨설팅, 데이터 매핑, 모델 거버넌스의 필요성을 인식함에 따라 서비스 부문은 연평균 성장률(CAGR) 15.85%로 급성장하고 있습니다. 주요 브랜드들은 POS 데이터, CRM 이벤트, 스트리밍 로그, 동의 정보를 연계하기 위해 통합 파트너를 활용하고 있으며, 이는 서비스 매출이 라이선스 매출보다 빠르게 성장하고 있는 이유를 뒷받침합니다.
관리형 서비스는 기술 인력 부족에 직면한 조직에게 더욱 매력적인 선택지가 되고 있습니다. 외부 위탁 분석가가 알고리즘의 가중치를 미세 조정하고, 증분 분석을 수행하며, 경영진의 의사 결정을 위해 대시보드를 해석합니다. 이러한 실무적인 지원은 플랫폼 공급업체의 계약 갱신율을 높일 뿐만 아니라, 도입 후 최적화가 수년에 걸친 계약으로 이어짐에 따라 시장의 증분 수익도 견인하고 있습니다.
지역별 분석
2025년, 북미는 전 세계 매출의 39.20%를 차지했습니다. 이는 프로그램 광고에 대한 막대한 투자, 커넥티드 TV의 보급 규모, 그리고 개인정보 보호 강화 기술의 조기 확산에 힘입은 결과입니다. 미국은 마케팅 측정 분야의 AI 실험 중심지이며, 캐나다는 옴니채널 소매 분석을 주도하고, 멕시코는 전자상거래 어트리뷰션 분야에서 고성장 신흥 시장으로 부상하고 있습니다.
유럽은 2위를 차지했으며, 일반 데이터 보호 규정(GDPR(EU 개인정보보호규정))의 영향으로 ‘프라이버시 바이 디자인’이 양보할 수 없는 구매 기준으로 자리 잡고 있습니다. 독일은 제조업 수출 체인에서의 B2B 어트리뷰션을 중시하고, 영국은 금융 및 소매업에 중점을 두고 있으며, 프랑스에서는 슈퍼마켓이 수익원을 다각화하는 가운데 리테일 미디어 측정이 확대되고 있습니다. 북유럽 국가들은 광범위한 5G 보급과 높은 앱 보급률에 힘입어, 모바일 우선 어트리뷰션의 고도화 측면에서 두드러지고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 14.85%로 가장 빠르게 성장하는 지역이며, 이는 모바일 중심의 소비자 행동, 슈퍼앱 생태계, 라이브 스트리밍 커머스를 반영합니다. 중국에서는 라이브 스트리밍에서의 상호작용, 소셜 미디어를 통한 소개, 매장에서의 QR 코드 스캔을 통합하는 어트리뷰션 시범 운영이 진행되고 있으며, 복잡하게 얽힌 터치포인트를 분석하는 모델에 대한 수요가 나타나고 있습니다. 일본은 커넥티드 TV 및 게임 분야에서 크로스 디바이스 어트리뷰션을 추진하고 있는 반면, 인도에서는 디지털 결제 인프라의 확장이 소매 및 핀테크 분야의 어트리뷰션 수요를 뒷받침하고 있습니다. 싱가포르에서 인도네시아에 이르는 동남아시아 시장에서는 오프라인 매장 체인이 디지털 스토어프론트를 전개함에 따라 옴니채널 분석이 우선시되고 있습니다. 이러한 동향들이 맞물리면서 멀티 터치 어트리뷰션 시장은 모든 주요 지역에서 확대되는 예산을 확보하게 될 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, multi-touch attribution market size in 2026 is estimated at USD 2.76 billion, growing from 2025 value of USD 2.43 billion with 2031 projections showing USD 5.17 billion, growing at 13.41% CAGR over 2026-2031.
This report is Segmented by Attribution Model (Algorithmic/Data-Driven, Linear, Time-Decay, and More), Component (Solutions, and Services), Deployment Mode (Cloud, and On-Premise), Organization Size (Small and Medium Enterprises, and Large Enterprises), End-User Industry (Retail and E-Commerce, BFSI, IT and Telecom, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Multi-Touch Attribution Market Trends and Insights
Increasing First-Party Data Strategies Spurred by Cookie-Less Browsers
Third-party cookie deprecation has pushed companies to build consent-based data foundations anchored in customer data platforms. Brands integrating identity resolution, differential privacy, and secure computation are reporting higher lifetime value and lower acquisition costs. As data flows shift from probabilistic to deterministic, demand rises for attribution engines able to ingest hashed emails, loyalty IDs, and clean-room outputs while honoring regional privacy laws. Vendors that embed native consent orchestration and robust governance are winning large contracts, particularly in regulated industries.
Proliferation of Omnichannel Retail in Asia Fueling Complex Journeys
Asia-Pacific retailers now blend in-app, live-stream, and in-store touchpoints inside super-apps and unified wallets, generating intricate conversion paths. Gen Z shoppers expect seamless experiences, forcing merchants to deploy attribution that maps social discovery, QR-code activations, and store purchases in one graph. Early adopters confirm double-digit improvements in marketing efficiency after shifting from last-click to algorithmic models able to weight upper-funnel engagements.
Signal Loss from Privacy Regulations Hindering Data Collection
Rules such as GDPR and CPRA restrict cookies, cross-site tracking, and user profiling. Marketers face thinner datasets, heavier reliance on modeled conversions, and tougher consent workflows. Many respond by investing in clean rooms and additive noise techniques, yet attribution precision still drops when opt-out rates climb. Compliance expenses divert budgets from innovation, and perpetual policy changes create planning uncertainty.
Other drivers and restraints analyzed in the detailed report include:
- Rise of Retail Media Networks Elevating Offline-to-Online Attribution Needs
- Programmatic CTV Advertising Adoption in North America
- Marketing-Ops Talent Shortage for Advanced Analytics Deployment
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Algorithmic and data-driven frameworks controlled 34.25% share in 2025 and will expand at 14.05% CAGR to 2031, marking the clear shift from rule-based to machine-learning approaches. These models parse billions of touchpoints to assign conversion credit dynamically, eliminating constant rule tweaking and boosting predictive accuracy. Linear, time-decay, and U-shape approaches persist for transitional mandates or single-channel campaigns but are ceding ground as marketers witness higher return on ad spend under probabilistic, AI-powered calculations. Meridian, Mix Modeler, and similar offerings embed causal inference that benchmarks true lift, while self-serve interfaces let non-technical teams launch tests without coding.
Continued investment in algorithmic engines will lift the multi-touch attribution market as brands demand faster insights and cross-device granularity. When advanced methodologies are paired with privacy-tech layers, enterprises balance compliance and performance, reinforcing adoption momentum. Early pilots reveal that brands replacing last-click with algorithmic models have trimmed wasted spend by double digits, steering budget to channels previously undervalued.
Solutions still provided 69.10% of 2025 revenue by delivering the core data ingestion, modeling, and visualization stack that defines the multi-touch attribution market. Yet services are accelerating at a 15.85% CAGR as enterprises realize the need for strategy consulting, data mapping, and model governance. Large brands tap integration partners to link point-of-sale data, CRM events, streaming logs, and consent strings, underscoring why services revenue rises faster than licenses.
Managed services further appeal to organizations confronting skill shortages. Outsourced analysts fine-tune algorithm weights, run incrementality studies, and interpret dashboards for C-suite decisions. This hands-on support not only raises renewal rates for platform vendors but also drives incremental market revenue as post-implementation optimization becomes a multi-year engagement.
Complete Report Scope:
- By Attribution Model
- Algorithmic/Data-Driven
- Linear
- Time-Decay
- U-Shape/Position-Based
- Others (Custom, First/Last Touch)
- By Component
- Solutions
- Services
- Consulting
- Integration and Deployment
- Support and Maintenance
- By Deployment Mode
- Cloud
- On-Premise
- By Organization Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By End-User Industry
- Retail and E-commerce
- BFSI
- IT and Telecom
- Consumer Electronics and Durables
- Travel and Tourism
- Healthcare and Life Sciences
- Media and Entertainment
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Nordics
- Rest of Europe
- South America
- Brazil
- Rest of South America
- Asia Pacific
- China
- Japan
- India
- South East Asia
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Gulf Cooperation Council Countries
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 39.20% of global revenue in 2025, driven by deep programmatic spend, connected-TV scale, and early traction for privacy-enhancing technologies. The United States is the epicenter for AI experimentation in marketing measurement, while Canada advances omnichannel retail analytics and Mexico emerges as a high-growth frontier for e-commerce attribution.
Europe ranks second, shaped by the General Data Protection Regulation, which positions privacy-by-design as a non-negotiable buying criterion. Germany favors B2B attribution for manufacturing export chains, the United Kingdom emphasizes finance and retail, and France is scaling retail-media measurement as supermarkets diversify revenue streams. Nordic countries stand out for mobile-first attribution sophistication, aided by broad 5G coverage and high app penetration.
Asia-Pacific is the fastest-growing region at 14.85% CAGR to 2031, reflecting mobile-centric consumer behavior, super-app ecosystems, and live-stream commerce. China pilots attribution that stitches live-stream interactions, social referrals, and in-store QR code scans, illustrating demand for models that parse intertwined touchpoints. Japan pushes cross-device attribution for connected-TV and gaming, while India's expanding digital payments infrastructure fuels attribution needs in retail and fintech. Southeast Asian markets, from Singapore to Indonesia, prioritize omnichannel analytics as brick-and-mortar chains launch digital storefronts. Collectively, these dynamics ensure the multi-touch attribution market captures expanding budgets across all major geographies.
- Adobe Inc.
- Alphabet Inc. (Google Analytics 360)
- AppsFlyer Ltd.
- Adjust GmbH
- Branch Metrics Inc.
- C3 Metrics Inc.
- CaliberMind Inc.
- Conversion Logic Inc.
- Engagio Inc. (Demandbase)
- HubSpot Inc.
- Improvado Inc.
- Impact.com Inc.
- LeanData Inc.
- LeadsRx Inc. (Acquire.io)
- Merkle Inc.
- Model N Inc.
- Neustar Inc.
- NielsenIQ (VisualIQ)
- Oracle Corp. (Eloqua)
- Rockerbox Inc.
- SAP SE
- SegmentStream Ltd.
- Singular Labs Inc.
- The Trade Desk Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing First-Party Data Strategies Spurred by Cookie-less Browsers
- 4.2.2 Proliferation of Omnichannel Retail in Asia Fueling Complex Journeys
- 4.2.3 Rise of Retail Media Networks Elevating Offline-to-Online Attribution Needs
- 4.2.4 Programmatic CTV Advertising Adoption in North America
- 4.2.5 AI-Powered Marketing Automation Suites Bundling Attribution Natively
- 4.3 Market Restraints
- 4.3.1 Signal Loss from Privacy Regulations (GDPR, CPRA) Hindering Data Collection
- 4.3.2 Marketing-Ops Talent Shortage for Advanced Analytics Deployment
- 4.3.3 High Integration Costs with Legacy MarTech Stacks in Europe
- 4.3.4 Disparate ID Graph Standards Limiting Cross-Device Stitching Accuracy
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Attribution Model
- 5.1.1 Algorithmic/Data-Driven
- 5.1.2 Linear
- 5.1.3 Time-Decay
- 5.1.4 U-Shape/Position-Based
- 5.1.5 Others (Custom, First/Last Touch)
- 5.2 By Component
- 5.2.1 Solutions
- 5.2.2 Services
- 5.2.2.1 Consulting
- 5.2.2.2 Integration and Deployment
- 5.2.2.3 Support and Maintenance
- 5.3 By Deployment Mode
- 5.3.1 Cloud
- 5.3.2 On-Premise
- 5.4 By Organization Size
- 5.4.1 Small and Medium Enterprises (SMEs)
- 5.4.2 Large Enterprises
- 5.5 By End-User Industry
- 5.5.1 Retail and E-commerce
- 5.5.2 BFSI
- 5.5.3 IT and Telecom
- 5.5.4 Consumer Electronics and Durables
- 5.5.5 Travel and Tourism
- 5.5.6 Healthcare and Life Sciences
- 5.5.7 Media and Entertainment
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Nordics
- 5.6.2.5 Rest of Europe
- 5.6.3 South America
- 5.6.3.1 Brazil
- 5.6.3.2 Rest of South America
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South East Asia
- 5.6.4.5 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Gulf Cooperation Council Countries
- 5.6.5.1.2 Turkey
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Adobe Inc.
- 6.4.2 Alphabet Inc. (Google Analytics 360)
- 6.4.3 AppsFlyer Ltd.
- 6.4.4 Adjust GmbH
- 6.4.5 Branch Metrics Inc.
- 6.4.6 C3 Metrics Inc.
- 6.4.7 CaliberMind Inc.
- 6.4.8 Conversion Logic Inc.
- 6.4.9 Engagio Inc. (Demandbase)
- 6.4.10 HubSpot Inc.
- 6.4.11 Improvado Inc.
- 6.4.12 Impact.com Inc.
- 6.4.13 LeanData Inc.
- 6.4.14 LeadsRx Inc. (Acquire.io)
- 6.4.15 Merkle Inc.
- 6.4.16 Model N Inc.
- 6.4.17 Neustar Inc.
- 6.4.18 NielsenIQ (VisualIQ)
- 6.4.19 Oracle Corp. (Eloqua)
- 6.4.20 Rockerbox Inc.
- 6.4.21 SAP SE
- 6.4.22 SegmentStream Ltd.
- 6.4.23 Singular Labs Inc.
- 6.4.24 The Trade Desk Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


