

|
시장보고서
상품코드
2124456
인도의 레이저 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)India Laser - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
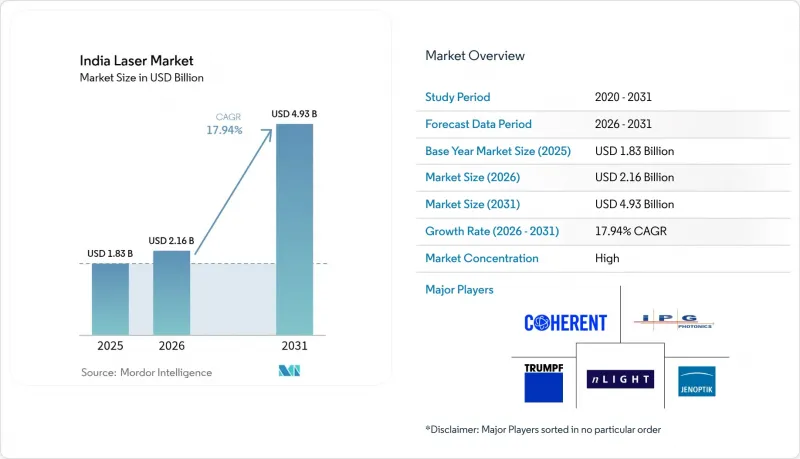
에 의하면, 인도의 레이저 시장 규모는 2025년 18억 3,000만 달러로 평가되었습니다. 2026년 21억 6,000만 달러에서 2031년까지 49억 3,000만 달러로 확대되고 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 17.94%를 나타낼 전망입니다.
본 보고서는 레이저의 유형(파이버, 고체, CO₂, 다이오드, 엑시머 등), 출력(저출력, 중출력, 고출력), 용도(재료 가공, 통신 등), 최종 사용자 산업(자동차, 항공우주 및 방위, 일렉트로믹스 및 반도체, 의료 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
인도의 레이저 시장 동향 및 인사이트
반도체 팹에 대한 정부의 지원책
‘인도 반도체 미션’에 기반한 정책 지원으로 10개의 팹이 승인되었으며, 1.6락 크롤(192억 달러)의 자금이 조성되었습니다. 각 팹에는 서브마이크론 공차로 작동이 요구되는 레이저 다이싱, 마킹, 스크라이빙 장비가 도입되어 있습니다. ‘수출 촉진 자본재(Export Promotion Capital Goods)’ 제도에 따른 무관세 수입으로 인해 소유 비용이 18%-22% 절감되었으며, 가동률이 높은 파이버 플랫폼의 투자 회수 기간이 단축되고 있습니다. 마이크론(Micron)사의 사난드 공장만 해도 가동 개시 후에는 수십 대의 레이저식 검사·마킹 스테이션이 필요하게 됩니다. 팹 건설 전체를 놓고 보면, 2030년까지 설치된 레이저 대수가 15배로 확대될 것으로 예상되어, 장기간에 걸친 서비스 및 소모품 수요가 확실해질 것입니다.
EV·배터리 생산 라인의 급속한 보급
1,810억 루피(22억 달러) 규모의 ‘첨단 화학 배터리 PLI’는 50GWh의 배터리 생산 능력 파이프라인을 창출하고 있으며, 알루미늄과 구리의 접합에는 레이저 용접이 적합합니다. 이를 통해 스폿 용접에 비해 접합부의 저항을 18% 저감할 수 있습니다. PM E-DRIVE 제도에 따른 보조금은 160만 대의 전동 이륜차와 50만 대의 전동 삼륜차를 지원하며, 각 배터리 팩은 AIS-156 충돌 안전 기준을 충족하기 위해 레이저 심 용접을 채택하고 있습니다. 원격 레이저 용접을 도입한 자동차 OEM 각사에서는 저항 용접법에 비해 루프 심 용접의 사이클 시간이 30% 단축된 것이 확인되었습니다. 그 결과, 라인 밀도 증가에 따라 고출력에 대한 수요는 플라즈마 커터에서 수 kW급 연속파 파이버 레이저 장치로 전환되고 있습니다.
고출력 파이버 레이저의 높은 설비 투자 비용
15만-40만 달러 가격대의 수 kW급 장비는 순이익률이 12%-18%인 위탁 가공 업체의 재무 상황을 압박하고 있습니다. 리스 금융 이용률은 25% 미만에 그치고 있으며(독일에서는 60%-70%), 구매자는 9%-11%의 금리로 운전자금 대출을 받을 수밖에 없어 투자 회수 기간이 4년 이상 소요되고 있습니다. 재생 레이저의 중고 시장이 존재하지 않기 때문에 실질적인 지출이 2배로 불어났고, 구매 지연이 겹치면서 2025년 IPG의 인도 내 매출액은 전년 대비 8% 감소했습니다. 또한, 3급 도시의 중소기업 사용자들은 용도 랩을 이용할 수 없어 기술적 위험에 대한 우려가 커지면서 수주 전환이 지연되고 있습니다.
부문별 분석
2025년 매출의 41.23%를 파이버 플랫폼이 차지했으며, 판금 절단, 배터리 탭 용접, PCB 마킹에 대한 적합성이 두드러집니다. 인도의 레이저 시장에서 파이버 시스템 시장 규모는 4배 이상 확대될 것으로 예측됩니다. 이는 팹, EV 생산 라인, 태양광 발전소가월플러그 효율 40%를 초과하는 단일 모드 광원으로의 표준화를 서두르고 있기 때문입니다. 초고속 파이버 레이저는 현재로서는 틈새 시장이지만, 의료기기 분야의 펨토초 마이크로 머시닝 및 스마트폰 커버 글라스용 투명 기판 천공 가공을 배경으로 연평균 성장률(CAGR) 19.18%로 성장하고 있습니다. 고체 Nd-YAG 레이저 및 다이오드 여기형 레이저는 보석 용접 및 시계 제조 분야에서 여전히 중요한 역할을 하고 있으며, 그 지위는 순수한 성능보다는 기존 설비에 대한 익숙함 덕분에 유지되고 있습니다. CO₂ 레이저는 여전히 아크릴, 목재, 가죽 절단에 사용되고 있지만, 납기 기한이 점점 더 촉박해짐에 따라 많은 위탁 가공 업체들은 유지보수를 효율화하기 위해 2파장 대응 설비를 단계적으로 폐지하고 있습니다.
연구 및 방위 분야에서는 엑시머 레이저, 자외선 레이저, 그리고 새롭게 등장한 테라헤르츠 광원이 각각의 전문적인 역할을 담당하고 있습니다. 인도 우주 연구 기관(ISRO)이 2025년 12월에 고조파 발생 기능을 갖춘 펨토초 레이저 시스템에 대한 입찰을 진행한 것은 국립 연구소가 양자 광학 및 고에너지 실험 분야에서 주도권을 잡으려 하고 있음을 여실히 보여줍니다. 인도 과학산업연구위원회(CSIR)는 계측용 주파수 안정화 헬륨-네온 레이저를 조달하고 있는데, 이는 저출력이지만 극히 높은 안정성을 갖춘 벤치탑 장치에 대한 수요가 여전히 뿌리 깊음을 시사합니다. 염료 레이저나 자유전자 레이저의 구성은 여전히 학술적인 희귀품에 그치고 있지만, 이 분야의 획기적인 발전은 10년 이내에 상용 파장으로 전환되는 경우가 많으며, 현재의 예측 기간을 훨씬 넘어선 후에도 혁신 주기가 인도의 레이저 시장을 지속적으로 활성화할 것임이 보장됩니다.
1-100와트의 중출력 레이저는 2025년 매출의 48.67%를 차지했으며, 인도의 대부분의 작업 현장에서 볼 수 있는 일련번호 각인, 셀렉티브 솔더링, 박판 금속 절단 등의 작업에 대응하고 있습니다. 플러그 앤 플레이 방식의 공랭 기능, 220볼트 지원, 그리고 전국을 커버하는 48시간 이내 서비스 체제를 통해 총 가동 중단 시간을 2% 미만으로 억제하고 있으며, 이는 중소기업에게 매우 중요한 판매 포인트입니다. 100와트를 초과하는 고출력 시스템의 인도의 레이저 시장 점유율은 급속히 상승하고 있으며, 이는 알루미늄 배터리 케이스나 20mm 두께의 선박용 강판 블랭크를 플라즈마로는 달성할 수 없는 속도로 용접하는 수 kW급 용접 셀과 밀접한 관련이 있습니다. 2025년 8월 가동을 시작한 TRUMPF의 푸네 공장에서는 현재 6kW에서 12kW의 디스크 광원 및 파이버 광원을 현지에서 조립하고 있으며, 리드 타임을 8-10주로 단축함으로써 출하 불확실성을 우려하는 OEM 각사를 안심시키고 있습니다.
시스템 통합사업자들은 여전히 기술 격차에 직면해 있습니다. 원격 용접에 요구되는 0.1mm 미만의 경로 정밀도로 6축 로봇을 프로그래밍할 수 있는 업체는 10곳 중 3곳에 불과하여, 지방으로의 확산이 제한되고 있습니다. 한편, 1와트 미만의 저출력 분야에서는 바코드 스캐너,스마트폰의 깊이 센서, 위치 정렬 모듈 분야에서 여전히 출하 대수 1위를 유지하고 있습니다. 그러나 평균 판매 가격(ASP) 하락으로 인해, 휴대전화 조립에 따른 출하 대수가 폭발적으로 증가하고 있음에도 불구하고, 이 분야가 인도의 레이저 시장 규모에서 차지하는 비중은 극히 미미합니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the India laser market size is projected to expand from USD 1.83 billion in 2025 and USD 2.16 billion in 2026 to USD 4.93 billion by 2031, registering a CAGR of 17.94% between 2026 and 2031.
This report is Segmented by Laser Type (Fiber, Solid-State, CO2, Diode, Excimer, and More), Power Output (Low-Power, Medium-Power, and High-Power), Application (Material Processing, Communication, and More), End-User Industry (Automotive, Aerospace and Defense, Electronics and Semiconductors, Healthcare, and More). Market Forecasts are Provided in Terms of Value (USD).
India Laser Market Trends and Insights
Government Incentives For Semiconductor Fabs
Policy support under the India Semiconductor Mission approved 10 fabs with INR 1.6 lakh crore (USD 19.2 billion) committed, each embedding laser dicing, marking and scribing tools that must run at sub-micron tolerances. Zero-duty imports under the Export Promotion Capital Goods window cut ownership cost by 18%-22%, compressing payback periods on high-uptime fiber platforms. Micron's Sanand plant alone will require several dozen laser-based inspection and marking stations once operations commence. Collectively, the fab build-out implies a 15-fold scale-up in installed laser base by 2030, locking in long-tail service and consumables demand.
Rapid Adoption of EV And Battery Fabrication Lines
The Advanced Chemistry Cell PLI of INR 18,100 crore (USD 2.2 billion) creates a 50 GWh battery capacity pipeline that favors laser welding for aluminum-to-copper joints, cutting joint resistance by 18% relative to spot welding. Subsidies under the PM E-DRIVE scheme support 1.6 million electric two-wheelers and 0.5 million three-wheelers, each battery pack relying on laser seam welds to meet AIS-156 crash norms. Automotive OEMs adapting remote laser welding have recorded 30 % faster roof-seam cycles versus resistance methods. Growing line densities are therefore shifting high-power demand from plasma cutters to multi-kilowatt continuous-wave fiber units.
High Capex Of High-Power Fiber Lasers
Multi-kilowatt units priced between USD 150,000 and USD 400,000 strain balance sheets of job shops operating on 12%-18% net margins. Lease finance penetration is below 25% versus 60%-70% in Germany, forcing buyers into working-capital loans at 9%-11% interest, stretching paybacks beyond four years. The absence of a secondary market for refurbished lasers doubles the net outlay, while deferred purchases pressured IPG's India revenue to fall 8% year-over-year in 2025. SME adopters in tier-3 cities also lack access to application labs, raising perceived technical risk and slowing order conversion.
Other drivers and restraints analyzed in the detailed report include:
- Surge In Domestic Electronics Manufacturing Clusters
- PLI For Solar Module Lines Requiring Laser Scribing
- Rupee Volatility Vs USD/CNY
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fiber platforms dominated 41.23 % of 2025 revenue, underlining their fit for sheet-metal cutting, battery tab welding and PCB marking. The india laser market size for fiber systems is projected to expand by more than four-fold as fabs, EV lines and solar plants race to standardize on single-mode sources with wall-plug efficiencies exceeding 40%. Ultrafast fiber lasers, though just a niche today, are climbing at a 19.18% CAGR on the back of femtosecond micro-machining in medical devices and transparent-substrate drilling for smartphone cover glass. Solid-state Nd-YAG and diode-pumped variants keep resonance in jewelry welding and watchmaking, protected by installed-base familiarity rather than raw performance. CO2 units still cut acrylic, wood and leather, yet many job shops are shedding dual-wavelength setups to streamline maintenance under tighter delivery windows.
In research and defense, excimer, ultraviolet and emerging terahertz sources fill specialized roles. ISRO's December 2025 tender for a harmonics-enabled femtosecond system underscores how national labs are staking claims in quantum optics and high-energy experiments. The Council of Scientific and Industrial Research procured frequency-stabilized helium-neon lasers for metrology, hinting at enduring demand for low-power but ultrastable benches. Dye and free-electron configurations remain academic curiosities, yet breakthroughs here often migrate to commercial wavelengths within a decade, ensuring that innovation cycles continue to refresh the india laser market long after the present forecast horizon.
Medium-power lasers between 1 and 100 watts accounted for 48.67 % of 2025 revenue, covering serial-number marking, selective soldering and thin-metal cutting tasks that populate most Indian workshops. Their plug-and-play air cooling, 220-volt compatibility and 48-hour nationwide service reach keep total downtime below 2 %, a critical selling point for SMEs. The india laser market share for high-power systems above 100 watts is rising fast, tied to multi-kilowatt weld cells that fuse aluminum battery enclosures and 20-millimeter ship-steel blanks at speeds unattainable by plasma. TRUMPF's Pune factory, opened in August 2025, now assembles 6 kW through 12 kW disk and fiber sources locally, slicing lead times to 8-10 weeks and comforting OEMs wary of shipment uncertainty.
System integrators still confront a skills gap. Only three in ten can program six-axis robots to the sub-0.1 mm path accuracy that remote welding demands, limiting provincial roll-outs. Conversely, the low-power tier below 1 watt keeps volume leadership in barcode scanners, smartphone depth sensors and alignment modules. ASP compression, however, means this tier contributes a minor fraction of india laser market size, even as shipment counts explode alongside handset assembly.
Complete Report Scope:
- By Laser Type
- Fiber Laser
- Solid-State Laser (Nd-YAG, DPSS etc.)
- CO2 Laser
- Diode / Direct Semiconductor Laser
- Excimer / UV Laser
- Ultrafast Fiber Laser
- Other Laser Types
- By Power Output
- Low-Power (less than 1 W)
- Medium-Power (1-100 W)
- High-Power (above 100 W)
- By Application
- Material Processing (Cutting, Welding, Marking)
- Communication and Optical Storage
- Medical and Aesthetic
- Instrumentation and Measurement
- Defense and Security
- Research and Development
- Consumer Electronics
- Other Applications
- By End-User Industry
- Automotive
- Aerospace and Defense
- Electronics and Semiconductors
- Healthcare
- Telecommunications
- Research Institutions
- Other End-User Industries
List of Companies Covered in this Report:
- IPG Photonics Corporation
- Coherent Corp.
- TRUMPF SE + Co. KG
- nLIGHT, Inc.
- Jenoptik AG
- Lumentum Holdings Inc.
- MKS Instruments, Inc. (Spectra-Physics)
- Han's Laser Technology Industry Group Co., Ltd.
- Wuhan Raycus Fiber Laser Technologies Co., Ltd.
- Synrad Inc. (Novanta Inc.)
- SPI Lasers UK Ltd.
- Laserline GmbH
- Maxphotonics Co., Ltd.
- EKSPLA UAB
- EdgeWave GmbH
- Toptica Photonics AG
- Amplitude Laser Group (Amplitude SAS)
- Light Conversion UAB
- Bystronic Laser AG
- Litron Lasers Ltd.
- HUBNER Photonics GmbH
- Epilog Corporation
- Universal Laser Systems, Inc.
- JPT Opto-electronics Co., Ltd.
- IPG Laser India Pvt. Ltd.
- Sahajanand Laser Technology Ltd. (SLTL Group)
- Additive India Tech Pvt. Ltd.
- Laser Technologies Pvt. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Domestic Electronics Manufacturing Clusters
- 4.2.2 Rapid Adoption of EV and Battery Fabrication Lines
- 4.2.3 Government Incentives for Semiconductor Fabs
- 4.2.4 Expansion of Laser-Based Additive Manufacturing Startups
- 4.2.5 Rising Procurement of Laser-Based LiDAR Sensors by Smart-City Projects
- 4.2.6 PLI for Solar Module Lines Requiring Laser Scribing
- 4.3 Market Restraints
- 4.3.1 High Capex of High-Power Fiber Lasers
- 4.3.2 Rupee Volatility vs USD/CNY
- 4.3.3 Inter-State GST Credit Delays on Capital Machinery
- 4.3.4 Limited Local Supply Chain for High-Precision Optical Isolators
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Laser Type
- 5.1.1 Fiber Laser
- 5.1.2 Solid-State Laser (Nd-YAG, DPSS etc.)
- 5.1.3 CO2 Laser
- 5.1.4 Diode / Direct Semiconductor Laser
- 5.1.5 Excimer / UV Laser
- 5.1.6 Ultrafast Fiber Laser
- 5.1.7 Other Laser Types
- 5.2 By Power Output
- 5.2.1 Low-Power (less than 1 W)
- 5.2.2 Medium-Power (1-100 W)
- 5.2.3 High-Power (above 100 W)
- 5.3 By Application
- 5.3.1 Material Processing (Cutting, Welding, Marking)
- 5.3.2 Communication and Optical Storage
- 5.3.3 Medical and Aesthetic
- 5.3.4 Instrumentation and Measurement
- 5.3.5 Defense and Security
- 5.3.6 Research and Development
- 5.3.7 Consumer Electronics
- 5.3.8 Other Applications
- 5.4 By End-User Industry
- 5.4.1 Automotive
- 5.4.2 Aerospace and Defense
- 5.4.3 Electronics and Semiconductors
- 5.4.4 Healthcare
- 5.4.5 Telecommunications
- 5.4.6 Research Institutions
- 5.4.7 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 IPG Photonics Corporation
- 6.4.2 Coherent Corp.
- 6.4.3 TRUMPF SE + Co. KG
- 6.4.4 nLIGHT, Inc.
- 6.4.5 Jenoptik AG
- 6.4.6 Lumentum Holdings Inc.
- 6.4.7 MKS Instruments, Inc. (Spectra-Physics)
- 6.4.8 Han's Laser Technology Industry Group Co., Ltd.
- 6.4.9 Wuhan Raycus Fiber Laser Technologies Co., Ltd.
- 6.4.10 Synrad Inc. (Novanta Inc.)
- 6.4.11 SPI Lasers UK Ltd.
- 6.4.12 Laserline GmbH
- 6.4.13 Maxphotonics Co., Ltd.
- 6.4.14 EKSPLA UAB
- 6.4.15 EdgeWave GmbH
- 6.4.16 Toptica Photonics AG
- 6.4.17 Amplitude Laser Group (Amplitude SAS)
- 6.4.18 Light Conversion UAB
- 6.4.19 Bystronic Laser AG
- 6.4.20 Litron Lasers Ltd.
- 6.4.21 HUBNER Photonics GmbH
- 6.4.22 Epilog Corporation
- 6.4.23 Universal Laser Systems, Inc.
- 6.4.24 JPT Opto-electronics Co., Ltd.
- 6.4.25 IPG Laser India Pvt. Ltd.
- 6.4.26 Sahajanand Laser Technology Ltd. (SLTL Group)
- 6.4.27 Additive India Tech Pvt. Ltd.
- 6.4.28 Laser Technologies Pvt. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


