

|
시장보고서
상품코드
2124480
석유 및 가스 엔지니어링 서비스 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Oil & Gas Engineering Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
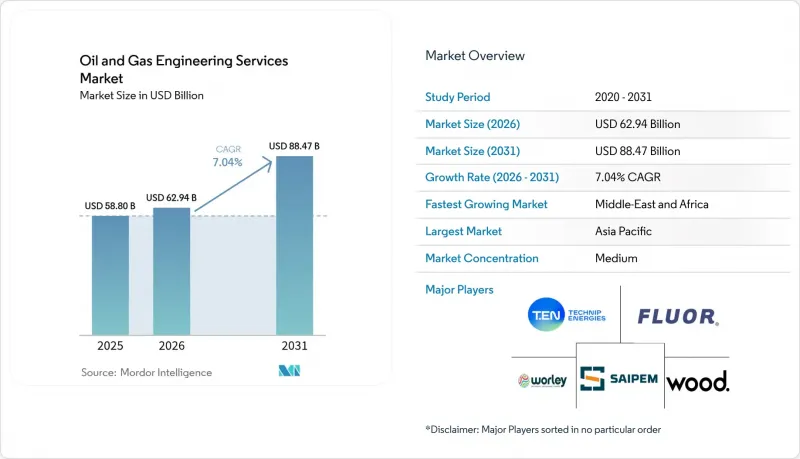
에 의하면, 석유 및 가스 엔지니어링 서비스 시장 규모는 2025년 588억 달러에서 2026년에는 629억 4,000만 달러에 이르고, 2026-2031년 CAGR 7.04%로 성장을 지속하여 2031년에는 884억 7,000만 달러에 달할 것으로 예측됩니다.

본 보고서는 유형별(업스트림, 중류, 하류), 서비스 유형별(설계 및 프런트엔드 엔지니어링, 상세 엔지니어링 및 EPCm 등), 용도별(탐사·생산, 정제 및 석유화학, LNG 및 가스 처리 등), 지역별(북미, 남미, 유럽 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 석유 및 가스 엔지니어링 서비스 시장 동향 및 인사이트
자동화 및 디지털 트윈 도입 확대
쉘(Shell)사의 ‘프렐류드(Prelude)’ FLNG 시설에 도입된 디지털 트윈은 프로젝트 실행 기간을 18% 단축하고 연간 유지보수 비용을 4,500만 달러 절감함으로써, 실시간 데이터 통합의 비즈니스적 유효성을 입증했습니다. 자산 소유자가 입찰 단계에서 디지털 트윈 산출물을 요구하는 사례가 증가하고 있으며, 서비스 범위는 예측 유지보수 및 시나리오 기반 최적화로 전환되고 있습니다. API 및 ISO 55000 표준 준수를 통해 이사회 승인이 신속화되고, 더 대규모의 변혁 프로그램을 위한 자금 조달이 가능해집니다. 통합 데이터 플랫폼에 투자해 온 서비스 제공업체들은 현재 수익성이 높은 성과 기반 계약을 수주하고 있습니다. 이러한 추세는 석유 및 가스 엔지니어링 서비스 시장에서 고급 분석 전문가에 대한 수요 증가로 직접 이어지고 있습니다.
신흥 시장의 LNG 생산 능력 확대
아프리카와 동남아시아를 합치면, 향후 5년 동안 전문 엔지니어링이 필요한 총액 1,800억 달러 이상의 LNG 프로젝트가 확정되어 있습니다. 카타르의 노스필드 확장 프로젝트만 해도, 상세 설계, 제조 지원, 디지털 통합을 아우르는 250억 달러 이상의 엔지니어링 계약이 발주되었습니다. 국제에너지기구(IEA)에 따르면, 가혹한 환경 조건의 입지에서는 기존 플랜트에 비해 단위당 엔지니어링 부담이 40% 증가합니다. 복잡성이 높아짐에 따라 청구 단가가 상승하여, LNG에 특화된 서비스 포트폴리오의 두 자릿수 성장을 뒷받침하고 있습니다. 이러한 추세는 견조한 수주 잔고를 지탱하며, 업스트림 부문 지출의 경기 순환적 침체로부터 서비스 제공업체를 보호하고 있습니다.
원유 가격의 주기성과 설비 투자 축소
2024년 원유 가격이 배럴당 70달러에서 95달러 사이에서 변동함에 따라 여러 프로젝트가 연기될 수밖에 없었고, 코노코Philips의 자본 예산은 12억 달러 삭감되었으며, 관련 엔지니어링 계약 규모도 15% 축소되었습니다. 현재 운영사들은 위험을 계약업체에 전가할 수 있는 유연한 범위 조항을 규정하고 있습니다. 메가 프로젝트에 대한 의존도가 높은 기업들은 현금 흐름의 변동에 직면하게 되며, 경기 침체기에는 유휴 설비를 유지해야 합니다. 규모가 작고 지역적으로 분산된 사업량은 수익 변동을 완화하는 데 도움이 되지만, 석유 및 가스 엔지니어링 서비스 시장의 단기적인 경기 침체를 극복하기 위해서는 여전히 견고한 재무 건전성이 필수적입니다.
부문별 분석
2025년, 업스트림 부문 서비스는 석유 및 가스 엔지니어링 서비스 시장에서 41.78%의 시장 점유율을 차지하고 있으며, 이는 심해 탐사, 비전통 자원 개발 및 증산 프로그램이 자본 집약적임을 여실히 보여줍니다. 지속적인 저류층 평가와 복잡한 유정 구조에는 지하 및 지상 엔지니어링을 통합한 접근 방식이 요구되지만, 이를 대규모로 실행할 수 있는 경쟁사는 극소수에 불과합니다. 업스트림 부문의 업무에는 생산 최적화에 기여하고 개발 기간 전반에 걸쳐 계약 기간을 연장하는 디지털 필드 라이프사이클 모델링도 포함됩니다.
다운스트림 부문은 규모는 작지만, 정유사들이 수익성을 극대화하기 위해 석유화학 사업의 현대화 및 통합을 추진함에 따라 연평균 성장률(CAGR) 7.82%로 더 빠르게 성장하고 있습니다. 사우디 아람코의 200억 달러 규모의 자잔 콤플렉스는 다운스트림 분야의 성장세를 주도하는 고부가가치 프로젝트의 대표적인 예입니다. 환경 규제가 강화됨에 따라 유황 제거, 플레어 배출 감축, 에너지 효율화에 대한 기술적 요구 사항이 높아지고 있어 컨설팅 및 시공 관련 수익을 끌어올리고 있습니다. LNG 시설과 파이프라인을 핵심으로 하는 미드스트림 부문은 시장 전체의 약 27.65%를 차지하며, 장기적인 인프라 사업을 통해 안정적인 수익을 창출하고 있습니다. 이러한 동향들이 결합되어 석유 및 가스 엔지니어링 서비스 시장 전체에 걸쳐 균형 잡힌 비즈니스 기회가 형성되고 있습니다.
지역별 분석
아시아태평양은 2025년 세계 매출의 20.95%를 차지하며 1위를 기록하고 있습니다. 이는 2030년까지 1,500억 달러를 넘어설 것으로 예상되는 정유, 석유화학, LNG 분야에 대한 막대한 투자가 주도한 결과입니다. 중국의 탄소 중립 공약은 CCUS(이산화탄소 포집·활용·저장) 엔지니어링 수요를 자극하고 있는 반면, 인도의 하류 부문 확대는 복잡한 공정 유닛의 설계를 촉진하고 있습니다.
북미는 2025년에 큰 점유율을 차지했습니다. 셰일 생산 최적화, LNG 수출 터미널, 정유시설 개보수 등, 모두 에너지 효율에 중점을 둔 노력이 계속해서 주요 촉진요인으로 작용하고 있습니다. EPA(미국 환경보호청)의 메탄 규제로 인해 배기가스 제어 엔지니어링에 대한 수요가 증가하고 있으며, 퍼미안 분지에서는 대규모 브라운필드 개선 프로그램이 지속되고 있습니다. 캐나다의 오일샌드는 새로운 용매 기반 추출 방법이 필요한 탄소 강도 저감 프로젝트를 주도하고 있습니다.
중동 및 아프리카는 합쳐서 연평균 성장률(CAGR) 8.74%라는 가장 급격한 성장을 기록하고 있습니다. 사우디아라비아의 NEOM 이니셔티브, ADNOC의 루와이스 확장 계획, 카타르의 LNG 메가 프로젝트는 2,000억 달러를 초과하는 다년간의 사업 파이프라인을 형성하고 있습니다. 아프리카의 코랄 설(Coral Sul) FLNG와 나이지리아의 심해 유전들은 원격 환경 전문가들에게 절호의 기회를 제공합니다. 유럽에서는 탈탄소화 개조, 북해 유전 수명 연장, 그리고 ‘유럽 그린딜’ 프레임워크에 기반한 재생에너지 통합 프로젝트를 통해 안정적인 수요가 유지되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the oil and gas engineering services market size is expected to grow from USD 58.8 billion in 2025 to USD 62.94 billion in 2026 and is forecast to reach USD 88.47 billion by 2031 at 7.04% CAGR over 2026-2031.
This report is Segmented by Type (Upstream, Midstream, and Downstream), Service Type (Design and Front-End Engineering, Detailed Engineering and EPCm, and More), Application (Exploration and Production, Refining and Petrochemicals, LNG and Gas Processing, and More), and Geography (North America, South America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Oil & Gas Engineering Services Market Trends and Insights
Growing adoption of automation and digital twins
Shell's digital twin for its Prelude FLNG facility reduced project execution time by 18% and saved USD 45 million annually in maintenance, demonstrating the business case for real-time data integration. Asset owners are increasingly specifying digital-twin deliverables at the bidding stage, shifting the service scope toward predictive maintenance and scenario-based optimization. Alignment with API and ISO 55000 standards speeds board approvals and unlocks capital for larger transformation programs. Service providers that have invested in integrated data platforms now win higher-margin outcome-based contracts. This momentum directly feeds into the expanding demand for advanced analytics professionals within the oil and gas engineering services market.
LNG capacity build-out in emerging markets
Africa and Southeast Asia together have more than USD 180 billion in committed LNG projects that require specialized engineering over the next five years. Qatar's North Field expansion alone has issued over USD 25 billion in engineering contracts covering detailed design, fabrication support, and digital integration. Harsh-environment locations increase per-unit engineering intensity by 40% compared to legacy plants, according to the International Energy Agency. Higher complexity translates into premium billing rates, sustaining double-digit growth for LNG-focused service portfolios. The trend anchors robust order backlogs that cushion providers against cyclical dips in upstream spending.
Crude-price cyclicality and cap-ex pull-backs
Oil prices oscillating between USD 70 and USD 95 per barrel in 2024 forced multiple project deferrals, slicing ConocoPhillips' capital budget by USD 1.2 billion and shrinking associated engineering awards by 15%. Operators now stipulate flexible scope clauses that shift risk onto contractors. Firms heavily exposed to mega-projects face lumpy cash flows and must maintain idle capacity during downturns. Smaller, regionally diversified workloads help mitigate revenue volatility; however, balance-sheet resilience remains critical for weathering short-cycle pullbacks within the oil and gas engineering services market.
Other drivers and restraints analyzed in the detailed report include:
- Decarbonisation mandates (CCUS and methane abatement)
- Industry-wide cost optimisation imperatives
- Skilled-labour shortages in specialised disciplines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Upstream services held a 41.78% market share of the oil and gas engineering services market in 2025, underscoring the capital-intensive nature of deep-water exploration, unconventional resource development, and enhanced recovery programs. Continuous reservoir appraisal and complex well architectures demand integrated subsurface and surface engineering that few competitors can execute at scale. Upstream workloads also include digital field life-cycle modeling, which informs production optimization and extends contract duration across the development horizon.
The downstream arena, although smaller, is growing faster at 7.82% CAGR as refiners modernize and integrate petrochemicals to maximize margins. Saudi Aramco's USD 20 billion Jazan complex exemplifies the high-value projects driving downstream momentum. Stricter environmental rules raise technology requirements for sulfur removal, flare reduction, and energy efficiency, boosting consulting and execution revenues. Midstream, anchored by LNG facilities and pipelines, captures roughly 27.65%, providing steady income from long-dated infrastructure programs. Together, these dynamics reinforce a balanced opportunity set across the oil and gas engineering services market.
Complete Report Scope:
- By Type
- Upstream
- Midstream
- Downstream
- By Service Type
- Design and Front-End Engineering
- Detailed Engineering and EPCm
- Asset Integrity and Maintenance
- Digital Engineering (BIM, XR, Analytics)
- Consulting and Advisory
- By Application
- Exploration and Production
- Refining and Petrochemicals
- LNG and Gas Processing
- Pipeline and Storage
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South-East Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
The Asia-Pacific region led with 20.95% of global revenue in 2025, driven by massive investments in refining, petrochemicals, and LNG, exceeding USD 150 billion through 2030. China's carbon-neutrality pledge stimulates CCUS engineering demand, while India's downstream build-out drives the design of complex process units.
North America contributed a significant share in 2025. Shale optimization, LNG export terminals, and refinery upgrades, each of which focuses on energy efficiency, remain key drivers. EPA methane rules sharpen demand for emissions-control engineering, and the Permian Basin sustains sizeable brown-field enhancement programs. Canada's oil sands drive carbon-intensity reduction projects that require novel solvent-based extraction methods.
The Middle East and Africa jointly register the sharpest expansion at 8.74% CAGR. Saudi Arabia's NEOM initiative, ADNOC's Ruwais expansion, and Qatar's LNG megaprojects form a multi-year workload pipeline surpassing USD 200 billion. Africa's Coral Sul FLNG and Nigerian deep-water fields open premium opportunities for remote-environment specialists. Europe sustains stable demand through decarbonization retrofits, North Sea field life extension, and renewable integration projects under the European Green Deal framework.
- Wood Group PLC
- Worley Limited
- Technip Energies N.V.
- Fluor Corporation
- Saipem S.p.A.
- KBR Inc.
- Petrofac Limited
- Larsen & Toubro Technology Services Ltd.
- SNC-Lavalin Group Inc. (AtkinsRealis)
- Hatch Ltd.
- WSP Global Inc.
- Tetra Tech Inc.
- Toyo Engineering Corporation
- JGC Holdings Corporation
- McDermott International Ltd.
- Hyundai Engineering Co., Ltd.
- Samsung Engineering Co., Ltd.
- CIMC Raffles Offshore Ltd.
- Mannvit Engineering
- Citec Group Oy Ab
- Arseal Technologies
- QuEST Global Services Pte. Ltd.
- M&H Consulting Engineers LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing adoption of automation and digital twins
- 4.2.2 Industry-wide cost optimisation imperatives
- 4.2.3 Rising brown-field asset life-extension projects
- 4.2.4 LNG capacity build-out in emerging markets
- 4.2.5 Decarbonisation mandates (CCUS and methane abatement)
- 4.2.6 Surge in private upstream investment in Africa
- 4.3 Market Restraints
- 4.3.1 Crude-price cyclicality and cap-ex pull-backs
- 4.3.2 Skilled-labour shortages in specialised disciplines
- 4.3.3 Escalating ESG-driven compliance costs
- 4.3.4 Cyber-security and IP-theft concerns in remote delivery
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Supply-Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Upstream
- 5.1.2 Midstream
- 5.1.3 Downstream
- 5.2 By Service Type
- 5.2.1 Design and Front-End Engineering
- 5.2.2 Detailed Engineering and EPCm
- 5.2.3 Asset Integrity and Maintenance
- 5.2.4 Digital Engineering (BIM, XR, Analytics)
- 5.2.5 Consulting and Advisory
- 5.3 By Application
- 5.3.1 Exploration and Production
- 5.3.2 Refining and Petrochemicals
- 5.3.3 LNG and Gas Processing
- 5.3.4 Pipeline and Storage
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Russia
- 5.4.3.5 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South-East Asia
- 5.4.4.5 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 Saudi Arabia
- 5.4.5.1.2 United Arab Emirates
- 5.4.5.1.3 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Egypt
- 5.4.5.2.3 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Wood Group PLC
- 6.4.2 Worley Limited
- 6.4.3 Technip Energies N.V.
- 6.4.4 Fluor Corporation
- 6.4.5 Saipem S.p.A.
- 6.4.6 KBR Inc.
- 6.4.7 Petrofac Limited
- 6.4.8 Larsen & Toubro Technology Services Ltd.
- 6.4.9 SNC-Lavalin Group Inc. (AtkinsRealis)
- 6.4.10 Hatch Ltd.
- 6.4.11 WSP Global Inc.
- 6.4.12 Tetra Tech Inc.
- 6.4.13 Toyo Engineering Corporation
- 6.4.14 JGC Holdings Corporation
- 6.4.15 McDermott International Ltd.
- 6.4.16 Hyundai Engineering Co., Ltd.
- 6.4.17 Samsung Engineering Co., Ltd.
- 6.4.18 CIMC Raffles Offshore Ltd.
- 6.4.19 Mannvit Engineering
- 6.4.20 Citec Group Oy Ab
- 6.4.21 Arseal Technologies
- 6.4.22 QuEST Global Services Pte. Ltd.
- 6.4.23 M&H Consulting Engineers LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


