

|
시장보고서
상품코드
2125487
산업용 정지 장비 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Industrial Static Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
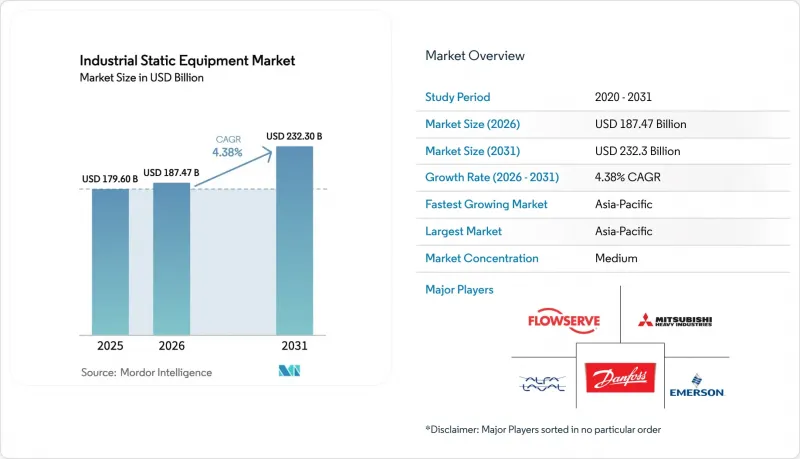
에 의하면, 산업용 정지 장비 시장 규모는 2025년에 1,796억 달러로 평가되었고, 2026년 1,874억 7,000만 달러에서 2031년까지 2,323억 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.38%를 나타낼 전망입니다.

본 보고서는 장비 유형별(밸브, 용광로·보일러, 열교환기, 기타), 구조 재료별(탄소강, 스테인리스 스틸, 합금강, 비철금속·복합재료), 정격 압력별(저압, 중압, 고압), 최종 사용자 산업별(석유 및 가스, 발전, 상·하수도 처리, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 산업용 정지 장비 시장 동향 및 인사이트
신흥 경제국의 급속한 산업화
2024년, 중국의 제조업 생산액은 전년 대비 6.2% 증가했으며, 인도의 산업 생산도 전년 대비 5.8% 증가했습니다. 이에 따라 밸브, 압력 용기, 열교환기가 각각 필요한 석유화학 단지, 제철소, 재생 가능 수소 허브의 건설이 가속화되고 있습니다. 또한, 일부 걸프 국가들도 수소 메가 프로젝트에 200억 달러 이상을 투자하며 고압 정지 장비에 대한 초기 수요를 견인하고 있습니다. 이러한 경제권에서는 단계적인 교체보다 그린필드에서의 신규 설치가 빈번하게 요구되고 있으며, 그 결과 여러 장비를 아우르는 대규모 수주가 발생하여 산업용 정적 장비 시장을 견인하고 있습니다. 정부 주도의 산업 회랑 및 외국인 직접 투자(FDI) 프로그램을 통해 예측 기간 동안 생산 능력 증대가 지속될 것으로 확실시되며, 수요는 견조한 추세를 유지할 것으로 전망됩니다.
석유 및 가스 업스트림 부문 및 LNG 인프라 확대
2024년 전 세계 LNG 액화 능력 증설은 카타르, 미국, 호주의 프로젝트에 힘입어 연간 4,200만 톤에 달했습니다. 이러한 프로젝트에서는 극저온용 밸브와 맞춤형 열교환기가 필수적입니다. 업스트림 부문의 설비 투자는 5,250억 달러까지 회복되어, 리드타임이 긴 해양 플랫폼, 가스 집하 시스템, 가스 처리 플랜트와 관련된 지속적인 설비 수주의 기반이 마련되었습니다. 사워 가스, 고온, 해저 설비 분야에서 실적이 입증된 공급업체는 우선 공급업체로서의 지위를 확보하여, 수십 년에 걸친 프로젝트 수명 주기 전반에 걸쳐 지속적인 수익을 강화하고 있습니다.
높은 자본 비용과 재생에너지 발전으로의 전환
2024년에는 전 세계 신규 발전 설비 용량의 85%를 재생에너지가 차지했으며, 화석 연료 자산과 관련된 보일러 및 화로 수주를 억제했습니다. 동시에 금리 상승으로 인해, 1기당 설치 비용이 5,000만 달러를 상회하는 설비 투자가 많은 고정식 장비 패키지의 수익성 기준이 높아지고 있습니다. 투자자들은 저탄소 또는 유연성이 높은 자산을 선호하기 때문에 기존 방식의 화력 발전 프로젝트는 지연되고 있으며, 대구경 용기 및 대용량 열회수 시스템에 대한 단기 수주 잔고는 감소하고 있습니다.
부문별 분석
밸브는 산업용 고정 설비 시장 규모의 가장 큰 부분을 차지했으며, 모든 공정에서 차단, 조절, 안전 기능에 폭넓게 활용되고 있어 2025년 매출의 32.86%를 차지했습니다. 교체 주기가 5-7년으로 비교적 짧고, 하나의 플랜트 내에 다수 설치되어 있기 때문에 높은 판매량이 예상됩니다. 열교환기의 산업용 고정 설비 시장 점유율은 규모는 작지만 급속히 확대되고 있습니다. 효율화 개조 의무화에 따라 2031년까지 열교환기의 매출액은 연평균 성장률(CAGR) 5.65%로 증가하고 있습니다. 각 제조업체는 가동률과 에너지 회수율을 높이기 위해 센서 및 방오 코팅 적용을 추진하고 있습니다.
로 및 보일러의 경우, 석탄 화력 발전소의 폐지가 진행되는 상황에서도 폐기물 발전 및 지역 난방 프로젝트를 통해 안정적인 수주가 이어지고 있습니다. 압력 용기는 생산량은 적지만, 맞춤형 설계, 엄격한 규격 준수, 최장 18개월에 달하는 긴 제조 일정으로 인해 고가 대에서 거래되고 있습니다. 디지털 통합은 이제 어디에서나 볼 수 있게 되었습니다. 스마트 밸브는 스템의 마찰이나 시트 부위의 상태를 전달하고, 열교환기 어레이는 오염 계수를 실시간으로 전송함으로써 운영 비용을 절감하는 예측 유지보수 전략을 가능하게 합니다.
탄소강은 2025년에도 매출 점유율 37.40%를 차지하는 비용 대비 효율이 높은 주력 소재로 남아, 상수도, HVAC, 중온 처리 라인의 일반적인 용도 수요를 충족시키고 있습니다. 그러나 정유시설, 석유화학 크래커, 복합 사이클 발전소 등에서 온도와 압력이 더욱 높아짐에 따라 합금강 수요가 증가하고 있으며, 이 부문은 연평균 성장률(CAGR) 5.78%로 성장을 지속하고, 있습니다. 사업자들은 우수한 합금을 사용함으로써 예기치 않은 가동 중단 시간을 줄이고 부식 관련 고장을 감소시킬 수 있다는 점을 인식하고, 수명 주기 전반에 걸친 비용을 점점 더 중요하게 여기고 있습니다. 그 결과, 중요 공정상의 중단과 관련된 보증 청구 및 보험료를 절감할 수 있게 됩니다.
스테인리스 스틸은 제품의 순도가 최우선으로 요구되는 식품, 음료, 의약품 부문에서 높은 평가를 받고 있으며, 균형 잡힌 중간 위치를 차지하고 있습니다. 비철금속과 복합재료는 틈새 시장이지만 점차 확대되는 시장 점유율을 차지하고 있습니다. 예를 들어, 티타늄 열교환기는 스테인리스 스틸 대체품에 비해 가격이 최대 8배나 비싸지만, 해안 지역의 냉각수 용도로 선호되어 채택되고 있습니다. 또한, 상압 탱크용 복합재 쉘도 부식성 화학물질 저장 용도로 채택이 확대되고 있어, 공급업체의 제품 포트폴리오를 확장하는 데 있어 소재 혁신이 수행하는 역할의 중요성이 부각되고 있습니다.
지역별 분석
아시아태평양은 정유시설 확장, 석탄에서 화학제품을 생산하는 플랜트, 정부 주도의 인프라 회랑 등 거의 끊이지 않는 프로젝트 진행에 힘입어 2025년에는 전 세계 매출의 42.10%를 차지했습니다. 중국과 인도의 산업용 고정 설비 시장 규모는 석유화학제품 생산, 철강 생산, 그리드 규모의 저장 시설이 가동을 시작함에 따라 상승 추세를 이어가고 있습니다. 일본과 한국은 엄격한 품질 기준을 충족하는 정밀 합금 열교환기 및 특수 밸브의 고수익 수주에 기여하고 있는 반면, 동남아시아 국가들에서는 제조 거점이 남쪽으로 이동함에 따라 주류인 탄소강 설비에 대한 수요가 증가하고 있습니다.
북미는 셰일가스 개발과 석유화학 원료 통합을 향한 뚜렷한 움직임에 힘입어 그 다음으로 큰 규모를 차지하고 있습니다. 미국은 LNG 수출 능력에서 세계를 선도하고 있으며, 극저온 압력 용기 및 트리플 오프셋 밸브가 필요로 하고 있습니다. 한편, 캐나다의 오일샌드 사업자들은 배출 강도를 낮추기 위해 고온 열교환기를 개조하고 있습니다. 니어쇼어링 추세에 따라 확대되고 있는 멕시코의 마키라도라 공장은 중압 탄소강 용기 수요를 뒷받침하고 있습니다. 지역별 탈탄소화 규제로 인해 첨단 열회수 증기 발생기 및 저NOx 공정 히터의 판매가 더욱 촉진되고 있습니다.
유럽에서는 효율 향상이나 수명 만료에 따른 교체를 목적으로, 성숙 단계에 접어들었으나 안정적인 수주 실적이 나타나고 있습니다. 신규 화석 연료 발전소가 여전히 적기 때문에 산업용 고정식 설비 시장 점유율 증가세는 완만하지만, 그 대신 수소 시범 프로젝트, 배터리 제조 시설, 지역 난방 확장에 자본이 유입되고 있습니다. 독일의 산업 클러스터에서는 용매 회수 시스템용 합금 열교환기가 우선적으로 채택되고 있는 반면, 스칸디나비아의 펄프 및 제지 공장에서는 부식을 줄이기 위해 복합재 소화조가 채택되고 있습니다. 동유럽은 EU가 지원하는 현대화 자금의 혜택을 받고 있으며, 신흥 화학 산업 거점에서 규격 인증을 받은 압력 용기 및 스테인리스 스틸 위생 밸브에 대한 수요가 촉진되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the industrial static equipment market size was valued at USD 179.6 billion in 2025 and estimated to grow from USD 187.47 billion in 2026 to reach USD 232.3 billion by 2031, at a CAGR of 4.38% during the forecast period (2026-2031).
This report is Segmented by Equipment Type (Valves, Furnaces/Boilers, Heat Exchangers, and More), Material of Construction (Carbon Steel, Stainless Steel, Alloy Steel, and Non-Ferrous and Composites), Pressure Rating (Low, Medium, and High), End-User Industry (Oil and Gas, Power Generation, Water and Wastewater, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Static Equipment Market Trends and Insights
Rapid Industrialization Across Emerging Economies
Manufacturing output in China climbed 6.2% during 2024 while India's industrial production grew 5.8% year-over-year, accelerating build-outs of petrochemical complexes, steel plants, and renewable hydrogen hubs that each need valves, pressure vessels, and heat exchangers. Several Gulf nations also committed more than USD 20 billion to hydrogen megaprojects, driving initial demand for high-pressure static assets. These economies frequently require entire greenfield installations rather than incremental replacements, resulting in large multi-equipment orders that lift the industrial static equipment market. Government-backed industrial corridors and foreign direct investment programs ensure capacity additions extend well into the forecast window, maintaining a positive demand trajectory.
Expansion of Upstream Oil and Gas and LNG Infrastructure
Global LNG liquefaction capacity additions totaled 42 million tpa in 2024, supported by projects in Qatar, the United States, and Australia that mandate cryogenic valves and custom heat exchangers. Upstream capital expenditure rebounded to USD 525 billion, setting the stage for sustained equipment orders tied to long-lead offshore platforms, gathering systems, and gas-processing plants. Suppliers with proven sour-gas, high-temperature, and subsea qualifications gain preferred-vendor status, reinforcing recurring revenue across multi-decade project lifecycles.
High Capital Cost and Shift Toward Renewable Generation
Renewables accounted for 85% of global new-build power capacity in 2024, suppressing boiler and furnace orders tied to fossil assets. Simultaneously, elevated interest rates raise hurdle rates for cap-ex-heavy static equipment packages that routinely eclipse USD 50 million per installation. Investors prefer low-carbon or flexible assets, delaying traditional thermal projects and trimming near-term order books for large-diameter vessels and high-capacity heat-recovery systems.
Other drivers and restraints analyzed in the detailed report include:
- Capacity Additions in Chemicals and Petrochemicals
- Stricter Emission Norms Driving Heat-Transfer Retrofits
- Volatile Prices of Special-Grade Steel and Alloys
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Valves generated the largest portion of the industrial static equipment market size, contributing 32.86% of 2025 revenue as their omnipresence spans isolation, regulation, and safety functions across every process. Their relatively short five-to-seven-year replacement cycles and multiplicity within a single plant drive high unit volumes. The industrial static equipment market share for heat exchangers, though smaller, is rising swiftly; mandated efficiency retrofits lift exchanger sales at a 5.65% CAGR through 2031. Manufacturers are embedding sensors and antifouling coatings to boost uptime and energy recovery.
Furnaces and boilers continue to register dependable orders from waste-to-energy and district-heating projects, even as coal retirements continue. Pressure vessels, while low in volume, command premium prices owing to custom engineering, stringent code compliance, and extended fabrication schedules that stretch up to 18 months. Digital integration is now ubiquitous: smart valves relay stem friction and seating integrity, while exchanger arrays transmit fouling coefficients in real time, enabling predictive maintenance strategies that shrink operating expenditure.
Carbon steel remained the cost-effective workhorse with 37.40% revenue share in 2025, meeting general service needs in water, HVAC, and moderate-temperature processing lines. Alloy steel, however, is gaining traction as refineries, petrochemical crackers, and combined-cycle plants push temperatures and pressures higher, giving the segment a 5.78% CAGR. Operators increasingly weigh total lifecycle expense, recognizing that superior alloys can cut unscheduled downtime and reduce corrosion-related failures, thereby trimming warranty claims and insurance premiums linked to critical-path outages.
Stainless steel occupies a balanced middle ground, prized in food, beverage, and pharmaceuticals, where product purity is paramount. Non-ferrous and composite materials claim a niche yet expanding foothold; titanium heat exchangers, for example, are preferred in coastal cooling-water service despite prices up to eight times higher than stainless alternatives. Composite shells for atmospheric tanks are also seeing uptake in corrosive chemical storage, underscoring material innovation's role in broadening supplier portfolios.
Complete Report Scope:
- By Equipment Type
- Valves
- Gate, Globe and Check
- Ball Valves
- Butterfly Valves
- Plug Valves
- Pressure-relief Valves
- Furnaces / Boilers
- Heat Exchangers
- Pressure Vessels
- Valves
- By Material of Construction
- Carbon Steel
- Stainless Steel
- Alloy Steel
- Non-ferrous and Composites
- By Pressure Rating
- Low (< 300 psi)
- Medium (300-900 psi)
- High (> 900 psi)
- By End-user Industry
- Oil and Gas
- Power Generation
- Chemicals and Petrochemicals
- Water and Wastewater
- Mining and Metals
- Food and Beverages
- Other End-user Industry
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific retained 42.10% of global revenue in 2025, underpinned by a near-constant pipeline of refinery expansions, coal-to-chemicals plants, and state-backed infrastructure corridors. The industrial static equipment market size across China and India continues its upward trajectory as petrochemical output, steel production, and grid-scale storage facilities come online. Japan and South Korea contribute high-margin orders for precision alloy exchangers and specialty valves that meet stringent quality norms, while Southeast Asian nations absorb mainstream carbon-steel equipment as manufacturing shifts southward.
North America ranks next, anchored by shale gas development and a pronounced push toward petrochemical feedstock integration. The United States leads in LNG export capacity, necessitating cryogenic pressure vessels and triple-offset valves, whereas Canada's oil-sands operators retrofit high-temperature exchangers to lower emissions intensity. Mexican maquiladora plants, expanding under nearshoring moves, bolster medium-pressure carbon-steel vessel demand. Regional decarbonization rules further stimulate sales of advanced heat-recovery steam generators and low-NOx process heaters.
Europe exhibits mature yet stable orders geared toward efficiency upgrades and end-of-life replacements. Industrial static equipment market share growth is modest as new fossil plants remain scarce; instead, capital flows into hydrogen pilot projects, battery manufacturing facilities, and district heating expansions. German industrial clusters prioritize alloy exchangers for solvent recovery systems, while Scandinavian pulp and paper mills adopt composite digesters to mitigate corrosion. Eastern Europe benefits from EU-supported modernization funds, stimulating demand for code-stamped pressure vessels and stainless-steel sanitary valves in emerging chemical hubs.
- Flowserve Corporation
- Emerson Electric Co.
- Alfa Laval A B
- Danfoss A/S
- Mitsubishi Heavy Industries, Ltd.
- KSB SE & Co. KGaA
- Velan Inc.
- Wartsila Oyj Abp
- Johnson Controls International plc
- Xylem Inc.
- SPX FLOW, Inc.
- L&T Valves Limited
- Paul Mueller Company
- Kelvion Holding GmbH
- Hamon & Cie (International) S.A.
- Nippon Steel Engineering Co., Ltd.
- Doosan Mecatec Co., Ltd.
- IHI Power Systems Co., Ltd.
- Hitachi Zosen Corporation
- CIMC Enric Holdings Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid industrialization across emerging economies
- 4.2.2 Expansion of upstream oil and gas and LNG infrastructure
- 4.2.3 Capacity additions in chemicals and petrochemicals
- 4.2.4 Stricter emission norms driving heat-transfer retrofits
- 4.2.5 Hydrogen economy retrofits for high-pressure equipment
- 4.2.6 Digital-twin adoption enabling predictive maintenance
- 4.3 Market Restraints
- 4.3.1 High capital cost and shift toward renewable generation
- 4.3.2 Volatile prices of special-grade steel and alloys
- 4.3.3 Supply-chain disruptions for exotic materials
- 4.3.4 Shortage of ASME-certified skilled fabricators
- 4.4 Industry Ecosystem Analysis
- 4.5 Regulatory Landscape and Standards
- 4.6 Technological Outlook (Edge and AI analytics)
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Equipment Type
- 5.1.1 Valves
- 5.1.1.1 Gate, Globe and Check
- 5.1.1.2 Ball Valves
- 5.1.1.3 Butterfly Valves
- 5.1.1.4 Plug Valves
- 5.1.1.5 Pressure-relief Valves
- 5.1.2 Furnaces / Boilers
- 5.1.3 Heat Exchangers
- 5.1.4 Pressure Vessels
- 5.1.1 Valves
- 5.2 By Material of Construction
- 5.2.1 Carbon Steel
- 5.2.2 Stainless Steel
- 5.2.3 Alloy Steel
- 5.2.4 Non-ferrous and Composites
- 5.3 By Pressure Rating
- 5.3.1 Low (< 300 psi)
- 5.3.2 Medium (300-900 psi)
- 5.3.3 High (> 900 psi)
- 5.4 By End-user Industry
- 5.4.1 Oil and Gas
- 5.4.2 Power Generation
- 5.4.3 Chemicals and Petrochemicals
- 5.4.4 Water and Wastewater
- 5.4.5 Mining and Metals
- 5.4.6 Food and Beverages
- 5.4.7 Other End-user Industry
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Flowserve Corporation
- 6.4.2 Emerson Electric Co.
- 6.4.3 Alfa Laval A B
- 6.4.4 Danfoss A/S
- 6.4.5 Mitsubishi Heavy Industries, Ltd.
- 6.4.6 KSB SE & Co. KGaA
- 6.4.7 Velan Inc.
- 6.4.8 Wartsila Oyj Abp
- 6.4.9 Johnson Controls International plc
- 6.4.10 Xylem Inc.
- 6.4.11 SPX FLOW, Inc.
- 6.4.12 L&T Valves Limited
- 6.4.13 Paul Mueller Company
- 6.4.14 Kelvion Holding GmbH
- 6.4.15 Hamon & Cie (International) S.A.
- 6.4.16 Nippon Steel Engineering Co., Ltd.
- 6.4.17 Doosan Mecatec Co., Ltd.
- 6.4.18 IHI Power Systems Co., Ltd.
- 6.4.19 Hitachi Zosen Corporation
- 6.4.20 CIMC Enric Holdings Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


