

|
시장보고서
상품코드
2124652
Wi-Fi : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Wi-Fi - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
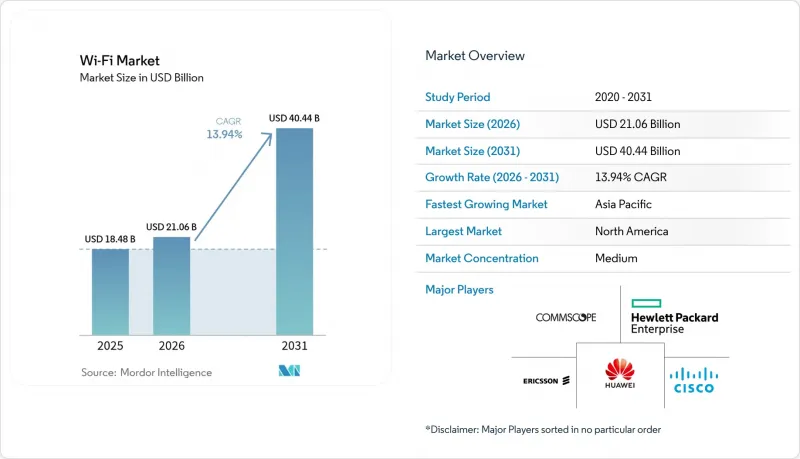
에 의하면, Wi-Fi 시장 규모는 2025년에 184억 8,000만 달러로 평가되었습니다. 2026년 210억 6,000만 달러에서 2031년까지 404억 4,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 13.94%를 나타낼 전망입니다.
본 보고서는 구성 요소(하드웨어, 솔루션, 서비스), 최종 사용자 산업 분야(일반 소비자, 기업·법인 캠퍼스, 교육, 의료, 호텔·소매, 산업·물류) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 Wi-Fi 시장 동향 및 인사이트
IoT 및 스마트 기기의 보급
기업에서는 액세스 포인트 1개당 100개가 넘는 연결 엔드포인트를 보유한 고밀도 센서 네트워크를 구축하고 있지만, 이러한 환경을 경제적으로 지원할 수 있는 것은 Wi-Fi 6E의 OFDMA 스케줄링 및 멀티유저 MIMO 기능뿐입니다. 스마트 빌딩 운영 사업자는 Wi-Fi 메시를 통해 HVAC(공조·환기·급배수), 조명, 감시 시스템을 통합함으로써 구조화 배선 비용을 40% 절감하고 예측 유지보수 분석을 실현하고 있습니다. 엣지 추론 워크플로우에서 10밀리초 미만의 응답 시간에 대한 수요로 인해 Wi-Fi 7의 멀티링크 작동이 주목받고 있습니다. 이는 부하가 걸린 상태에서도 지터 없는 트래픽을 유지할 수 있기 때문입니다. 산업 자동화 시범 사례에 따르면, 전용 6GHz 채널의 가동률은 99.9%인 반면, 혼잡한 5GHz 링크에서는 97.8%에 그치는 것으로 보고되어, 미션 크리티컬한 로봇 공학 분야에서 새로운 주파수 대역으로의 전환이 효과적임을 입증하고 있습니다. 이러한 장점 덕분에 조직들은 장기적인 생산성 향상을 대가로 더 높은 설비 투자를 수용하는 추세입니다.
스마트 시티 이니셔티브와 공공 Wi-Fi 구축
지방 자치 단체의 광대역 프로그램에서는 광활한 농촌 지역에서 광섬유보다 설치가 신속하고 자본 집약도가 낮기 때문에 디지털 포용의 주요 매체로 Wi-Fi가 점점 더 중요시되고 있습니다. 필리핀은 2028년까지 1만 7,000개의 바랑가이에 10만 곳 이상의 공공 핫스팟을 구축하기 위해 12억 달러를 투자하기로 결정했으며, 이 모델은 몇몇 신흥 경제국에서도 채택되고 있습니다. 유럽의 ‘디지털 데케이드(Digital Decade)’는 2030년까지 기가비트급 통신망을 구축하는 것을 목표로 하고 있으며, 산악 지대나 도서 지역에서는 Wi-Fi 7 메쉬를 비용 대비 효과가 높은 라스트 마일(last mile)의 대안으로 자리매김하고 있습니다. 각 도시는 교통, 대기 질, 긴급 대응 시스템을 위한 센서 백홀을 인프라에 접목하여 수익화를 도모하고 있으며, 효율성 향상을 통해 자체 자금을 조달하고 있습니다. OpenRoaming 협정에 따라 Wi-Fi와 5G 무선 기술을 융합한 뉴트럴 호스트형 구축은 로밍 요금이라는 새로운 수익원을 창출하는 동시에 시민들에게 원활한 연결 환경을 제공합니다.
비면허 대역의 주파수 대역 혼잡 및 간섭
맨해튼과 같이 인구 밀도가 높은 도시 지역에서는 Wi-Fi 6E 지원 하드웨어가 도입되어 있더라도 피크 시간대 이용 시 처리량이 60% 가까이 저하됩니다. 이는 레거시 기기가 2.4GHz 대역의 주파수 대역을 혼잡하게 만들고 있기 때문입니다. 전자레인지, 블루투스 지원 단말기, 구형 라우터 등이 겹쳐서 노이즈를 발생시키며, 적응형 알고리즘으로는 이를 완전히 피할 수 없습니다. 기업에서는 서비스 수준 목표를 충족하는 채널 계획을 수립하기 위해 스펙트럼 컨설턴트를 기용하는 사례가 늘고 있습니다. 광대한 캠퍼스의 경우, 이 서비스 비용은 5만-20만 달러에 달할 전망입니다. 규제 당국은 중요한 IoT 트래픽이 일반 소비자의 간섭을 받지 않고 작동할 수 있도록 CBRS와 유사한 준라이선싱 제도의 도입을 검토하고 있습니다. 6GHz 대역의 할당은 일시적으로 압박을 완화해 주겠지만, IoT 엔드포인트가 기하급수적으로 증가함에 따라 5년 이내에 포화 상태에 도달할 것으로 예측됩니다.
부문별 분석
2025년에는 액세스 포인트가 Wi-Fi 시장 점유율의 35.92%를 차지했으며, 이는 수익 구조가 변화하는 상황에서도 하드웨어의 중요성이 여전히 높음을 보여줍니다. 한편, 서비스 부문은 2031년까지 연평균 성장률(CAGR) 15.98%로 확대될 것으로 예측되며, 이는 초기 투자를 지속적인 운영 비용으로 전환하는 ‘Network-as-a-Service(Naas)’ 프레임워크로의 전환을 반영합니다. 비용 압박으로 인해 독립형 라우터와 레인지 익스텐더는 상품화가 진행되는 반면, 클라우드 네이티브 오케스트레이션 플랫폼이 기존 On-Premise 컨트롤러가 수행하던 정책 관리 및 분석 역할을 이어받고 있습니다. 관리형 서비스 제공업체(MSP)는 인공지능을 활용하여 채널 할당, 부하 분산, 이상 감지를 자동화하고 있으며, 그 결과 고객이 직접 운영하는 네트워크에 비해 예기치 않은 다운타임을 75% 줄이는 데 성공했습니다. 2031년까지 조직이 자산 소유보다 라이프사이클의 유연성을 우선시하게 됨에 따라, 성숙한 경제권에서 소프트웨어 및 서비스에 기인한 Wi-Fi 시장 규모는 하드웨어의 기여도를 능가할 것으로 예측됩니다.
이러한 변화는 소유권보다 성과를 중시하는 보다 광범위한 IT 조달 동향을 반영하고 있습니다. 사용량 기반 요금 체계를 통해 WLAN 비용은 이용률에 따라 변동하여 예산의 급격한 증가를 억제하고 CFO의 가시성을 향상시킵니다. 각 벤더는 예방적 유지보수, 보안 규정 준수, 실시간 경험 평가를 묶음 상품으로 제공함으로써 하드웨어 이외의 측면에서 차별화를 꾀하고 있습니다. 엣지 게이트웨이 및 내환경형 IoT 브리지는 규모는 작지만 빠르게 성장하고 있는 카테고리로, 진동, 분진, 극한 온도 등의 요인으로 인해 소비자용 기기를 사용할 수 없는 가혹한 산업 현장에서 안정적인 연결성을 제공합니다. 액세스 포인트에 AI 칩이 탑재됨에 따라, 범용 하드웨어라 하더라도 복잡성을 추상화하고 생산성 달성까지 걸리는 시간을 단축하는 매니지드 서비스로 제공됨으로써 부가가치가 창출됩니다.
지역별 분석
2025년 Wi-Fi 시장에서 북미는 40.55%를 차지했습니다. 이는 650억 달러 규모의 광대역 장려책과 기업의 급속한 기기 교체 주기 덕분입니다. 6GHz 대역 주파수에 조기에 접근함으로써 각 기관은 트라이밴드(Tri-band) 구축의 선구자가 될 수 있으며, 규제 당국의 승인을 아직 기다리고 있는 지역과의 성능 격차를 만들어내고 있습니다. 포춘 500대 기업은 하이브리드 근무에 적합한 스마트 오피스를 구축하기 위해 5년마다 WLAN을 갱신하고 있으며, 이는 세계 평균보다 2년 빠른 속도입니다. 원격 의료 및 원격 교육에는 엔터프라이즈 수준의 신뢰성이 요구되므로, 의료 및 교육 분야는 견조한 성장의 주축이 되고 있습니다.
아시아태평양은 무선 기술을 보완적인 인프라가 아닌 주요 인프라로 자리매김하는 각국의 디지털 전략에 힘입어, 2031년까지 연평균 성장률(CAGR) 15.12%라는 가장 빠른 성장 궤도를 기록하고 있습니다. 중국의 공장 자동화 붐은 국내 칩셋 생산 능력을 육성하는 정책에 힘입어 더욱 가속화되고 있으며, 이는 산업용 등급의 Wi-Fi 6E 기기에 대한 대량 발주로 이어지고 있습니다. 인도의 ‘디지털 인디아(Digital India)’ 구상은 Wi-Fi 메쉬를 통해 60만 개의 마을을 연결하는 것을 목표로 하고 있으며, 무선 통신은 농촌 지역의 디지털 포용을 위한 핵심 요소로 자리 잡고 있습니다. 동남아시아 국가들에서는 관광 거점 및 수출 지향형 제조업 단지 전체에 WLAN이 도입되고 있으며, 정부의 보조금으로 인해 투자 회수 기간이 단축되면서 도입이 가속화되고 있습니다. 자카르타, 방콕, 호치민시에서 진행 중인 스마트 시티 자금 조달 라운드도 해당 지역 수요를 더욱 끌어올리고 있습니다.
유럽의 성장은 계속해서 꾸준한 속도로 진행되고 있으며, 인더스트리 4.0의 보급과 ‘디지털 디케이드’ 이니셔티브에 따라 2030년까지 모든 가구에 기가비트급 연결이 요구되고 있습니다. Wi-Fi는 알프스나 그리스의 섬들처럼 기복이 심한 지형에서 비용 대비 효과가 높은 라스트 마일 솔루션으로 기능하고 있습니다. EU의 ‘디지털 단일 시장’이 주도하는 OpenRoaming 협정은 국경을 초월한 원활한 연결을 실현하여 관광 및 외딴 지역으로의 출장을 뒷받침하고 있습니다. 독일은 산업 분야에서의 도입을 주도하고 있는 반면, 북유럽 국가들은 에너지 효율이 뛰어난 TWT 스케줄링에 의존하는 스마트 그리드 및 지속가능성 관련 이용 사례에 주력하고 있습니다. 중동 및 아프리카에서는 탄화수소에 의존하지 않는 경제 다각화를 도모하고, 사막 지대나 산악 지대 같은 농촌 지역의 디지털 격차를 해소하기 위해 Wi-Fi에 대한 투자가 진행되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the wi-Fi market size was valued at USD 18.48 billion in 2025 and estimated to grow from USD 21.06 billion in 2026 to reach USD 40.44 billion by 2031, at a CAGR of 13.94% during the forecast period (2026-2031).
This report is Segmented by Component (Hardware, Solutions, Services), End-User Vertical (Consumer, Enterprise/Corporate Campuses, Education, Healthcare, Hospitality and Retail, Industrial and Logistics), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Wi-Fi Market Trends and Insights
Proliferation of IoT and smart devices
Enterprises deploy dense sensor networks that often exceed 100 connected endpoints per access point, a profile economically serviced only by Wi-Fi 6E's OFDMA scheduling and multi-user MIMO capabilities. Smart-building operators integrate HVAC, lighting, and surveillance over Wi-Fi mesh to cut structured-cabling costs by 40% and enable predictive maintenance analytics. Demand for sub-10 ms response in edge inference workflows makes Wi-Fi 7's multi-link operation attractive because it sustains jitter-free traffic under load. Industrial automation pilots report 99.9% uptime on dedicated 6 GHz channels versus 97.8% on congested 5 GHz links, validating the migration to new spectrum for mission-critical robotics. These gains encourage organizations to absorb higher capital outlays in return for long-run productivity .
Smart-city initiatives and public Wi-Fi roll-outs
Municipal broadband programs increasingly favor Wi-Fi as the primary medium for digital inclusion because installation is quicker and less capital-intensive than fiber in sprawling rural territories. The Philippines commits USD 1.2 billion to deploy more than 100,000 public hotspots across 17,000 barangays by 2028, a template mirrored by several emerging economies. Europe's Digital Decade targets gigabit coverage by 2030 and positions Wi-Fi 7 mesh as an affordable last-mile alternative in mountainous and island regions. Cities monetize infrastructure by layering sensor backhaul for traffic, air-quality, and emergency-response schemes that self-fund through efficiency gains. Neutral-host deployments that blend Wi-Fi and 5G radios under OpenRoaming agreements generate fresh revenue as roaming fees while delivering seamless citizen connectivity.
Spectrum congestion and interference in unlicensed bands
Dense urban precincts such as Manhattan experience throughput drops near 60% during peak usage, even when Wi-Fi 6E hardware is present, because legacy devices crowd the 2.4 GHz spectrum. Microwave ovens, Bluetooth handsets, and older routers create overlapping noise that adaptive algorithms cannot fully evade. Enterprises increasingly hire spectrum consultants, a service costing USD 50,000-200,000 on expansive campuses, to engineer channel plans that meet service-level objectives. Regulators consider quasi-licensed regimes akin to CBRS so that critical IoT traffic can operate free of consumer interference. Although the 6 GHz allocation temporarily alleviates pressure, forecasts show saturation within five years as IoT endpoints grow exponentially.
Other drivers and restraints analyzed in the detailed report include:
- Rapid adoption of Wi-Fi 6/6E and upcoming Wi-Fi 7
- Hybrid/remote work models demanding high-capacity WLAN
- Heightened data-privacy and security compliance costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, access points contributed 35.92% to the Wi-Fi market share, underlining hardware's continuing relevance even as revenue mix shifts. The services segment, however, is projected to compound at 15.98% through 2031, reflecting the pivot to Network-as-a-Service frameworks that convert upfront capital into recurring operating expense. Cost pressures commoditize standalone routers and range extenders, while cloud-native orchestration platforms take over the policy and analytics roles previously executed by on-premises controllers. Managed service providers leverage artificial intelligence to automate channel allocation, load balancing, and anomaly detection, ultimately delivering 75% fewer unplanned-outage minutes than customer-operated networks. By 2031, the Wi-Fi market size attributed to software and services is expected to eclipse hardware contribution in mature economies as organizations prioritize life-cycle flexibility over asset ownership.
The shift mirrors broader IT procurement trends that favor outcomes over ownership. Consumption-based pricing aligns WLAN costs with occupancy levels, flattening budget spikes and improving CFO visibility. Vendors bundle proactive maintenance, security compliance, and real-time experience scoring to differentiate beyond hardware. Edge gateways and ruggedized IoT bridges constitute a small but fast-rising category, supplying deterministic connectivity in harsh industrial zones where vibration, dust, and temperature extremes invalidate consumer-grade gear. As AI chips embed inside access points, even commodity hardware gains value when offered as a managed experience that abstracts complexity and accelerates time to productivity.
Complete Report Scope:
- By Component
- Hardware
- Access Points
- Routers and Extenders
- Wireless Controllers
- Other Device Types
- Solutions
- Services
- Hardware
- By End-user Vertical
- Consumer
- Enterprise/Corporate Campuses
- Education
- Healthcare
- Hospitality and Retail
- Industrial and Logistics
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia and New Zealand
- Rest of Asia Pacific
- Middle East
- GCC
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America accounts for 40.55% of the Wi-Fi market in 2025, owing to USD 65 billion in broadband incentives and rapid enterprise refresh cycles. Early access to 6 GHz spectrum allows institutions to pioneer tri-band deployments, creating a performance gap over regions still seeking regulatory clearance. Fortune 500 companies refresh their WLAN every five years, two years faster than the global average, to equip smart offices tailored for hybrid work. Healthcare and education pillars represent robust growth nodes as telehealth and distance learning require enterprise-grade reliability.
Asia Pacific records the fastest trajectory with a 15.12% CAGR through 2031, enabled by national digital strategies that treat wireless as primary rather than complementary infrastructure. China's factory-automation boom, amplified by policy to cultivate domestic chipset capability, translates to bulk orders for industrial-grade Wi-Fi 6E equipment. India's Digital India mission envisions connecting 600,000 villages via Wi-Fi mesh, making wireless the linchpin of rural inclusion. Southeast Asian economies integrate WLAN across tourism hubs and export-oriented manufacturing parks, while government subsidies shrink payback periods and accelerate deployments. Smart-city funding rounds across Jakarta, Bangkok, and Ho Chi Minh City further elevate regional demand.
Europe's growth remains orderly as Industry 4.0 uptake and Digital Decade mandates require gigabit household coverage by 2030. Wi-Fi serves as the cost-effective last-mile solution in rugged topographies like the Alps and the Greek islands. OpenRoaming agreements spearheaded by the EU Digital Single Market create frictionless cross-border connectivity, bolstering tourism and remote business travel. Germany leads industrial adoption, whereas Nordic nations focus on smart-grid and sustainability use cases that rely on energy-efficient TWT scheduling. The Middle East and Africa invest in Wi-Fi to diversify economies beyond hydrocarbons and to bridge digital divides in rural deserts and mountainous terrain.
- Cisco Systems, Inc.
- Hewlett Packard Enterprise (Aruba)
- Huawei Technologies Co., Ltd.
- CommScope Holding Company Inc.(Ruckus Networks)
- Juniper Networks Inc.
- Telefonaktiebolaget LM Ericsson
- Extreme Networks, Inc.
- Ubiquiti Inc.
- Fortinet Inc.
- TP-Link Technologies Co., Ltd.
- Netgear Inc.
- D-Link Corporation
- Zyxel Communications Corp.
- Qualcomm Technologies, Inc.
- Broadcom Inc.
- Intel Corporation
- MediaTek Inc.
- Cambium Networks Ltd.
- EnGenius Networks, Inc. (Elitegroup)
- Purple WiFi Ltd.
- Cloud4Wi Inc.
- MetTel Inc.
- Singtel Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of IoT and smart devices
- 4.2.2 Smart-city initiatives and public WiFi roll-outs
- 4.2.3 Rapid adoption of WiFi 6/6E and upcoming WiFi 7
- 4.2.4 Hybrid/remote work models demanding high-capacity WLAN
- 4.2.5 Convergence of WiFi and 5G via OpenRoaming/Passpoint
- 4.2.6 Energy-efficient TWT features for battery-powered IoT nodes
- 4.3 Market Restraints
- 4.3.1 Spectrum congestion and interference in unlicensed bands
- 4.3.2 Heightened data-privacy/security compliance costs
- 4.3.3 Li-Fi and 60 GHz alternatives cannibalizing dense-WiFi use cases
- 4.3.4 Chipset supply constraints delaying WiFi 7 device launches
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.1.1 Access Points
- 5.1.1.2 Routers and Extenders
- 5.1.1.3 Wireless Controllers
- 5.1.1.4 Other Device Types
- 5.1.2 Solutions
- 5.1.3 Services
- 5.1.1 Hardware
- 5.2 By End-user Vertical
- 5.2.1 Consumer
- 5.2.2 Enterprise/Corporate Campuses
- 5.2.3 Education
- 5.2.4 Healthcare
- 5.2.5 Hospitality and Retail
- 5.2.6 Industrial and Logistics
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 South America
- 5.3.2.1 Brazil
- 5.3.2.2 Argentina
- 5.3.2.3 Rest of South America
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Rest of Europe
- 5.3.4 Asia Pacific
- 5.3.4.1 China
- 5.3.4.2 Japan
- 5.3.4.3 South Korea
- 5.3.4.4 India
- 5.3.4.5 Australia and New Zealand
- 5.3.4.6 Rest of Asia Pacific
- 5.3.5 Middle East
- 5.3.5.1 GCC
- 5.3.5.2 Turkey
- 5.3.5.3 Rest of Middle East
- 5.3.6 Africa
- 5.3.6.1 South Africa
- 5.3.6.2 Nigeria
- 5.3.6.3 Rest of Africa
- 5.3.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Cisco Systems, Inc.
- 6.4.2 Hewlett Packard Enterprise (Aruba)
- 6.4.3 Huawei Technologies Co., Ltd.
- 6.4.4 CommScope Holding Company Inc.(Ruckus Networks)
- 6.4.5 Juniper Networks Inc.
- 6.4.6 Telefonaktiebolaget LM Ericsson
- 6.4.7 Extreme Networks, Inc.
- 6.4.8 Ubiquiti Inc.
- 6.4.9 Fortinet Inc.
- 6.4.10 TP-Link Technologies Co., Ltd.
- 6.4.11 Netgear Inc.
- 6.4.12 D-Link Corporation
- 6.4.13 Zyxel Communications Corp.
- 6.4.14 Qualcomm Technologies, Inc.
- 6.4.15 Broadcom Inc.
- 6.4.16 Intel Corporation
- 6.4.17 MediaTek Inc.
- 6.4.18 Cambium Networks Ltd.
- 6.4.19 EnGenius Networks, Inc. (Elitegroup)
- 6.4.20 Purple WiFi Ltd.
- 6.4.21 Cloud4Wi Inc.
- 6.4.22 MetTel Inc.
- 6.4.23 Singtel Group
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


