|
시장보고서
상품코드
2124711
자동차 데이터 수익화 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Automotive Data Monetization - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
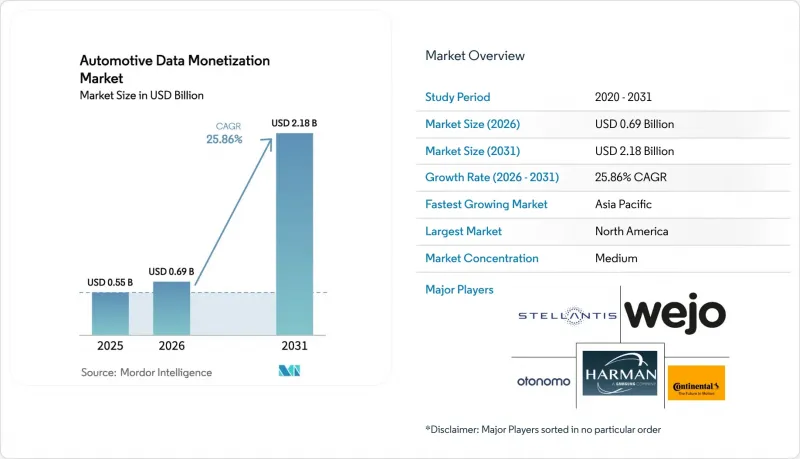
에 의하면, 자동차 데이터 수익화 시장 규모는 2025년에 5억 5,000만 달러로 평가되었습니다. 2026년 6억 9,000만 달러에서 성장하여 2031년까지 21억 8,000만 달러에 이를 것으로 예측됩니다.
예측 기간(2026-2031년) 동안 연평균 성장률(CAGR)은 25.86%를 나타낼 것으로 전망됩니다.
본 보고서는 수익화 모델(직접 데이터 라이선싱, 구독형 데이터 서비스 등), 용도(주행 거리 연동형 보험, 예측 유지보수 등), 최종 사용자(자동차 OEM, Tier 1 공급업체, 보험사 등), 데이터 유형(텔레매틱스 및 차량 상태 데이터 등), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 자동차 데이터 수익화 시장 동향 및 인사이트
커넥티드카 및 V2X 인프라의 보급
2024년형 차량의 절반은 내장형 커넥티비티를 탑재하여 출고되었으며, 그 보급률은 2030년까지 90%에 달할 전망입니다. 양방향 V2X(Vehicle-to-Everything) 통신을 통해 200개 이상의 차량용 센서에서 매일 3-40GB의 데이터가 전송되며, 자동차는 사실상 주행하는 데이터센터로 변모하고 있습니다. 5세대 네트워크는 1밀리초 미만의 지연 시간을 실현하여, 협업형 상황 인식 메시징과 같은 안전상 중요한 활용 사례를 가능하게 할 뿐만 아니라 실시간 분석 서비스도 제공합니다. 데이터 양이 급증하는 가운데, 자동차 데이터 수익화 시장은 트래픽 최적화, 예측 유지보수 구독 서비스, 그리고 이러한 지속적인 데이터 피드에서 가치를 도출하는 위치 기반 서비스의 혜택을 받고 있습니다. 자동차 제조업체와 지자체에서는 이미 운전자에게 실시간 위험 경보를 전송하고, 그 대가로 교통 체증 관리를 위한 익명화된 텔레메트리 데이터를 수집하는 5G 도로변 장비의 시범 운영이 진행되고 있습니다.
주행 거리 및 이용 현황에 따른 보험 프로그램 확대
텔레매틱스를 활용한 보험은 시범 단계에서 주류로 전환되고 있으며, 주요 보험사들은 북미와 유럽 전역에서 운전 스타일에 따른 보험료(Pay-How-You-Drive) 및 주행 거리에 따른 보험료(Pay-As-You-Drive) 상품을 출시하고 있습니다. 속도, 가속도, 코너링, 환경 상황 등을 포괄하는 상세한 지표가 AI 모델에 공급되어 개별 위험 점수가 산출됨에 따라, 보험 인수는 인구통계학적 평균치를 기반으로 하는 방식에서 행동에 기반한 가격 책정으로 전환되고 있습니다. 안전 운전을 하는 운전자는 보험료 할인을 받을 수 있고, 보험사는 보험금 지급 비용을 절감할 수 있으며, 데이터 제공업체는 빈도가 높은 데이터 스트림을 통해 지속적인 수익을 확보할 수 있습니다. OEM을 통해 출고 시에 내장되는 텔레매틱스 모듈은 이러한 보급을 가속화하고, 애프터마켓 기기 비용을 절감하며, 데이터 품질을 보장합니다. 초기 연구에 따르면, 예측 모델을 통해 예방적인 운전자 지도가 이루어질 경우 손해율이 두 자릿수 감소하는 것으로 나타났습니다.
증가하는 사이버 보안 및 개인정보 보호에 대한 우려
현재 자동차는 광범위한 개인정보를 수집하고 안전상 중요한 기능에 대한 잠재적인 관문 역할을 하고 있기 때문에 사이버 공격의 주요 표적이 되고 있습니다. 주목을 받은 정보 유출 사건과 일반 데이터 보호 규정(GDPR(EU 개인정보보호규정)), 캘리포니아주 소비자 개인정보 보호법(CCPA) 등 엄격한 법규로 인해 동의, 암호화 및 데이터 최소화에 관한 까다로운 요구 사항이 부과되고 있습니다. 자동차 제조업체는 보안 부트 체인, 무선(OTA) 패치 관리, 지속적인 위협 모니터링에 투자해야 하며, 이로 인해 운영 비용이 증가하고 새로운 데이터 공유 계약 체결이 지연되고 있습니다. 또한, 개인정보 보호에 대한 우려는 소비자의 동의 의향에도 영향을 미치고 있어, 자동차 데이터 수익화 시장으로의 데이터 공급을 억제하는 한편, 이해관계자들에게 차등 개인정보 보호 및 기기 내 처리와 같은 개인정보 보호형 분석 기술의 도입을 촉구하고 있습니다.
부문별 분석
2025년 자동차 데이터 수익화 시장에서 직접 데이터 라이선싱은 36.78%의 점유율을 차지했으며, 고객 관계와 가격 결정력을 지키고자 하는 OEM에게 여전히 선호되는 방식입니다. 위치 정보, 진단 데이터, 이용 현황 지표 등을 포괄하는 계약 기반 데이터 세트는 보험사, 차량 대여 업체, 분석 벤더에 판매되어 즉각적인 현금 흐름을 창출하고 있습니다. 예측 기간 동안 직접 라이선싱은 절대값 기준으로는 여전히 확대될 것, 수익 분배형 마켓플레이스의 확장에 따라 그 상대적 우위는 점차 낮아질 것입니다. 이러한 플랫폼 사업자들은 여러 브랜드의 익명화된 데이터를 묶어 동의 관리를 수행하고, 기술적 복잡성을 추상화합니다. 그 결과, 수익 분배 모델은 연평균 성장률(CAGR) 26.62%를 나타낼 것으로 예측되며, 이는 모든 카테고리 중 가장 높은 성장률로, 집계되고 표준화되며 규정 준수를 충족하는 데이터 접근에 대한 구매자의 선호도가 높아지고 있음을 반영합니다.
이와 동시에, 구독형 API는 라이브 스트림을 정기적인 수익원으로 활용하여 개발자가 모빌리티 앱, 내비게이션 및 차량 대시보드에 실시간 인사이트를 통합할 수 있도록 지원합니다. 광고 주도형 방식은 아직 초기 단계이지만, 차량 내 인터페이스가 상황에 맞는 컨텐츠를 지원하게 되면 새로운 가치를 창출할 가능성이 있습니다. 개방형 접근을 촉진하는 규제, 특히 유럽연합(EU)의 데이터법은 독점적 관리를 제한함으로써 마켓플레이스형 접근 방식에 호재를 제공합니다. 따라서 자동차 데이터 수익화 업계는 OEM이 프리미엄 데이터 세트를 직접 라이선싱하는 동시에, 더 광범위한 도달 범위를 확보하기 위해 수익 분배형 거래에도 참여하는 하이브리드 전략으로 전환하고 있습니다.
주행 거리 연동형 보험(UBI)은 2025년 수익의 41.64%를 차지하며, 보험사가 행동 기반 인수로 빠르게 전환하고 있음을 반영했습니다. 고빈도 텔레메트리 덕분에 세밀한 위험 세분화가 가능해졌으며, 그 결과 보험금 지급률이 낮아지고 안전 운전에 대한 개별적인 인센티브 제공으로 이어지고 있습니다. 예측 유지보수는 두 번째로 큰 분야로, 차량 상태 신호를 활용하여 예방적으로 정비 일정을 수립함으로써 가동 중단 시간을 최소화하고 있습니다. 스마트 시티 및 인프라 계획은 현재 규모는 작지만, 교통 체증 완화, 배기가스 감축, 대중교통 최적화를 목표로 하는 정부의 이니셔티브에 힘입어 연평균 성장률(CAGR) 27.68%라는 가장 높은 성장률을 보이고 있습니다.
플릿 관리 플랫폼은 경로 계획, 운전자 평가, 연비 분석을 통합하고, 동일한 데이터 스트림을 활용하여 상업 사업자의 운영 비용을 절감합니다. 소프트웨어 정의 차량(SDV)이 위치 정보, 이동 상황, 탑승자의 선호도에 기반하여 개인화된 프로모션을 제공함으로써, 차량 내 상거래 및 광고가 주목을 받고 있습니다. 전동화 추세에 따라 배터리 상태 관리 및 V2G(Vehicle-to-Grid) 서비스가 등장하며, 자동차 데이터 수익화 시장의 수익 구성을 다각화하는 새로운 데이터 세트를 제공합니다.
지역별 분석
2025년에도 북미는 가장 큰 단일 지역이었으며, 텔레매틱스의 보급, 이용 기반 보험의 조기 도입, 그리고 혁신을 촉진하는 데이터 정책에 힘입어 자동차 데이터 수익화 시장 규모는 확대되었습니다. 미시간주와 캘리포니아주에서 진행된 주 차원의 실증 실험에서는 익명화된 차량 텔레메트리 데이터를 기반으로 한 실시간 정체 요금 모델이 검증되었습니다. OEM과 보험사의 협력을 통해 차량 구매 시 동의 획득 체계를 도입함으로써 데이터 활용이 가속화되어, 해당 지역의 리더십이 더욱 공고해졌습니다.
유럽은 2위 자리를 유지했습니다. 곧 시행될 EU 데이터법은 표준화된 API를 의무화하고 B2B 데이터 공유 의무를 정의함으로써, 분절화로 인한 비용을 절감할 가능성이 있는 예측 가능한 프레임워크를 구축하고 있습니다. 독일의 고급 자동차 브랜드는 이 법의 동의 규정에 부합하는 주행 데이터 구독 서비스를 이미 옵션으로 제공합니다. 공공 기관은 집계된 데이터 세트를 활용하여 저공해 구역을 최적화하고 신호등을 동적으로 조정하고 있으며, 이는 일회성 조사 목적의 데이터 접근에서 지속적인 데이터 서비스로의 전환을 시사합니다.
아시아태평양의 급속한 성장은 여러 국가 정책에 기인합니다. 중국 공업정보화부(MIIT)는 커넥티드카 데이터를 현지 서버에 제출할 것을 의무화하고 있으며, 이를 통해 지방 자치 단체가 교통 분석 데이터를 확보할 수 있게 되었습니다. 일본의 Society 5.0 로드맵은 산업 간 데이터 융합을 가속화하여 모빌리티, 에너지, 상거래 데이터 스트림을 시민 중심 플랫폼으로 통합하고 있습니다. 인도에서는 상용 차량에 AIS-140 텔레매틱스 장치의 탑재가 의무화되어 표준화된 데이터의 새로운 공급원이 창출되고 있습니다. 이러한 공급량 증가는 급성장하는 개발자 생태계와 맞물려 자동차 데이터 수익화 시장을 지역 최고 수준의 연평균 성장률(CAGR)로 끌어올리고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the automotive data monetization market size was valued at USD 0.55 billion in 2025 and estimated to grow from USD 0.69 billion in 2026 to reach USD 2.18 billion by 2031, at a CAGR of 25.86% during the forecast period (2026-2031).
This report is Segmented by Monetization Model (Direct Data Licensing, Subscription-Based Data Services, and More), Application (Usage-Based Insurance, Predictive Maintenance, and More), End User (Automotive OEMs, Tier-1 Suppliers, Insurance Companies, and More), Data Type (Telematics and Vehicle Health Data, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Data Monetization Market Trends and Insights
Proliferation of Connected Vehicles and V2X Infrastructure
Half of 2024 model-year vehicles shipped with embedded connectivity and penetration is on track to reach 90% by 2030. Bidirectional vehicle-to-everything links funnel 3-40 GB of data each day from more than 200 onboard sensors, effectively turning the car into a rolling data center. Fifth-generation networks supply sub-millisecond latency that unlocks safety-critical use cases such as cooperative awareness messaging and enables real-time analytics services. As data volumes soar, the automotive data monetization market benefits from traffic optimization, predictive-maintenance subscriptions, and location-based offerings that derive value from these continuous feeds. OEMs and municipalities already pilot 5G road-side units that push real-time hazard alerts to drivers and, in return, harvest anonymized telemetry for congestion management.
Expansion of Usage-Based Insurance Programs
Telematics-driven insurance shifted from pilot stage to mainstream, with major carriers rolling out pay-how-you-drive and pay-as-you-drive products across North America and Europe. Granular metrics covering speed, acceleration, cornering, and environmental context feed AI models that calculate individual risk scores, moving underwriting away from demographic averages toward behavior-based pricing. Safe drivers earn premium discounts, insurers reduce claims costs, and data suppliers secure recurring revenue from high-frequency streams. Embedded telematics modules factory-installed by OEMs accelerate this adoption, eliminating aftermarket device costs and ensuring data quality. Early studies show double-digit declines in loss ratios where predictive models trigger pre-emptive driver coaching.
Heightened Cybersecurity and Privacy Concerns
Vehicles now collect extensive personal information and serve as potential gateways to safety-critical functions, making them prime cyber targets. High-profile breaches and stricter legislation such as the General Data Protection Regulation and the California Consumer Privacy Act impose stringent consent, encryption, and minimization requirements. Automakers must invest in secure boot chains, over-the-air patch management, and continuous threat monitoring, inflating operating costs and slowing new data-sharing agreements. Privacy anxieties also affect consumer willingness to opt-in, curbing data supply to the automotive data monetization market and forcing stakeholders to adopt privacy-preserving analytics such as differential privacy and on-device processing.
Other drivers and restraints analyzed in the detailed report include:
- OEM Shift Toward Software-Defined Vehicles and Subscriptions
- Accelerating Digital Transformation Across the Automotive Value Chain
- Lack of Standardized Data Taxonomy Across OEMs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Direct licensing held a 36.78% share of the automotive data monetization market in 2025 and remains the preferred path for OEMs that wish to safeguard customer relationships and pricing leverage. Contractual datasets covering location, diagnostics, and usage metrics are sold to insurers, fleets, and analytics vendors, yielding immediate cash flows. Over the forecast period, direct licensing still expands in absolute terms, yet its relative dominance erodes as revenue-sharing marketplaces accelerate. These platform operators bundle anonymized feeds from multiple brands, manage consent, and abstract technical complexities. As a result, revenue-sharing models are forecast to post a 26.62% CAGR, the fastest among all categories, reflecting rising buyer preference for aggregated, standardized, and compliant data access.
In parallel, subscription APIs monetize live streams on a recurring basis, enabling developers to embed real-time insights into mobility apps, navigation, and fleet dashboards. Advertising-driven schemes remain nascent but could unlock new value once in-cabin interfaces support contextually relevant content. Regulatory pushes for open access, notably the European Union Data Act, create tailwinds for marketplace approaches by limiting exclusive control. The automotive data monetization industry therefore transitions toward hybrid strategies where OEMs license premium datasets directly while simultaneously participating in shared-revenue exchanges for broader reach.
Usage-based insurance commanded 41.64% of 2025 revenue, reflecting insurers' rapid shift toward behavior-based underwriting. High-frequency telemetry enables fine-grained risk segmentation, which in turn reduces claims ratios and empowers tailored rewards for safer driving. Predictive maintenance followed as the second-largest field, drawing on vehicle-health signals to schedule service proactively and minimize downtime. Smart-city and infrastructure planning, though smaller today, exhibits the strongest growth at 27.68% CAGR, backed by government initiatives to alleviate congestion, curb emissions, and optimize public transport.
Fleet-management platforms integrate routing, driver scoring, and fuel-efficiency analytics, leveraging the same data streams to lower operating costs for commercial operators. In-vehicle commerce and advertising enter the picture as software-defined vehicles deliver personalized promotions based on location, trip context, and occupant preferences. Battery-health and vehicle-to-grid services emerge alongside the electrification trend, providing fresh datasets that diversify the revenue mix inside the automotive data monetization market.
Complete Report Scope:
- Monetization Model
- Direct Data Licensing
- Subscription-Based Data Services
- Revenue-Sharing Marketplaces
- Advertising-Based Models
- Application
- Usage-Based Insurance
- Predictive Maintenance
- Fleet Management and Optimization
- In-Vehicle Advertising and Commerce
- Smart City and Infrastructure Planning
- End User
- Automotive OEMs
- Tier-1 Suppliers
- Insurance Companies
- Fleet Operators and Mobility Providers
- Government and Infrastructure Agencies
- Data Type
- Telematics and Vehicle Health Data
- Infotainment and In-Cabin Interaction Data
- Powertrain and Battery Performance Data
- ADAS and Autonomous Driving Sensor Data
- Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Southeast Asia
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America remained the single largest region in 2025, with the automotive data monetization market size benefiting from widespread telematics installations, early usage-based insurance adoption, and pro-innovation data policies. State-level pilots in Michigan and California demonstrate real-time congestion-pricing models that rely on anonymized vehicle telemetry. OEM-insurer collaborations further entrench the region's leadership by embedding consent mechanisms at vehicle purchase, which expedites data activation.
Europe sustained second position. The forthcoming EU Data Act mandates standardized APIs and defines B2B data-sharing obligations, creating predictable guardrails that may reduce fragmentation costs. German premium brands are already offering optional driving-data subscriptions compliant with the Act's consent provisions. Public agencies tap aggregated datasets to refine low-emission zones and adjust traffic signals dynamically, signaling a shift from one-off research access toward recurring data services.
Asia Pacific's fast growth stems from multiple national policies. China's MIIT requires connected-vehicle data submissions to local servers, enabling city governments to procure traffic analytics. Japan's Society 5.0 roadmap accelerates cross-industry data fusion, integrating mobility, energy, and commerce streams into citizen-centric platforms. India introduces mandatory AIS-140 telematics in commercial fleets, unlocking a new supply of standardized data. The rising supply aligns with a burgeoning developer ecosystem, collectively propelling the automotive data monetization market to its highest regional CAGR.
- Otonomo Technologies Ltd.
- Wejo Group Limited
- Continental AG
- Harman International Industries Inc.
- Stellantis N.V. (Mobilisights)
- Xevo Inc. (Lear Corporation)
- Robert Bosch GmbH
- HERE Global B.V.
- TomTom International B.V.
- Amazon Web Services Inc.
- Microsoft Corporation
- Verizon Communications Inc. (Verizon Connect)
- Databricks, Inc.
- Palantir Technologies
- Vinli Inc.
- Caruso GmbH
- Denso Corporation
- Sibros Technologies Inc.
- Tesla Inc.
- Smartcar Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of Connected Vehicles AND V2X Infrastructure
- 4.2.2 Expansion of Usage-Based Insurance Programs
- 4.2.3 OEM Shift toward Software-Defined Vehicles and Subscriptions
- 4.2.4 Accelerating Digital Transformation across Automotive Value Chain
- 4.2.5 Regulatory Push for Open Data Access and Standardized APIs
- 4.2.6 AI Foundation Models Enabling Synthetic Vehicle Data Products
- 4.3 Market Restraints
- 4.3.1 Heightened Cybersecurity and Privacy Concerns
- 4.3.2 Lack of Standardized Data Taxonomy across OEMs
- 4.3.3 Edge-Computing Shift Limiting Centralized Data Availability
- 4.3.4 Consumer Backlash to In-Cabin Surveillance Data Collection
- 4.4 Industry Ecosystem Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 Monetization Model
- 5.1.1 Direct Data Licensing
- 5.1.2 Subscription-Based Data Services
- 5.1.3 Revenue-Sharing Marketplaces
- 5.1.4 Advertising-Based Models
- 5.2 Application
- 5.2.1 Usage-Based Insurance
- 5.2.2 Predictive Maintenance
- 5.2.3 Fleet Management and Optimization
- 5.2.4 In-Vehicle Advertising and Commerce
- 5.2.5 Smart City and Infrastructure Planning
- 5.3 End User
- 5.3.1 Automotive OEMs
- 5.3.2 Tier-1 Suppliers
- 5.3.3 Insurance Companies
- 5.3.4 Fleet Operators and Mobility Providers
- 5.3.5 Government and Infrastructure Agencies
- 5.4 Data Type
- 5.4.1 Telematics and Vehicle Health Data
- 5.4.2 Infotainment and In-Cabin Interaction Data
- 5.4.3 Powertrain and Battery Performance Data
- 5.4.4 ADAS and Autonomous Driving Sensor Data
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 France
- 5.5.3.3 United Kingdom
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Southeast Asia
- 5.5.4.7 Rest of Asia Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Egypt
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Otonomo Technologies Ltd.
- 6.4.2 Wejo Group Limited
- 6.4.3 Continental AG
- 6.4.4 Harman International Industries Inc.
- 6.4.5 Stellantis N.V. (Mobilisights)
- 6.4.6 Xevo Inc. (Lear Corporation)
- 6.4.7 Robert Bosch GmbH
- 6.4.8 HERE Global B.V.
- 6.4.9 TomTom International B.V.
- 6.4.10 Amazon Web Services Inc.
- 6.4.11 Microsoft Corporation
- 6.4.12 Verizon Communications Inc. (Verizon Connect)
- 6.4.13 Databricks, Inc.
- 6.4.14 Palantir Technologies
- 6.4.15 Vinli Inc.
- 6.4.16 Caruso GmbH
- 6.4.17 Denso Corporation
- 6.4.18 Sibros Technologies Inc.
- 6.4.19 Tesla Inc.
- 6.4.20 Smartcar Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment