|
시장보고서
상품코드
2124715
아세안의 스마트홈 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)ASEAN Smart Homes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 아세안의 스마트홈 시장 규모는 2025년 52억 9,000만 달러에서 2026년에는 61억 1,000만 달러에 이르고, 2026-2031년 CAGR 15.51%로 성장을 지속하여 2031년에는 125억 6,000만 달러에 달할 것으로 예측됩니다.

본 보고서는 제품 유형(스마트 조명, HVAC 및 에너지 관리 기기, 안전 및 보안·접근 제어 등), 통신 프로토콜(Wi-Fi, Zigbee 등), 판매 채널(온라인 소매 및 마켓플레이스, 통신사업자/ISP 번들 등), 설치 유형(기존 주택에 대한 사후 설치, 신축 주택에 대한 통합), 국가별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
아세안(ASEAN) 스마트 홈 시장 동향 및 인사이트
정부 주도의 에너지 절약 인센티브
싱가포르의 ‘기후 친화적 가정 프로그램’에서는 HDB(주택개발청)의 모든 가구에 에너지 절약 가전제품 구매용 400싱가포르달러 상당의 바우처가 지급되고 있으며, 이는 인근 시장이 주목하는 영향력 있는 벤치마크가 되고 있습니다. 태국의 ‘건축물 에너지 코드’와 말레이시아의 ‘국가 반도체 전략’도 유사한 규제를 통해 뒷받침하며, 커넥티드 HVAC 및 에너지 관리 기기 수요를 높이고 있습니다. 여러 국가의 전력 회사는 시간대별 요금제의 시범 운영을 시작하여, 스마트 온도 조절기나 부하 제어 장치를 도입한 가정에 인센티브를 제공합니다. 싱가포르 푼골 노스쇼어 주택단지에 도입된 가정용 에너지 관리 시스템의 통합 사례는 이를 인프라에 통합함으로써 투자 회수 기간이 단축되고 사용자의 신뢰도가 높아진다는 점을 보여줍니다. 이러한 조치들이 결합되면서 스마트 에너지 기기는 ‘있으면 편리한 것’에서 ‘표준 사양’으로 전환되고 있으며, 이는 중기적인 아세안 스마트 홈 시장 전망을 밝게 하고 있습니다.
도시 중산층의 가처분 소득 증가
아세안에서 확대되고 있는 도시 중산층은 기본적인 가전제품에서 기능이 풍부하고 네트워크로 연결된 제품으로의 전환을 주도하고 있습니다. 베트남의 가전제품 지출은 연간 10% 이상의 성장률을 유지하며, 2025년까지 130억 달러에 달할 전망입니다. 인도네시아의 개발사들은 현재 스마트 홈을 ‘프리미엄’이 아닌 ‘표준’으로 포지셔닝하고 있으며, 네트워크로 연결된 생활이 현대 주택의 일부라는 소비자의 인식을 강화하고 있습니다. 6,000제곱미터 규모의 IoT 공장을 운영하며 7만 명의 고객에게 서비스를 제공하는 베트남의 Lumi와 같은 지역 기업들은 현지 맞춤형 디자인, 언어 지원, 기후에 적합한 하드웨어가 다국적 브랜드에 대항할 수 있는 견고한 틈새 시장을 어떻게 창출하고 있는지 보여주고 있습니다. 이처럼 가처분 소득 증가는 여러 기기의 구매나 구독 서비스 업그레이드를 가능하게 하여, 공급업체 입장에서 고객의 평생 가치를 높이고 있습니다.
높은 초기 기기 및 설치 비용
부품 가격의 급등과 관세 압박으로 인해, 가격에 민감한 아세안 소비자들이 자발적인 업그레이드를 고려하고 있는 바로 그 시점에 BOM(부품 원가)이 상승하고 있습니다. 관세 부담을 줄이기 위해 말레이시아나 베트남으로 생산을 다각화하는 제조업체는 단기적인 설비 투자를 할 수밖에 없으며, 이는 최종 사용자의 가격 상승으로 이어져 엔트리 레벨 부문의 보급을 둔화시킬 가능성이 있습니다. 정부의 일괄 구매에 대한 보조금은 가격 급등으로 인한 충격을 부분적으로 상쇄하고 있지만, 많은 가정은 여전히 풀세트 도입이 아닌 단일 기기로부터 도입을 시작하는 경향을 보이고 있습니다. 벤더 측은 기능을 축소한 SKU로 대응하고 있지만, 이러한 기능 축소는 정기적인 수익 모델의 기반이 되는 원활한 사용자 경험을 저해할 수 있어 단기적인 보급을 둔화시키고 있습니다.
부문 분석
2025년, 아세안(ASEAN) 스마트 홈 시장에서 안전 및 보안 및 접근 제어 기기가 31.45%를 차지했습니다. 이는 도시 지역의 밀집된 주거 환경과 개인의 안전에 대한 소비자의 관심이 높아지고 있음을 반영합니다. 도어락, 카메라, 센서는 구조적인 변경 없이 설치할 수 있기 때문에 이 부문에서는 리모델링 수요가 견조합니다. HVAC(난방·환기·공조) 및 에너지 관리 기기는 가장 빠른 성장세를 보이고 있으며, 전력 회사가 변동 요금제를 도입하고 정부가 가전제품 보조금 제도를 에너지 스타 등급과 연계함에 따라 연평균 성장률(CAGR) 16.78%로 확대되고 있습니다. 스마트 조명은 여전히 확고한 게이트웨이 카테고리이며, Philips 휴(Philips Hue)의 AI 강화 제품은 분위기 조성, 보안, 자동화의 융합이 진행되고 있음을 보여줍니다. 엔터테인먼트 허브는 스마트폰 기반 제어 패널로부터의 대체 압력에 직면하고 있지만, 지연에 민감한 스트리밍의 경우 멀티룸 환경에서도 여전히 전용 브리지가 선호되고 있습니다. 스마트 수도꼭지나 누수 감지기 같은 신흥 틈새 시장은 물 부족으로 어려움을 겪는 시장에서 회복력 강화에 기여하고 있습니다.
Philips 휴(Philips Hue)의 생성형 AI 어시스턴트는 기존 조명 브랜드가 주택 전체의 보안 분야로 사업을 확장하고 있는 좋은 예이며, 한편,투야의 AI 탑재 반려동물 자동 급식기는 카테고리 경계가 모호해지고 있음을 여실히 보여주고 있으며, 이것이 아세안(ASEAN)의 스마트 홈 시장을 활기차게 유지하고 있습니다. 경쟁의 치열함은 제품마다 차이가 있습니다. 모션 센서와 같은 성숙한 기기는 상품화가 진행되고 있지만, AI 탑재 카메라나 에너지 최적화형 HVAC 제어 장치는 여전히 프리미엄 가격을 유지하고 있습니다. 클라우드 분석에 대한 사용자의 신뢰가 높아짐에 따라, 소프트웨어 대시보드를 하드웨어와 번들로 제공하는 벤더들은 더 높은 고객 유지율과 지속적인 서비스 수익을 실현하고 있습니다.
2025년에는 Wi-Fi가 연결 기기의 38.55%를 차지할 것으로 예상되며, 이는 라우터의 보급과 사용자의 간편한 설치 편의성 덕분입니다. 그러나 전력 소비 문제와 2.4GHz 대역의 혼잡으로 인해 Thread의 저전력 메시 네트워크가 연평균 성장률(CAGR) 16.55%로 성장할 여지가 생기고 있습니다. Zigbee는 비용 중심의 멀티 센서 도입, 특히 조명 분야에서 여전히 일정한 입지를 유지하고 있습니다. Bluetooth Low Energy는 문 열기 등의 근접형 기능을 지원하지만, 주택 전체의 관리를 담당하는 경우는 거의 없습니다. 장거리 보안 주변기기에서는 독자적인 서브GHz 프로토콜이 여전히 존재하지만, 멀티 프로토콜 칩이 주류가 됨에 따라 점유율을 잃고 있습니다. 구글과 미디어텍이 선보인 Thread 네이티브 칩셋은 실리콘 생태계가 표준화된 스택으로 전환되고 있음을 보여주며, 개발 오버헤드를 줄이고 벤더 간 상호 운용성을 높이고 있습니다. Silicon Labs의 네이티브 Matter-over-Thread 지원 스마트 잠금장치 지원은 높은 수준의 보안이 요구되는 이용 사례에서 해당 프로토콜의 실용성을 더욱 입증하고 있습니다. 칩셋 가격이 하락함에 따라 아세안(ASEAN) 지역의 제조업체들은 듀얼 밴드 Wi-Fi/Thread 무선 기능을 통합하여 최종 사용자에게 미래를 대비한 유연성을 제공합니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 동향
LSHAccording to Mordor Intelligence, the ASEAN smart homes market size is expected to grow from USD 5.29 billion in 2025 to USD 6.11 billion in 2026 and is forecast to reach USD 12.56 billion by 2031 at 15.51% CAGR over 2026-2031.
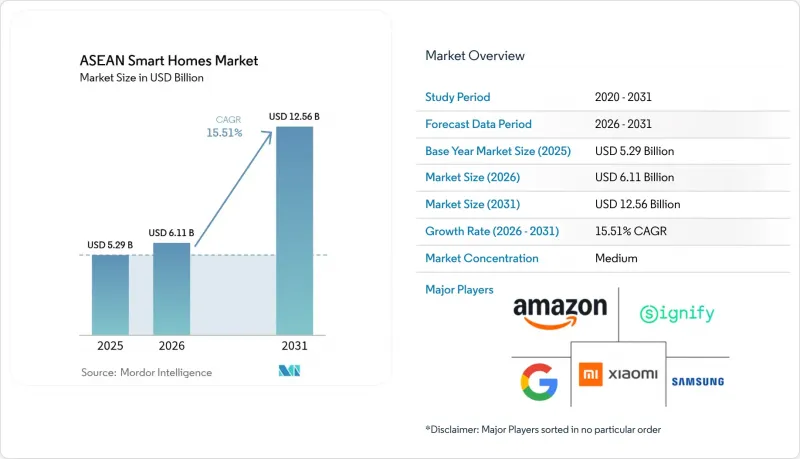
This report is Segmented by Product Type (Smart Lighting, HVAC and Energy-Management Devices, Safety, Security and Access Control, and More), Communication Protocol (Wi-Fi, Zigbee, and More), Sales Channel (Online Retail and Marketplaces, Telco/ISP Bundles, and More), Installation Type (Retrofit and New-Build Integrated), and Country. The Market Forecasts are Provided in Terms of Value (USD).
ASEAN Smart Homes Market Trends and Insights
Government-backed Energy-efficiency Incentives
Singapore's Climate-Friendly Households Programme gives every HDB household SGD 400 vouchers for energy-efficient appliances and sets an influential benchmark that neighboring markets monitor closely. Thailand's Building Energy Code and Malaysia's National Semiconductor Strategy provide similar regulatory nudges that elevate demand for connected HVAC and energy-management devices. Utilities in multiple countries have begun piloting time-of-use tariffs, rewarding homes equipped with smart thermostats and load controllers. Integration of Home Energy Management Systems into Singapore's Punggol Northshore estates demonstrates how bake-in infrastructure shortens payback periods and boosts user confidence. Collectively, these measures move smart energy devices from nice-to-have to default specifications, lifting the ASEAN smart homes market outlook for the medium term.
Rising Urban Middle-class Disposable Income
ASEAN's expanding urban middle class drives a shift from basic appliances to feature-rich, connected products. Vietnam's home-appliance spend is on course to touch USD 13 billion by 2025, growing over 10% annually. Indonesian developers now position smart homes as standard rather than premium, reinforcing consumer perception that connected living is part of modern housing. Regional firms such as Vietnam's Lumi, which operates a 6,000 m2 IoT factory and serves 70,000 customers, illustrate how localized design, language support, and climate-appropriate hardware create defensible niches against multinational brands. Rising disposable income thus unlocks multi-device purchases and subscription upgrades, increasing lifetime customer value for vendors.
High Upfront Device and Install Cost
Component inflation and tariff pressures have lifted BOM costs just as price-sensitive ASEAN consumers weigh discretionary upgrades. Manufacturers diversifying production into Malaysia and Vietnam to reduce duty exposure incur short-term capex that can raise end-user prices, slowing adoption in entry-level segments. Bulk-purchase government subsidies partially offset sticker shock, yet many households still start with single devices rather than full-suite installs. Vendors respond with stripped-down SKUs, but these pared features sometimes dilute the seamless experience that anchors recurring revenue models, tempering near-term uptake.
Other drivers and restraints analyzed in the detailed report include:
- Smartphone and Broadband Penetration Surge
- Matter Protocol Enabling Cross-brand IoT
- Ecosystem Fragmentation and Legacy Protocol Lock-in
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Safety, security, and access control devices accounted for 31.45% of the ASEAN smart homes market in 2025, reflecting dense urban living and rising consumer focus on personal safety. The segment enjoys strong retrofit demand, as door locks, cameras, and sensors can be installed without structural changes. HVAC and energy-management devices register the quickest pulse, expanding at 16.78% CAGR as utilities launch variable tariffs and governments tie appliance rebates to energy-star ratings. Smart lighting remains an established gateway category; Philips Hue's AI-enhanced offerings illustrate growing convergence between ambiance, security, and automation. Entertainment hubs face substitution pressure from smartphone-based control panels, yet multi-room setups still favor dedicated bridges for latency-sensitive streaming. Emerging niches such as smart water valves and leak detectors address resilience in water-stressed markets.
Philips Hue's generative-AI assistant exemplifies how legacy lighting brands extend into whole-home security, while Tuya's AI-enabled pet-health feeders highlight category blurring that keeps the ASEAN smart homes market vibrant. Competitive intensity varies: mature devices like motion sensors are commoditizing, but AI-enabled cameras and energy-optimizing HVAC controls sustain premium pricing. As user trust in cloud analytics rises, vendors that bundle software dashboards with hardware achieve higher stickiness and recurring service revenue.
Wi-Fi underpins 38.55% of connected devices in 2025, benefiting from ubiquitous router presence and straightforward user onboarding. Power consumption and congested 2.4 GHz bands, however, open space for Thread's low-energy mesh to grow at 16.55% CAGR. Zigbee maintains a foothold in cost-sensitive, multi-sensor deployments, especially for lighting. Bluetooth Low Energy powers proximity-based functions such as door unlocks, but rarely manages entire homes. Proprietary sub-GHz protocols persist in long-range security peripherals yet lose share as multi-protocol chips become mainstream. Google-MediaTek's Thread-native chipset signals the silicon ecosystem's pivot toward standardized stacks, reducing development overhead and boosting cross-vendor interoperability. Silicon Labs' support for native Matter-over-Thread smart locks further validates the protocol's viability in high-security use cases. As chipset prices fall, ASEAN manufacturers integrate dual-band Wi-Fi/Thread radios, granting end users future-proof flexibility.
Complete Report Scope:
- By Product Type
- Smart Lighting
- HVAC and Energy-Management Devices
- Safety, Security and Access Control
- Smart Appliances
- Entertainment and Connectivity Hubs
- Water and Utility-Management Devices
- By Communication Protocol
- Wi-Fi
- Zigbee
- Bluetooth/BLE
- Z-Wave
- Thread and Matter
- Proprietary/Others
- By Sales Channel
- Online Retail and Marketplaces
- Telco/ISP Bundles
- Home-Improvement and Electronics Stores
- Value-added Service Integrators
- By Installation Type
- Retrofit
- New-Build Integrated
- By Country
- Indonesia
- Thailand
- Malaysia
- Vietnam
- Singapore
- Philippines
- Others
List of Companies Covered in this Report:
- Amazon.com Inc. (Ring/Echo)
- Google LLC (Nest)
- Samsung Electronics Co. Ltd (SmartThings)
- Xiaomi Corp. (Aqara)
- Signify N.V. (Philips Hue)
- Schneider Electric SE (Wiser)
- Honeywell International Inc. (Resideo)
- Arlo Technologies Inc.
- Ecobee Inc.
- TP-Link Technologies Co. Ltd (Tapo/Kasa)
- Anker Innovations (Eufy)
- Wyze Labs Inc.
- Nanoleaf Canada Ltd.
- Belkin International Inc. (Wemo)
- Lifx Lighting (Feit Electric)
- Eve Systems GmbH
- Yale Home (ASSA ABLOY)
- SimpliSafe Inc.
- August Home Inc.
- SwitchBot Co. Ltd.
- Sengled Optoelectronics Co. Ltd.
- Fibaro (Nice S.p.A.)
- Tuya Smart Co. Ltd.
- Aqara (Lumi United)
- DoorBird (Bird Home Automation GmbH)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government?backed energy-efficiency incentives
- 4.2.2 Rising urban middle-class disposable income
- 4.2.3 Smartphone and broadband penetration surge
- 4.2.4 Security and safety concerns in dense cities
- 4.2.5 Matter protocol enabling cross-brand IoT
- 4.2.6 Telco-bundled IoT subscription models
- 4.3 Market Restraints
- 4.3.1 High upfront device and install cost
- 4.3.2 Ecosystem fragmentation and legacy protocol lock-in
- 4.3.3 Data-localisation compliance costs
- 4.3.4 Limited certified installer base beyond tier-1 cities
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Pricing Analysis
- 4.9 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Product Type
- 5.1.1 Smart Lighting
- 5.1.2 HVAC and Energy-Management Devices
- 5.1.3 Safety, Security and Access Control
- 5.1.4 Smart Appliances
- 5.1.5 Entertainment and Connectivity Hubs
- 5.1.6 Water and Utility-Management Devices
- 5.2 By Communication Protocol
- 5.2.1 Wi-Fi
- 5.2.2 Zigbee
- 5.2.3 Bluetooth/BLE
- 5.2.4 Z-Wave
- 5.2.5 Thread and Matter
- 5.2.6 Proprietary/Others
- 5.3 By Sales Channel
- 5.3.1 Online Retail and Marketplaces
- 5.3.2 Telco/ISP Bundles
- 5.3.3 Home-Improvement and Electronics Stores
- 5.3.4 Value-added Service Integrators
- 5.4 By Installation Type
- 5.4.1 Retrofit
- 5.4.2 New-Build Integrated
- 5.5 By Country
- 5.5.1 Indonesia
- 5.5.2 Thailand
- 5.5.3 Malaysia
- 5.5.4 Vietnam
- 5.5.5 Singapore
- 5.5.6 Philippines
- 5.5.7 Others
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amazon.com Inc. (Ring/Echo)
- 6.4.2 Google LLC (Nest)
- 6.4.3 Samsung Electronics Co. Ltd (SmartThings)
- 6.4.4 Xiaomi Corp. (Aqara)
- 6.4.5 Signify N.V. (Philips Hue)
- 6.4.6 Schneider Electric SE (Wiser)
- 6.4.7 Honeywell International Inc. (Resideo)
- 6.4.8 Arlo Technologies Inc.
- 6.4.9 Ecobee Inc.
- 6.4.10 TP-Link Technologies Co. Ltd (Tapo/Kasa)
- 6.4.11 Anker Innovations (Eufy)
- 6.4.12 Wyze Labs Inc.
- 6.4.13 Nanoleaf Canada Ltd.
- 6.4.14 Belkin International Inc. (Wemo)
- 6.4.15 Lifx Lighting (Feit Electric)
- 6.4.16 Eve Systems GmbH
- 6.4.17 Yale Home (ASSA ABLOY)
- 6.4.18 SimpliSafe Inc.
- 6.4.19 August Home Inc.
- 6.4.20 SwitchBot Co. Ltd.
- 6.4.21 Sengled Optoelectronics Co. Ltd.
- 6.4.22 Fibaro (Nice S.p.A.)
- 6.4.23 Tuya Smart Co. Ltd.
- 6.4.24 Aqara (Lumi United)
- 6.4.25 DoorBird (Bird Home Automation GmbH)
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-Space and Unmet-Need Assessment