

|
시장보고서
상품코드
2124718
태국의 IT 및 보안 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Thailand IT And Security - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
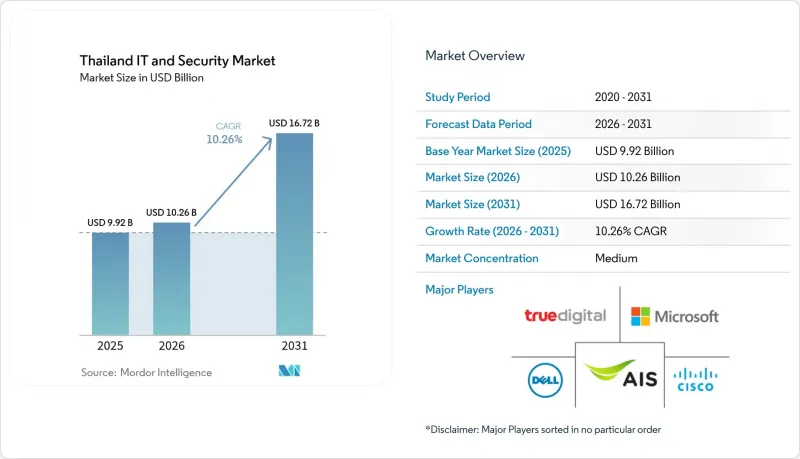
에 의하면, 태국의 IT 및 보안 시장 규모는 2025년에 99억 2,000만 달러로 평가되었습니다. 2026년 102억 6,000만 달러에서 2031년까지 167억 2,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 10.26%를 나타낼 전망입니다.
본 보고서는 구성 요소(하드웨어 및 디바이스, 소프트웨어, 서비스), 도입 형태(On-Premise, 클라우드, 하이브리드), 조직 규모(대기업, 중소기업), 최종 사용자 산업(은행, 금융서비스 및 보험(BFSI), 정부·국방, 제조, 의료, 소매 및 전자상거래 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
태국의 IT 및 보안 시장 동향 및 인사이트
태국 공공 부문의 클라우드 퍼스트 정책
디지털 정부 개발청은 2027년까지 공공 부문의 신규 워크로드 70%를 클라우드 인프라로 이전할 것을 의무화하고 있으며, 412개 기관에 대해 2026년 12월까지 최소 1개의 미션 크리티컬 시스템을 이전할 것을 요구하고 있습니다. 2025년에 National Telecom과 체결된 계약은 이미 18개 부처에 걸쳐 있으며, ISO/IEC 27001 인증을 획득한 인프라가 포함되어 있어 클라우드 보안 태세 관리 및 특권 액세스 제어에 대한 지출이 증가하고 있습니다. 공공 부문에서 이러한 툴셋의 구매액이 연평균 41%의 성장률을 보이고 있다는 사실은 정책 지침이 어떻게 구체적인 수요로 이어지고 있는지를 여실히 보여줍니다. 그러나 9개월에 달하는 입찰 주기와 레거시 On-Premise 자산과의 공존으로 인해 하이브리드 환경 전반에 걸친 통합적인 모니터링이 필요해지면서 복잡성이 증가하는 한편, 관리형 보안 운영 센터(MSOC)의 도입이 촉진되고 있습니다. 또한, 이 지침에 명시된 다단계 인증 및 5년간의 감사 로그 보관과 같은 요건은 Identity-as-a-Service(IaaS) 및 불변 스토리지에 대한 수요를 더욱 확고히 하고 있습니다.
5G 구축 가속화로 엣지부터 클라우드까지의 활용 사례 가능
True Corporation과 Advanced Info Service는 2024년 말에 네트워크 통합을 완료했으며, 그 결과 2025년 중반까지 인구의 92%를 커버하는 5G 독립형 네트워크가 구축되었습니다. 촌부리와 라용의 산업단지에서는 지연 시간이 10밀리초 미만으로 줄어들어 머신 비전을 활용한 품질 관리, 무인 운반차(AGV), 원격 수술의 시범 운영이 가능해졌습니다. 이러한 이용 사례에는 엣지 방화벽, 마이크로 세분화, 클라우드 기반 위협 분석과의 암호화된 텔레메트리 동기화가 필요하며, 이 세 가지가 합쳐서 2025년 엣지 보안 예산 증가분의 62%를 차지했습니다. 네트워크 슬라이싱은 새로운 인증 과제를 야기하고 있습니다. 네트워크 기능 가상화(NFV) 보안을 도입한 기업은 19%에 불과하여, 이는 미개척 서비스 기회가 존재함을 시사합니다. 2024년에 완료된 2G/3G 서비스 종료는 산업용 컨트롤러의 업그레이드를 가속화했으며, 공장들이 새로운 무선 게이트웨이의 보안을 서둘러 확보함에 따라 태국의 IT 및 보안 시장을 확대시켰습니다.
3만 명의 사이버 보안 전문가 부족
국가 사이버 보안청의 추산에 따르면, 2027년까지 3만 명의 인력 부족이 발생할 것으로 예상되지만, 태국의 CISSP 취득자 수는 2024년부터 2025년에 걸쳐 고작 385명에서 431명으로 증가하는 데 그쳤습니다. 방콕의 보안 운영 센터(SOC) 분석가 연봉 중앙값은 월 18% 증가한 6만 5,000바트(1,850달러)로 급등했으며, 이로 인해 중소기업들은 자체적으로 관리 및 평가를 수행하기 어려운 상황에서 매니지드 서비스 이용을 선택할 수밖에 없게 되었습니다. 2025년에는 아웃소싱이 22% 증가했으나, 제3자에 의한 사고 대응에 대한 의존은 조직 내 노하우를 약화시키고, 피해 확산을 막는 데 걸리는 시간을 길게 만들고 있습니다. 전문가를 확보하기 어려워 제로 트러스트 네트워크 액세스 도입이 지연되고 있으며(2025년 말 기준 도입한 조직은 고작 11%에 불과), 보안 오케스트레이션, 자동화 및 대응의 보급도 더딘 실정입니다. 정부의 장학금 프로그램과 벤더가 운영하는 아카데미는 확대되고 있지만, 고급 인증 자격 취득이 지연되고 있어 태국의 IT 및 보안 시장 성장세는 계속해서 제약을 받을 것으로 전망됩니다.
부문별 분석
서비스 부문은 가장 빠른 성장세를 보이고 있으며, 기업들이 취약점 평가, 침투 테스트 및 관리형 감지 및 대응(MDR)을 현지 전문가에게 위탁함에 따라 2031년까지 연평균 성장률(CAGR) 10.71%로 성장할 전망입니다. 태국의 IT 및 보안 시장의 전문 서비스 시장 규모는 국가 사이버 보안청의 분기별 감사 의무화에 따라 2025년에 21억 바트(6,000만 달러)에 달했습니다. 대조적으로, 소프트웨어 분야는 운영 비용(OPEX) 예산에 부합하는 구독형 엔드포인트 보호 및 클라우드 보안 태세 관리 플랫폼 덕분에 41.72%라는 최대 점유율을 유지했습니다. 반면, 하드웨어 분야의 지출은 방화벽 납기 기간이 14주에 달하고 바트화 약세로 인해 수입 장비 비용이 상승함에 따라 둔화되었습니다.
서비스 분야의 성장은 규제의 복잡화도 반영하고 있습니다. 정부 입찰에서는 ISO/IEC 27001 인증이 요구되고 있으며, 이로 인해 각 기관은 사내에 부족한 제3자 감사인이나 정책 설계자를 기용할 수밖에 없게 되었습니다. 특히 클라우드 워크로드를 위한 관리형 감지 및 대응(MDR)은 보안 운영 센터(SOC)를 보유하지 않은 중소기업들이 성장에 따른 과금 계약을 요구하는 추세에 힘입어 2025년에 28% 확대되었습니다. 이러한 동향은 태국의 IT 및 보안 시장에서 단순한 기술 재판매에서 전문 지식 주도형 서비스로 전환되는 구조적 변화를 뒷받침하고 있습니다.
2025년 지출 중 클라우드가 55.84%를 차지했지만, 하이브리드 환경은 연평균 성장률(CAGR) 10.44%를 나타낼 것으로 예측됩니다. 카시콘 은행 등 금융 기관들은 고객 데이터베이스를 On-Premise에 유지하면서 부정 감지 모델을 Google Cloud로 이전하고 있으며, 이는 보안 터널링, ID 페더레이션 및 통합 로그 관리가 필수적인 이유를 보여줍니다. 클라우드 우선 정책 하에서 기존 데이터센터와의 연계를 유지하면서 멀티 클라우드 전략을 채택하는 기관이 증가함에 따라, 태국의 IT 및 보안 시장에서 클라우드 워크로드 보호 플랫폼의 점유율이 확대되었습니다.
그럼에도 불구하고 국방, 공공 서비스, 의료 분야에서는 On-Premise 환경이 여전히 뿌리 깊게 남아 있으며, 주권 및 지연 시간 문제로 인해 워크로드는 프라이빗 클러스터에 배치되고 있습니다. 하이브리드 환경의 복잡성으로 인해 기업의 62%가 정책 일관성 문제를 겪고 있으며, 이는 쿠버네티스 클러스터와 하드웨어 기반 방화벽에 걸친 클라우드 보안 태세 관리에 대한 수요를 촉진하고 있습니다. 국가사이버보안청(NCS)의 2025년 1월 기준을 준수하는 Identity-as-a-Service(IaaS) 플랫폼은 이러한 사일로를 해소하고 있으며, 하이브리드 환경이 태국의 IT 및 보안 시장에서 일시적인 현상이 아닌 지속 가능한 운영 모델임을 부각시키고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the Thailand IT and Security market size was valued at USD 9.92 billion in 2025 and is estimated to grow from USD 10.26 billion in 2026 to reach USD 16.72 billion by 2031, at a CAGR of 10.26% during the forecast period (2026-2031).
This report is Segmented by Component (Hardware and Devices, Software, and Services), Deployment Mode (On-Premises, Cloud, and Hybrid), Organization Size (Large Enterprises, and Small and Medium Enterprises), End-User Industry (BFSI, Government and Defense, Manufacturing, Healthcare, Retail and E-Commerce, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Thailand IT And Security Market Trends and Insights
Cloud-First Policy in Thai Public Sector
The Digital Government Development Agency mandated that 70% of new public-sector workloads move to cloud infrastructure by 2027, compelling 412 agencies to migrate at least one mission-critical system before December 2026. Contracts signed with National Telecom in 2025 already span 18 ministries and include ISO/IEC 27001-certified infrastructure, elevating spend on cloud security posture management and privileged access controls. Annual growth of 41% in public-sector purchases of these toolsets underscores how policy edicts translate into addressable demand. Yet nine-month tender cycles and coexistence with legacy on-premises assets require integrated monitoring across hybrid environments, increasing complexity and fueling uptake of managed security operations centers. The directive's multi-factor authentication and five-year audit-log stipulations further lock in demand for identity-as-a-service and immutable storage.
Acceleration of 5G Rollout Enabling Edge-to-Cloud Use Cases
True Corporation and Advanced Info Service finished network consolidation in late 2024, resulting in a 5G standalone footprint that covered 92% of the population by mid-2025. Latency dropped below 10 milliseconds for industrial estates in Chonburi and Rayong, enabling machine-vision quality control, autonomous guided vehicles, and remote surgery pilots. These use cases require edge firewalls, micro-segmentation, and encrypted telemetry sync with cloud-based threat analytics, which together accounted for 62% of incremental edge-security budgets in 2025. Network slicing introduces fresh authentication challenges; only 19% of enterprises have deployed network-function-virtualization security, pointing to an untapped services opportunity. The 2G/3G shutdown completed in 2024 accelerated industrial controller upgrades, widening the Thailand IT and Security market as factories rushed to secure new radio gateways.
Shortage of 30,000 Cyber-Security Professionals
The National Cyber Security Agency calculated a 30,000-person talent gap through 2027, while Thailand's CISSP cohort rose only from 385 to 431 between 2024 and 2025. Median security-operations-center analyst pay in Bangkok jumped 18% to THB 65,000 (USD 1,850) per month, pushing small and medium enterprises toward managed services they often struggle to manage and assess. Outsourcing grew 22% in 2025, but reliance on third-party incident response dilutes institutional knowledge and extends containment times. Limited specialist availability slows adoption of zero-trust network access-implemented by just 11% of organizations as of end-2025-and drags on uptake of security orchestration, automation, and response. Government scholarship programs and vendor-run academies are scaling, yet the lag in advanced certifications will continue to temper the Thailand IT and Security market's growth trajectory.
Other drivers and restraints analyzed in the detailed report include:
- E-Commerce Boom Driving Hyperscale Data-Center Build-Outs
- Rise of Thailand PLUS Near-Shoring by Japanese and U.S. Manufacturers
- Fragmented SME IT Budget Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services generated the fastest momentum, poised to rise at 10.71% CAGR to 2031 as enterprises outsource vulnerability assessments, penetration tests, and managed detection and response to local specialists. The Thailand IT and Security market size for professional services reached THB 2.1 billion (USD 60 million) in 2025 following the National Cyber Security Agency's quarterly audit mandate. In contrast, software maintained the largest slice at 41.72% thanks to subscription-based endpoint protection and cloud-security posture management platforms that match operating-expense budgets. Hardware spent softened amid 14-week firewall lead times and Baht depreciation that inflated imported appliance costs.
Growth in services also mirrors regulatory intricacy. Government tenders require ISO/IEC 27001 certification, pushing agencies to engage third-party auditors and policy architects they lack in-house. Managed detection and response, especially for cloud workloads, expanded 28% in 2025 as small and medium enterprises lacking security-operations centers sought pay-as-they-grow contracts. This dynamic reinforces a structural shift in the Thailand IT and Security market toward expertise-driven offerings over pure technology resale.
Hybrid environments are projected to grow at a 10.44% CAGR, even though cloud held 55.84% of 2025 spending. Banks such as Kasikornbank moved fraud-detection models to Google Cloud while retaining customer databases on-premises, illustrating why secure tunneling, identity federation, and unified logging are indispensable. The Thailand IT and Security market share for cloud workload protection platforms widened as agencies under the Cloud First Policy adopted multicloud strategies that still tether to existing data centers.
Nevertheless, on-premises estates persist in defense, utilities, and healthcare, where sovereignty and latency push workloads to private clusters. Hybrid complexity has 62% of enterprises reporting policy-consistency challenges, fuelling demand for cloud-security posture management that spans Kubernetes clusters and hardware-based firewalls. Identity-as-a-service platforms compliant with the National Cyber Security Agency's January 2025 standards are bridging these silos, underscoring how hybrid is not a transitional but a durable operating model within the Thailand IT and Security market.
Complete Report Scope:
- By Component
- Hardware and Devices
- Software
- Services
- By Deployment Mode
- On-premises
- Cloud
- Hybrid
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By End-user Industry
- BFSI
- Government and Defense
- Manufacturing
- Healthcare
- Retail and E-commerce
- Energy and Utilities
- Other End-User Industries
List of Companies Covered in this Report:
- Advanced Info Service Public Co. Ltd. (AIS)
- True Digital Group Co. Ltd.
- Dell Technologies Inc.
- Cisco Systems Inc.
- International Business Machines Corp. (IBM)
- Microsoft Corporation
- Hewlett Packard Enterprise Co.
- Fujitsu (Thailand) Co. Ltd.
- Fortinet Inc.
- Palo Alto Networks Inc.
- Check Point Software Technologies Ltd.
- Trend Micro Inc.
- Kaspersky Lab
- Samsung Electronics Co. Ltd.
- Acer Inc.
- Lenovo Group Ltd.
- G-Able Co. Ltd.
- MFEC Public Co. Ltd.
- Digital Government Development Agency (DGA)
- SIAMDATA Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud-first policy in Thai public sector
- 4.2.2 Acceleration of 5G rollout enabling edge-to-cloud use-cases
- 4.2.3 E-commerce boom driving hyperscale data-center build-outs
- 4.2.4 Board-level adoption of NIST CSF and ISO/IEC 27001 to meet export-market mandates
- 4.2.5 Rise of "Thailand PLUS" near-shoring by Japanese and US manufacturers
- 4.2.6 FinTech regulatory sandbox pushing open-API security spend
- 4.3 Market Restraints
- 4.3.1 Fragmented SME IT budget cycles
- 4.3.2 Shortage of 30 000 cyber-security professionals
- 4.3.3 Legacy MPLS contracts delaying cloud migration
- 4.3.4 High dependence on imported semiconductors amid Baht volatility
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware and Devices
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Deployment Mode
- 5.2.1 On-premises
- 5.2.2 Cloud
- 5.2.3 Hybrid
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises (SMEs)
- 5.4 By End-user Industry
- 5.4.1 BFSI
- 5.4.2 Government and Defense
- 5.4.3 Manufacturing
- 5.4.4 Healthcare
- 5.4.5 Retail and E-commerce
- 5.4.6 Energy and Utilities
- 5.4.7 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Advanced Info Service Public Co. Ltd. (AIS)
- 6.4.2 True Digital Group Co. Ltd.
- 6.4.3 Dell Technologies Inc.
- 6.4.4 Cisco Systems Inc.
- 6.4.5 International Business Machines Corp. (IBM)
- 6.4.6 Microsoft Corporation
- 6.4.7 Hewlett Packard Enterprise Co.
- 6.4.8 Fujitsu (Thailand) Co. Ltd.
- 6.4.9 Fortinet Inc.
- 6.4.10 Palo Alto Networks Inc.
- 6.4.11 Check Point Software Technologies Ltd.
- 6.4.12 Trend Micro Inc.
- 6.4.13 Kaspersky Lab
- 6.4.14 Samsung Electronics Co. Ltd.
- 6.4.15 Acer Inc.
- 6.4.16 Lenovo Group Ltd.
- 6.4.17 G-Able Co. Ltd.
- 6.4.18 MFEC Public Co. Ltd.
- 6.4.19 Digital Government Development Agency (DGA)
- 6.4.20 SIAMDATA Co. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


