|
시장보고서
상품코드
2124728
독일의 의약품 3자 물류 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Germany Pharmaceutical 3PL - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
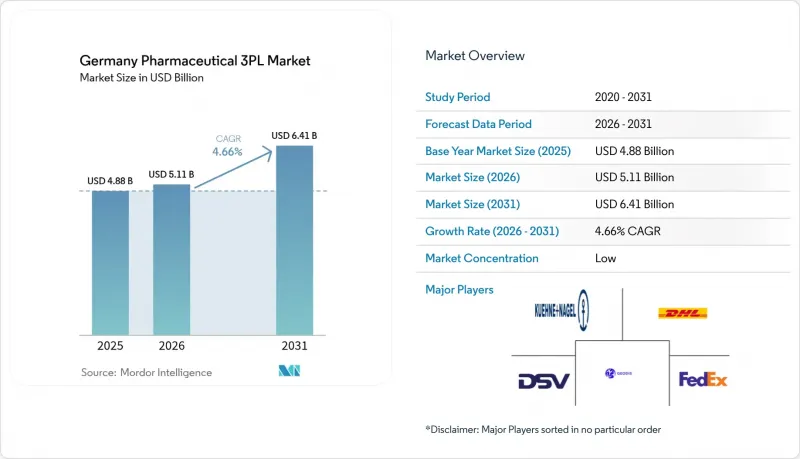
에 의하면, 독일의 의약품 3자 물류시장 규모는 2025년에 48억 8,000만 달러로 평가되었고, 2026년 51억 1,000만 달러에서 2031년까지 64억 1,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.66%를 기록할 전망입니다.
본 보고서는 서비스 유형(국내 운송 관리, 국제 운송 관리, 부가가치형 창고·유통), 최종 사용자(제약 제조업체, 바이오기술·바이오시밀러 제조업체 등), 제품 유형(처방약, OTC 의약품·소비자 건강 관리 제품 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
독일의 의약품 3자 물류 시장 동향 및 인사이트
견조한 국내 의약품 수요
고령화에 따라 처방약 처방량이 증가하고 있으며, 독일 제약 업계는 2024년에 2,000억 유로 이상의 매출을 창출하고 35만 명의 일자리를 지원하고 있습니다. 제조업체 내부의 생산 능력 제약으로 인해 재고 관리 및 유통 업무를 규제를 준수하는 3PL 파트너에게 아웃소싱하는 사례가 확대되고 있습니다. 베를린이 2023년에 발표한 ‘의약품 전략’에는 제조 인센티브 도입 및 임상시험 승인 신속화가 포함되어 있어, 이로 인해 물류의 복잡성이 더욱 가중되어 전문 업체들에게 유리한 상황이 되고 있습니다.
처방약 및 일반의약품 분야의 전자상거래 채널 가속화
DocMorris와 같은 대형 통신판매 업체들은 규제 당국의 apo-rot 인수 승인을 받아 적극적으로 사업을 확장했으며, GDP 인증 시설 내에서 상온 및 냉장 풀필먼트 라인이 필요한 라스트 마일 모델을 확립했습니다. 4개월에 걸친 ERP 통합 과정은 이 분야에서 IT의 중요성을 부각시켰으며, 3PL 각사는 자동 피킹 및 일련번호가 부여된 품목 단위 추적 시스템에 대한 투자를 서둘러야 하는 상황에 놓였습니다. 소비자들이 택배 서비스를 적극적으로 이용함에 따라, 온라인 약국에는 도매 배송과 환자에게 직접 배송을 결합한 서비스를 제공할 수 있는 파트너가 필요해지고 있습니다.
GDP/GMP 준수 시설의 높은 운영 비용
대규모 창고의 경우, 연례 감사 및 문서화에 드는 비용이 100만 유로를 초과하기도 하며, 새로운 운송 중 검증 규정에 따라 육상 화물 운송에서도 지속적인 모니터링이 요구되고 있습니다. 2024년 7월, 쾰른의 한 유통업체가 GDP 위반을 반복하여 면허가 취소되었습니다. 이는 규정 위반이 초래하는 경제적 위험의 심각성을 여실히 보여줍니다.
부문 분석
2025년, 국내 운송 관리는 독일의 의약품 3자 물류 시장 점유율의 40.35%를 차지하며, 독일이 유럽으로의 물류 교두보로서의 입지를 공고히 했습니다. 가장 빠르게 성장하고 있는 서비스인 ‘부가가치형 창고 및 물류’는 제조업체들이 GDP 준수 보관, 라벨 부착, 일련번호 부여를 외부에 위탁함에 따라 연평균 성장률(CAGR) 5.72%로 확대되고 있습니다. SSI SCHAEFER가 Losan Pharma를 위해 건설한 완전 자동화 사일로가 2025년에 가동을 시작함에 따라, 독일의 의약품 3자 물류 시장의 창고 부문 규모는 더욱 확대될 전망입니다. 긴급 생물학적 제제 운송에서는 국제 항공 노선이 여전히 필수적이며, 루프트한자 카고의 ‘Cool/td-Active’ 네트워크는 89개 거점 간에 -20°C에서 +30°C의 온도 관리 하에 운송을 보장하고 있습니다.
각 3PL 업체들이 운송, 재고 가시화, 규제 당국에 대한 신고를 단일 계약으로 통합함에 따라, 트럭 운송과 보관 사이의 기존 경계는 모호해지고 있습니다. DHL이 계획 중인 20억 유로 규모의 헬스케어 네트워크와 DSV의 DB 쉔커 인수는 전용 운송량과 자산 활용도 향상을 보장하는 규모 확대를 목표로 하는 전략의 좋은 예입니다.
콜드체인 사업은 2025년 매출의 57.75%를 차지하며 연평균 성장률(CAGR) 5.76%로 확대되고 있습니다. 이러한 성장을 주도하는 것은 온도가 좁은 허용 범위를 벗어나면 효능을 잃는 백신, 바이오의약품, 세포 치료제입니다. 독일 제약 업계의 초저온 서비스 3PL 시장 점유율은 세콥(Secop)사의 차세대 압축기가 -80℃ 냉동고 내 에너지 소비량을 두 자릿수 비율로 줄임에 따라 지속적으로 상승하고 있습니다. 상온 물류에서는 디지털 기술을 활용한 직송으로 인해 OTC 제품의 창고 체류 시간이 단축됨에 따라 요금 측면에서 압박을 받고 있습니다.
규제 당국의 감시가 강화되면서 진입 장벽이 높아지고 있습니다. EU의 GDP(의약품 유통 관리)에서는 모든 운송 경로의 검증이 의무화되어 있어, 소규모 공급업체는 투자를 하거나 시장에서 철수할 수밖에 없는 상황입니다. 자동화를 통해 일부 운영 비용이 절감됩니다. 예측형 HVAC 알고리즘과 연동된 새로운 창고 관리 시스템을 통해 30%의 에너지 절감 효과를 실현하고 있으며, 이는 전력 가격 변동이 심한 상황에서 이익의 완충 역할을 하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the Germany pharmaceutical 3PL market size was valued at USD 4.88 billion in 2025 and estimated to grow from USD 5.11 billion in 2026 to reach USD 6.41 billion by 2031, at a CAGR of 4.66% during the forecast period (2026-2031).
This report is Segmented by Service Type (Domestic Transportation Management, International Transportation Management, Value-Added Warehousing & Distribution), End User (Pharmaceutical Manufacturers, Biotech & Biosimilar Manufacturers, and More), Product Type (Prescription Drugs, OTC & Consumer Health Products, and More). The Market Forecasts are Provided in Terms of Value (USD).
Germany Pharmaceutical 3PL Market Trends and Insights
Strong Domestic Pharmaceutical Demand
Prescription volumes are growing in line with an aging population, and Germany's pharmaceutical industry generated more than EUR 200 billion in revenue in 2024, supporting 350,000 jobs. Capacity constraints inside manufacturers have triggered greater outsourcing of inventory management and distribution to compliant 3PL partners. Berlin's 2023 Pharmaceutical Strategy introduced manufacturing incentives and faster clinical-trial approvals, further increasing logistics complexity that favors specialized providers.
E-commerce Channel Acceleration for Rx & OTC Drugs
Mail-order leaders such as DocMorris scaled aggressively after regulators cleared the apo-rot acquisition, underpinning a last-mile model that demands ambient and cooled fulfillment lines inside GDP-certified facilities. Four-month ERP integrations highlight the IT intensity of this segment, prompting 3PLs to invest in automated picking and serialized, item-level tracking. As consumers embrace home delivery, e-pharmacies need partners that combine wholesale shipping with direct-to-patient drop-offs.
High Operating Costs for GDP/GMP-Compliant Facilities
Annual audit and documentation expenses can top EUR 1 million for large warehouses, and new in-transit verification rules require continuous monitoring in road freight as well. A Cologne distributor lost its license in July 2024 after repeated GDP breaches, underscoring the financial stakes of non-compliance.
Other drivers and restraints analyzed in the detailed report include:
- Rising Biologics & Advanced-Therapy Volumes Requiring GDP-Compliant Cold Chain
- End-to-End Digital Visibility Solutions Lowering Excursion Risk
- Skilled Labor Shortages in Temperature-Controlled Logistics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Domestic Transportation Management retained 40.35% of the German pharmaceutical 3PL market share in 2025, confirming the country's status as a distribution bridge into Europe. Value-Added Warehousing & Distribution, the fastest-rising service, is growing at 5.72% CAGR as manufacturers outsource GDP-compliant storage, labeling, and serialization. The German pharmaceutical 3PL market size for warehousing is set to expand further as fully automated silos such as SSI SCHAEFER's build for Losan Pharma go live in 2025. International air corridors stay vital for emergency biologics; Lufthansa Cargo's Cool/td-Active network secures -20 °C to +30 °C moves across 89 stations.
The traditional divide between trucking and storage blurs as 3PLs package transport, inventory visibility, and regulatory filing into single contracts. DHL's planned EUR 2 billion healthcare network and DSV's acquisition of DB Schenker exemplify scale-seeking strategies that lock in captive volumes and higher asset utilization.
Cold-chain operations cover 57.75% of 2025 revenue and expand at a 5.76% CAGR. Growth is fueled by vaccines, biologics, and cell therapies that lose efficacy once temperatures stray beyond narrow windows. The German pharmaceutical 3PL market share for ultra-low-temperature services keeps rising as Secop's next-gen compressors cut energy draw inside -80 °C freezers by double-digit percentages. Ambient logistics face fee pressure because digital direct shipping reduces warehouse dwell time for OTC lines.
Regulatory scrutiny elevates barriers to entry; EU GDP demands validation of every transport lane, forcing smaller providers either to invest or exit. Automation offsets some operating costs: new warehouse management systems linked to predictive HVAC algorithms achieve 30% energy savings, a margin buffer amid volatile power prices.
Complete Report Scope:
- By Service Type
- Domestic Transportation Management (DTM)
- Roadways
- Railways
- Airways
- Waterways
- International Transportation Management (ITM)
- Roadways
- Railways
- Airways
- Waterways
- Value-Added Warehousing & Distribution (VAWD)
- Domestic Transportation Management (DTM)
- By Temperature Type
- Cold Chain
- Non-cold Chain
- By End User
- Pharmaceutical Manufacturers
- Biotech & Biosimilar Manufacturers
- Clinical Research & Trial Sponsors
- Hospitals & Retail Pharmacies
- Healthcare Distributors & Wholesalers
- E-pharmacies & Direct-to-Patient Services
- Others
- By Product Type
- Prescription Drugs
- OTC & Consumer Health Products
- Biopharmaceuticals & Biosimilars (ex-CGT)
- Cell & Gene Therapies
- Vaccines & Blood-derived Products
- Veterinary Pharmaceuticals & Animal Health Products
- Medical Devices, Diagnostics & Combination Products
- Clinical-trial Materials (Investigational Medicinal Products)
- Others
List of Companies Covered in this Report:
- DHL Group
- DSV
- Kuehne + Nagel
- Rhenus Logistics
- Dachser
- CEVA Logistics
- UPS
- FedEx
- Geodis
- Hellmann Worldwide Logistics
- FIEGE Logistik
- Rohlig Logistics
- Eurotranspharma
- NextPharma Logistics
- World Courier
- Frigo-Trans
- MSK Pharma Logistics
- Loxxess Pharma
- Pharmaserv Logistics GmbH
- Pfenning Logistics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Strong domestic pharmaceutical demand
- 4.2.2 E-commerce channel acceleration for Rx & OTC drugs
- 4.2.3 Rising biologics & advanced-therapy volumes that require GDP-compliant cold-chain capacity
- 4.2.4 End-to-end digital visibility solutions lowering excursion risk
- 4.2.5 Sustainability-driven modal shift (air to sea/road) reducing carbon footprint
- 4.2.6 Surge in decentralized/virtual clinical trials driving direct-to-patient logistics needs
- 4.3 Market Restraints
- 4.3.1 High operating costs for GDP/GMP-compliant facilities
- 4.3.2 Skilled labour shortages in temperature-controlled logistics
- 4.3.3 Energy-price volatility inflating warehouse OPEX
- 4.3.4 Scarcity of GDP-approved urban micro-fulfilment space limiting last-mile service expansion
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Pharmaceutical E-commerce Outlook
- 4.8 Packaging Spotlight
- 4.9 Impact of Geopolitics & Pandemic
- 4.10 Porter's Five Forces
- 4.10.1 Bargaining Power of Suppliers
- 4.10.2 Bargaining Power of Consumers
- 4.10.3 Threat of New Entrants
- 4.10.4 Threat of Substitutes
- 4.10.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Service Type
- 5.1.1 Domestic Transportation Management (DTM)
- 5.1.1.1 Roadways
- 5.1.1.2 Railways
- 5.1.1.3 Airways
- 5.1.1.4 Waterways
- 5.1.2 International Transportation Management (ITM)
- 5.1.2.1 Roadways
- 5.1.2.2 Railways
- 5.1.2.3 Airways
- 5.1.2.4 Waterways
- 5.1.3 Value-Added Warehousing & Distribution (VAWD)
- 5.1.1 Domestic Transportation Management (DTM)
- 5.2 By Temperature Type
- 5.2.1 Cold Chain
- 5.2.2 Non-cold Chain
- 5.3 By End User
- 5.3.1 Pharmaceutical Manufacturers
- 5.3.2 Biotech & Biosimilar Manufacturers
- 5.3.3 Clinical Research & Trial Sponsors
- 5.3.4 Hospitals & Retail Pharmacies
- 5.3.5 Healthcare Distributors & Wholesalers
- 5.3.6 E-pharmacies & Direct-to-Patient Services
- 5.3.7 Others
- 5.4 By Product Type
- 5.4.1 Prescription Drugs
- 5.4.2 OTC & Consumer Health Products
- 5.4.3 Biopharmaceuticals & Biosimilars (ex-CGT)
- 5.4.4 Cell & Gene Therapies
- 5.4.5 Vaccines & Blood-derived Products
- 5.4.6 Veterinary Pharmaceuticals & Animal Health Products
- 5.4.7 Medical Devices, Diagnostics & Combination Products
- 5.4.8 Clinical-trial Materials (Investigational Medicinal Products)
- 5.4.9 Others
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 DHL Group
- 6.4.2 DSV
- 6.4.3 Kuehne + Nagel
- 6.4.4 Rhenus Logistics
- 6.4.5 Dachser
- 6.4.6 CEVA Logistics
- 6.4.7 UPS
- 6.4.8 FedEx
- 6.4.9 Geodis
- 6.4.10 Hellmann Worldwide Logistics
- 6.4.11 FIEGE Logistik
- 6.4.12 Rohlig Logistics
- 6.4.13 Eurotranspharma
- 6.4.14 NextPharma Logistics
- 6.4.15 World Courier
- 6.4.16 Frigo-Trans
- 6.4.17 MSK Pharma Logistics
- 6.4.18 Loxxess Pharma
- 6.4.19 Pharmaserv Logistics GmbH
- 6.4.20 Pfenning Logistics
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment