

|
시장보고서
상품코드
2124921
컴퓨터 및 주변기기 표준 로직 IC : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Computer And Peripherals Standard Logic IC - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
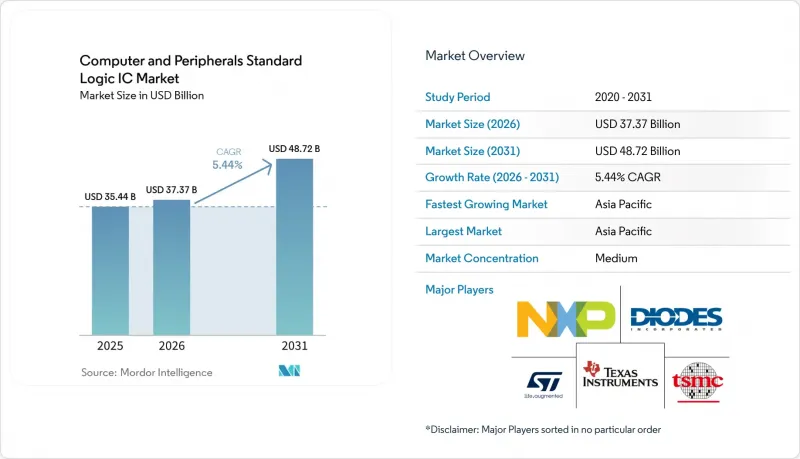
에 의하면, 컴퓨터 및 주변기기 표준 로직 IC 시장 규모는 2025년 354억 4,000만 달러로 평가되었습니다. 2026년에는 373억 7,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 5.44%로 성장을 지속하여, 2031년에는 487억 2,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 로직 패밀리별(트랜지스터-트랜지스터 로직(TTL/LS/ALS), 기타), 기능 유형별(게이트·인버터, 플립플롭·래치, 기타),패키지 유형별(스루홀 DIP/CDIP, SOIC/TSSOP, 기타), 최종 용도 기기별(개인용 컴퓨터·노트북, 프린터·스캐너·MFP, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 컴퓨터 및 주변기기용 표준 로직 IC 시장 동향 및 인사이트
초슬림형 주변기기에서 저전압 LVC 로직에 대한 수요가 급증
초슬림형 주변기기에서는 엄격한 열 설계 요건을 충족하면서 나노초 단위의 스위칭을 실현하는 1.65V-5.5V의 74LVC/AUP 디바이스가 선호되고 있으며, 이것이 2030년까지 연평균 성장률(CAGR) 6.73%를 견인하고 있습니다. USB4 및 Thunderbolt 5 허브는 콤팩트한 케이스 내에서 40Gbps 이상의 신호 전송을 필요로 한다는 점에서 이러한 변화를 상징합니다. 분산형 저전압 로직 아키텍처는 전력 소비 및 발열 측면에서 모놀리식형에 비해 우수하여, 전 세계 설계 센터와 아시아태평양의 조립 거점에서 수요를 뒷받침하고 있습니다.
AI를 활용한 자동 배선으로 인해 구성 가능한 멀티게이트 IC의 출하량이 증가
머신러닝을 활용한 PCB 설계 도구는 수천 개의 토폴로지를 몇 분 만에 평가하여, 종종 흔치 않은 게이트 조합을 선택합니다. 이로 인해 구성 가능한 멀티게이트 디바이스 수요가 23% 증가하고 있습니다. 설계 주기가 단축됨에 따라, 광범위한 파라메트릭 라이브러리와 신속한 샘플 제공이 가능한 벤더들이 수주를 확보하고 있습니다.
디스크리트 로직의 SoC 통합에 대한 설계 도입 지연
현재 첨단 SoC에는 일반적인 74 시리즈의 기능을 재현하는 프로그래머블 로직 블록이 통합되어 있어, 전자 기기 전체의 복잡성이 증가하고 있음에도 불구하고 대량 생산되는 디바이스에서 디스크리트 부품의 사용량을 줄이고 있습니다. 그러나 갈바닉 절연이나 고전압 스위칭이 필요한 기능에 대해서는 여전히 독립형 IC에 의존하고 있기 때문에 대체품의 위협은 완화되기는 하지만 완전히 배제되지는 않습니다.
부문별 분석
2025년 결과에 따르면, 고속 74HC/HCT 디바이스가 매출의 30.62%를 차지했습니다. 에너지 절약을 지향하는 첨단 노드의 혜택을 받는 저전압 74LVC/AUP 제품군은 연평균 성장률(CAGR) 6.51%로 확대될 것으로 예측되며, 이 범주에 속하는 컴퓨터 및 주변기기용 표준 로직 IC 시장 규모는 기존의 TTL 제품 라인을 능가하는 속도로 성장할 것으로 보입니다. 혼합 전압 설계에서는 비용과 타이밍의 균형을 맞추기 위해 여러 CMOS 제품군을 조합하고 있으며, 이러한 추세는 설계 부담을 줄여주는 AI 주도 CAD에 의해 가속화되고 있습니다.
이종 전압 도메인으로의 전환으로 인해, SoC의 핀만으로는 절연 및 노이즈 내성을 충족할 수 없는 경우 디스크리트 제품에 대한 수요가 유지되고 있습니다. ECL/MECL은 지터에 민감한 계측 시스템에서 틈새 시장을 유지하고 있는 반면, 4000 시리즈 CMOS는 넓은 전압 범위가 필요한 산업용 요구를 충족하고 있습니다. 패키지의 소형화가 지속됨에 따라, 컴퓨터 및 주변기기용 표준 로직 IC 시장은 단일한 지배적인 아키텍처로 수렴하기보다는 제품군의 다양성을 유지하게 될 것입니다.
2025년에는 게이트와 인버터가 그 범용성을 반영하여 25.98%의 점유율을 차지했습니다. 다중 전압 SoC가 혼합 신호 주변 기기와 인터페이스함에 따라, 신호 스위치와 레벨 변환기가 2031년까지 연평균 성장률(CAGR) 6.74%로 부문 확장을 주도하여, 컴퓨터 및 주변 기기용 표준 로직 IC 시장에서 이러한 소자의 점유율을 끌어올릴 것으로 전망됩니다. 멀티플렉서와 디코더는 멀티 디스플레이 도크를 지원하며, 버퍼는 고속 차동 쌍의 신호 무결성을 유지합니다.
설계 팀은 적응형 임계값 추적 기능을 갖춘 변환기 IC를 점점 더 선호하고 있으며, 이를 통해 전원 레일 전환으로 인한 기판 설계 반복 횟수를 줄이고 있습니다. 이러한 변화는 단순한 게이트 수보다는 인터페이스 관리에 기반한 수요 증가를 나타내며, 트랜지스터 집적도가 높아지더라도 그 가치를 유지하고 있습니다.
지역별 분석
아시아태평양은 2025년 컴퓨터 및 주변기기용 표준 로직 IC 시장에서 50.72%의 점유율로 1위를 차지했으며, 중국, 대만, 한국의 파운드리에서 조립에 이르는 일관된 생태계에 힘입어 연평균 성장률(CAGR) 8.45%로 확대될 것으로 전망됩니다. 일본의 자동차 산업을 중심으로 한 1차 공급업체들은 광범위한 온도 범위를 지원하는 제품군에 대한 수요를 뒷받침하고 있는 반면, 대만은 패널 레벨 패키징 클러스터를 통해 리더십을 확대되고 있습니다.
북미에서는 미국의 설계 회사가 구성 가능한 멀티게이트 로직이 필요한 AI 중심의 주변기기를 추진하고 있어 연평균 성장률(CAGR)이 상승할 것으로 전망됩니다. 캐나다와 멕시코는 미국 OEM 기업과의 지리적 근접성을 활용하여 기판 수준 조립을 수행하고 있으며, 웨이퍼 생산 능력이 제한적임에도 불구하고 지역 내 수요를 뒷받침하고 있습니다.
유럽에서는 자동차 전동화와 산업용 자동화를 원동력으로 연평균 성장률(CAGR)이 상승할 전망입니다. 독일의 1차 공급업체는 AEC-Q100 규격의 디바이스를 인증하고, 프랑스는 항공우주용 변형 제품을 지원하며, 이탈리아는 패널 레벨 패키징에 대한 투자를 유치함으로써 아시아 이외 지역으로공급 다각화를 도모하고 있습니다. 라틴아메리카, 중동 및 아프리카와 같은 신흥 지역은 2024년 매출에서 차지하는 비중이 전체적으로 작았지만, 인프라 중심의 네트워크 주변 기기가 향후 수요 증가를 견인할 전망입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the computer and Peripherals Standard Logic IC market size is expected to grow from USD 35.44 billion in 2025 to USD 37.37 billion in 2026 and is forecast to reach USD 48.72 billion by 2031 at 5.44% CAGR over 2026-2031.
This report is Segmented by Logic Family (Transistor-Transistor Logic (TTL / LS / ALS), and More), Function Type (Gates/Inverters, Flip-Flops/Latches, and More), Package Type (Through-Hole DIP / CDIP, SOIC/TSSOP, and More), End-Use Device (Personal Computers and Laptops, Printers, Scanners and MFPs, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Computer And Peripherals Standard Logic IC Market Trends and Insights
Surging demand for low-voltage LVC logic in ultra-thin peripherals
Ultra-thin peripherals favor 1.65 V-5.5 V 74LVC/AUP devices that deliver nanosecond switching while fitting strict thermal envelopes, propelling a 6.73% CAGR through 2030. USB4 and Thunderbolt 5 hubs exemplify this shift by requiring 40 Gbps-plus signaling in compact enclosures. Distributed low-voltage logic architectures outperform monolithic alternatives on power and heat, sustaining demand across global design centers and APAC assembly bases.
AI-assisted auto-routing increasing configurable multi-gate IC volume
Machine-learning PCB tools evaluate thousands of topologies in minutes and frequently choose uncommon gate combinations, driving a 23% rise in demand for configurable multi-gate devices. Vendors supplying broad parametric libraries and rapid samples win sockets as design cycles compress.
Design-in inertia toward SoC integration of discrete logic
Advanced SoCs now embed programmable logic blocks that replicate common 74-series functions, cutting discrete content in high-volume devices despite rising overall electronics complexity. Yet functions needing galvanic isolation or high-voltage switching still rely on stand-alone ICs, tempering but not eliminating the substitution threat.
Other drivers and restraints analyzed in the detailed report include:
- Mainstream USB-C/Thunderbolt hub upgrade cycles
- Rising attach rate of wireless keyboards and mice using low-power buffers
- Lengthening automotive-grade qualification queues (AEC-Q100)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
2025 results showed high-speed 74HC/HCT devices occupying 30.62% revenue. Low-voltage 74LVC/AUP families, benefiting from energy-sensitive edge nodes, are forecast to add 6.51% CAGR, driving the Computer and Peripherals Standard Logic IC market size in this category to outpace legacy TTL lines. Mixed-voltage designs combine multiple CMOS families to balance cost and timing, a pattern accelerated by AI-guided CAD that lowers design effort.
The migration toward heterogeneous voltage domains preserves discrete demand where SoC pins cannot satisfy isolation or noise immunity. ECL/MECL retains niche roles in jitter-sensitive acquisition systems, whereas 4000-series CMOS fulfills wide-voltage industrial needs. Continued package shrinkage ensures the Computer and Peripherals Standard Logic IC market retains family diversity rather than converging on a single dominant architecture.
Gates and inverters held a 25.98% share in 2025, reflecting their universality. Signal switches and level translators will lead segment expansion with a 6.74% CAGR to 2031 as multi-voltage SoCs interface with mixed-signal peripherals, raising the Computer and Peripherals Standard Logic IC market share for these devices. Multiplexers and decoders support multi-display docks, while buffers maintain integrity on high-speed differential pairs.
Design teams increasingly prefer translator ICs with adaptive threshold tracking, trimming board spins caused by supply-rail migrations. The shift signals demand growth rooted in interface management rather than raw gate count, sustaining value even as transistor integration climbs.
Complete Report Scope:
- By Logic Family
- Transistor-Transistor Logic (TTL / LS / ALS)
- High-Speed CMOS (74HC / HCT)
- Low-Voltage CMOS (74LVC / AUP)
- Advanced High-Speed CMOS (74AC / ACT)
- Wide-Voltage 4000-Series CMOS
- ECL / MECL and Other Bipolar Logic
- By Function Type
- Gates and Inverters
- Flip-Flops and Latches
- Counters and Dividers
- Shift Registers
- Buffers / Drivers / Transceivers
- Multiplexers / Decoders and Encoders
- Comparators and Arithmetic Logic
- Signal Switches and Level Translators
- By Package Type
- Through-Hole DIP / CDIP
- SOIC / TSSOP
- SOT-23 / SOT-353 and Other Micro-Packages
- QFN / XSON / DFN
- WLCSP / Wafer-Level Chip-Scale
- BGA / LGA
- By End-Use Device
- Personal Computers and Laptops
- Printers, Scanners and MFPs
- External Storage and Docking Stations
- Gaming Consoles and Accessories
- Networking Peripherals (Routers, Hubs)
- POS Terminals and Kiosks
- Industrial PCs and Rugged Peripherals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific led with 50.72% Computer and Peripherals Standard Logic IC market share in 2025 and is forecast to rise at an 8.45% CAGR, underpinned by integrated foundry-to-assembly ecosystems in China, Taiwan, and South Korea. Japan's automotive-centric tier-1s sustain demand for extended-temperature families, while Taiwan extends leadership through panel-level packaging clusters.
North America delivered a growing CAGR outlook as design houses in the United States push AI-centric peripherals that require configurable multi-gate logic. Canada and Mexico leverage proximity to U.S. OEMs for board-level assembly, anchoring regional demand despite limited wafer capacity.
Europe posted a growing CAGR trajectory driven by automotive electrification and industrial automation. Germany's Tier-1 suppliers qualify AEC-Q100 devices, France supports aerospace variants, and Italy attracts panel-level packaging investment that diversifies supply beyond Asia. Emerging regions in Latin America, the Middle East, and Africa collectively formed a small part of the 2024 revenue, with infrastructure-driven networking peripherals stimulating future uptake.
- Texas Instruments Incorporated
- Nexperia B.V.
- onsemi Corporation
- STMicroelectronics N.V.
- Toshiba Electronic Devices and Storage Corporation
- ROHM Co., Ltd.
- Diodes Incorporated
- Microchip Technology Inc.
- Infineon Technologies AG
- Renesas Electronics Corporation
- Maxim Integrated (Analog Devices, Inc.)
- Vishay Intertechnology, Inc.
- Lattice Semiconductor Corporation
- Skyworks Solutions, Inc.
- Taiwan Semiconductor Manufacturing Co., Ltd. (Foundry Perspective)
- Teledyne e2v Semiconductor
- Samsung Electronics Co., Ltd. (System LSI)
- NXP Semiconductors N.V.
- Broadcom Inc.
- Analog Devices, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for low-voltage LVC logic in ultra-thin peripherals
- 4.2.2 Shift-left PCB design workflows boosting single-gate (1G) logic ASPs
- 4.2.3 AI-assisted auto-routing increasing volume of configurable multi-gate ICs
- 4.2.4 Mainstream upgrade cycles for USB-C/Thunderbolt hubs
- 4.2.5 Rising attach-rate of wireless keyboards and mice using low-power buffers
- 4.2.6 Cost-down programs in ODM printers favouring 74HC/HCT drop-ins
- 4.3 Market Restraints
- 4.3.1 Design-in inertia toward SoC integration of discrete logic
- 4.3.2 Lengthening automotive-grade qualification queues (AEC-Q100)
- 4.3.3 Volatility in 200 mm foundry capacity for legacy logic nodes
- 4.3.4 Counterfeit 74-series influx in secondary channels
- 4.4 Industry Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Competition
- 4.8 Assessment of Macroeconomic Impact
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Logic Family
- 5.1.1 Transistor-Transistor Logic (TTL / LS / ALS)
- 5.1.2 High-Speed CMOS (74HC / HCT)
- 5.1.3 Low-Voltage CMOS (74LVC / AUP)
- 5.1.4 Advanced High-Speed CMOS (74AC / ACT)
- 5.1.5 Wide-Voltage 4000-Series CMOS
- 5.1.6 ECL / MECL and Other Bipolar Logic
- 5.2 By Function Type
- 5.2.1 Gates and Inverters
- 5.2.2 Flip-Flops and Latches
- 5.2.3 Counters and Dividers
- 5.2.4 Shift Registers
- 5.2.5 Buffers / Drivers / Transceivers
- 5.2.6 Multiplexers / Decoders and Encoders
- 5.2.7 Comparators and Arithmetic Logic
- 5.2.8 Signal Switches and Level Translators
- 5.3 By Package Type
- 5.3.1 Through-Hole DIP / CDIP
- 5.3.2 SOIC / TSSOP
- 5.3.3 SOT-23 / SOT-353 and Other Micro-Packages
- 5.3.4 QFN / XSON / DFN
- 5.3.5 WLCSP / Wafer-Level Chip-Scale
- 5.3.6 BGA / LGA
- 5.4 By End-Use Device
- 5.4.1 Personal Computers and Laptops
- 5.4.2 Printers, Scanners and MFPs
- 5.4.3 External Storage and Docking Stations
- 5.4.4 Gaming Consoles and Accessories
- 5.4.5 Networking Peripherals (Routers, Hubs)
- 5.4.6 POS Terminals and Kiosks
- 5.4.7 Industrial PCs and Rugged Peripherals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Colombia
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Texas Instruments Incorporated
- 6.4.2 Nexperia B.V.
- 6.4.3 onsemi Corporation
- 6.4.4 STMicroelectronics N.V.
- 6.4.5 Toshiba Electronic Devices and Storage Corporation
- 6.4.6 ROHM Co., Ltd.
- 6.4.7 Diodes Incorporated
- 6.4.8 Microchip Technology Inc.
- 6.4.9 Infineon Technologies AG
- 6.4.10 Renesas Electronics Corporation
- 6.4.11 Maxim Integrated (Analog Devices, Inc.)
- 6.4.12 Vishay Intertechnology, Inc.
- 6.4.13 Lattice Semiconductor Corporation
- 6.4.14 Skyworks Solutions, Inc.
- 6.4.15 Taiwan Semiconductor Manufacturing Co., Ltd. (Foundry Perspective)
- 6.4.16 Teledyne e2v Semiconductor
- 6.4.17 Samsung Electronics Co., Ltd. (System LSI)
- 6.4.18 NXP Semiconductors N.V.
- 6.4.19 Broadcom Inc.
- 6.4.20 Analog Devices, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


