|
시장보고서
상품코드
2124939
북미의 비디오 감시 시스템 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America Video Surveillance Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
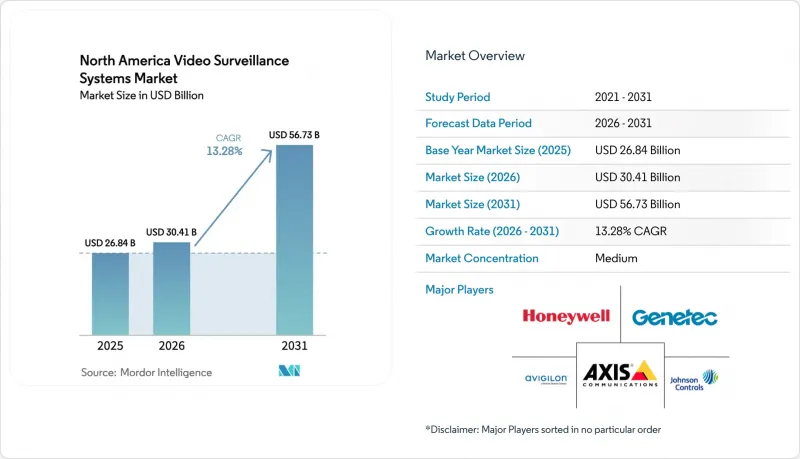
에 의하면, 2026년 북미의 비디오 감시 시스템 시장 규모는 304억 1,000만 달러로 추정되고 2025년 268억 4,000만 달러에서 확대해, 2031년에는 567억 3,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 동안의 연평균 성장률(CAGR)은 13.28%를 나타낼 전망입니다.

본 보고서는 구성 요소(하드웨어, 소프트웨어, 서비스), 배포 방식(On-Premise, 클라우드), 연결 방식(유선, 무선), 해상도(표준 해상도(SD), 고해상도(HD), 기타), 최종 사용자 산업(상업, 인프라, 기타), 국가별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
북미의 비디오 감시 시스템 시장 동향 및 인사이트
엣지 AI 칩의 발전으로 인한 미국 내 도입 시 총 소유 비용(TCO) 절감
카메라에 내장된 전용 AI 프로세서를 통해 분석 처리가 중앙 서버에서 엣지 측으로 이동하여 대역폭 수요를 최대 70%까지 줄이는 동시에 스토리지 요구 사항도 감소시키고 있습니다. NVIDIA Jetson Orin이 탑재된 플랫폼은 실시간 물체 감지, 스마트 주차, 경계 감시를 로컬에서 실행할 수 있음을 입증하여 고가의 백엔드 장비를 불필요하게 만들었습니다. 이러한 아키텍처의 변화는 기존에 중앙 집중식 분석에 막대한 설비 투자가 필요했던 소매업체, 캠퍼스, 여러 거점을 보유한 기업에게 매우 의미 있는 일입니다. 부품 가격 하락과 칩셋의 열 효율 개선에 따라 중소규모 프로젝트에서의 도입이 확대될 것으로 예상되며, 구독형 소프트웨어 업데이트에 대한 수요가 점차 높아질 것으로 전망됩니다.
미국 법 집행 기관의 바디캠 및 차량용 카메라 의무화
연방, 주, 지방 자치 단체 수준의 법적 요건에 따라 모바일 영상 기록은 공공 안전 예산에서 필수 항목으로 자리 잡고 있습니다. 현재 바디캠과 차량용 카메라는 증거 관리 중앙 시스템과 연동되어 증거 보관 경로의 추적을 자동화하고, 정보 공개 규정에 따른 신속한 공개를 가능하게 하고 있습니다. 휴대폰 회선을 이용한 백홀 도입을 시범적으로 시행하고 있는 부서에서는 범죄 억제 효과가 나타나고 있으며, 시민들의 민원도 감소하고 있습니다. 이러한 의무화는 보안 클라우드 스토리지, 디지털 증거 관리 소프트웨어, 데이터 보호 서비스와 같은 관련 분야로도 파급되어 전반적인 매출 규모를 확대시키고 있습니다.
얼굴 인식 기술 사용을 제한하는 주 차원의 감시 금지법
여러 관할 구역에 걸쳐 적용되는 생체 인식 분석에 대한 단편적인 금지 조치는 규정 준수의 복잡성과 법적 위험을 초래하고 있습니다. 전국적으로 사업을 전개하는 기업은 얼굴을 흐리게 처리하는 편집 도구를 도입하거나, 지역별로 알고리즘을 자동으로 전환해야 하므로 소프트웨어 및 프로세스 관련 부대 비용이 증가하고 있습니다. 연방 기준에 대한 불확실성으로 인해, 고도화된 분석에 의존하는 프로젝트의 조달 주기가 장기화되고 있으며, 그 기간 동안 수익 성장이 억제되고 있습니다.
부문별 분석
2025년 북미의 비디오 감시 시스템 시장의 하드웨어 시장 규모는 185억 7,000만 달러에 달하여 총 매출의 69.20%를 차지했습니다. 이는 소매 체인, 캠퍼스, 공공시설에서 대규모 카메라 도입이 지속되고 있음을 반영합니다. IP 카메라, 네트워크 비디오 레코더, 멀티 센서 장치는 고해상도와 분석 기능 지원 능력을 바탕으로 지출의 대부분을 주도하고 있습니다. 각 공급업체는 저조도 환경에서의 성능, 사이버 보안 강화, 접근 제어 및 빌딩 관리 플랫폼과의 통합을 간소화하는 오픈 API 설계를 통해 차별화를 꾀하고 있습니다. 단기적으로는 견조한 모습을 유지하겠지만, 고객이 자산 부담이 적은 조달 모델을 선호하는 경향이 있어 하드웨어 시장 점유율은 점차 감소할 것으로 예측됩니다.
2026년부터 2031년에 걸쳐 VSaaS(Video-Surveillance-as-a-Service)는 연평균 성장률(CAGR) 15.5%를 기록하며, 다른 모든 구성 요소 카테고리를 앞지를 것으로 예측됩니다. 클라우드 구독을 통해 소프트웨어 기능이 장비 교체 주기와 분리되어, 사용자는 새로운 카메라를 구매하지 않고도 새로운 AI 모듈을 활성화할 수 있게 됩니다. 이러한 변화로 인해 예산이 자본 설비에서 지속적인 운영비로 전환됨에 따라, 하드웨어 중심의 벤더들은 시장 진출 전략을 재검토하고 관리형 서비스를 패키지화해야 할 필요성에 직면해 있습니다.
2025년, 북미의 비디오 감시 시스템 시장 점유율의 84.10%를 On-Premise 도입이 차지했으며, 이는 결정론적 성능과 데이터 주권을 중시하는 산업에 의해 뒷받침되었습니다. 대형 소매업체와 공항은 기존에 지연이나 대역폭 제약을 피하기 위해 로컬 서버를 선호해 왔습니다. 그러나 이러한 인프라 확장에 드는 비용과 복잡성, 특히 클라우드 네이티브 플랫폼이 신속한 기능 출시 주기를 실현하고 있다는 점 때문에 재평가가 진행되고 있습니다.
클라우드 도입은 중앙 집중식 정책 관리, 탄력적인 스토리지, 엔터프라이즈 분석 워크로드와의 통합에 힘입어 2031년까지 연평균 15.9%의 성장이 예상됩니다. 하이브리드 모델(엣지에서의 기록과 클라우드를 통한 오케스트레이션의 조합)은 실용적인 전환 경로를 제공하고 가동 시간을 보장하는 동시에, API를 공개함으로써 점유율, 대기열 길이, 자산 활용 현황에 대한 실시간 인사이트를 기업의 대시보드에 제공합니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, North America video surveillance systems market size in 2026 is estimated at USD 30.41 billion, growing from 2025 value of USD 26.84 billion with 2031 projections showing USD 56.73 billion, growing at 13.28% CAGR over 2026-2031.
This report is Segmented by Component (Hardware, Software, Services), Deployment Mode (On-Premises, Cloud), Connectivity (Wired, Wireless), Resolution (Standard Definition (SD), High Definition (HD), and More), End-User Industry (Commercial, Infrastructure, and More), and by Country. The Market Forecasts are Provided in Terms of Value (USD).
North America Video Surveillance Systems Market Trends and Insights
Advances in Edge-AI Chips Reducing Total Cost of Ownership (TCO) in U.S. Installations
Specialized AI processors embedded inside cameras shift analytics from central servers to the edge, cutting bandwidth needs by up to 70% and lowering storage requirements. Platforms powered by NVIDIA Jetson Orin demonstrate how real-time object detection, smart parking, and perimeter monitoring can run locally, eliminating costly back-end appliances. The architectural change is meaningful for retailers, campuses, and multisite enterprises where centralized analytics previously required heavy capital spending. As component prices fall and chipsets attain higher thermal efficiency, adoption is expected to climb across small and mid-sized projects, driving incremental demand for subscription-based software updates.
Mandated Body-Worn & In-Vehicle Cameras for U.S. Law-Enforcement Agencies
Statutory requirements at federal, state, and municipal levels are turning mobile video capture into a non-discretionary line item for public-safety budgets. Body-worn and vehicle-mounted devices now integrate with central evidence management systems that automate chain-of-custody tracking and facilitate rapid disclosure under freedom-of-information rules. Departments experimenting with cellular backhaul have shown crime-deterrent benefits and reduced citizen complaints. These mandates ripple through adjacent segments such as secure cloud storage, digital-evidence software, and data-protection services, enlarging the overall revenue pool.
State-Level "Surveillance-Sanctuary" Legislation Limiting Facial Recognition Use
Patchwork bans on biometric analytics across multiple jurisdictions create compliance complexity and legal exposure. Enterprises operating nationwide must deploy redaction tools that blur faces or automatically toggle algorithms by location, increasing software and process overhead. Uncertainty about federal standards prolongs procurement cycles for projects that rely on advanced analytics, restraining revenue growth in the interim.
Other drivers and restraints analyzed in the detailed report include:
- Integration of Video Surveillance with POS & Inventory Systems in Big-Box Retail Chains
- Accelerated Uptake of Cloud-Native VSaaS among SME Multi-Site Franchises
- Escalating Cyber-Insurance Premiums for Cloud-Connected Cameras
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The North America video surveillance systems market size for hardware stood at USD 18.57 billion in 2025 and captured 69.20% of total revenue, reflecting ongoing large-scale camera roll-outs across retail chains, campuses, and utilities. IP cameras, network video recorders, and multi-sensor devices drive the bulk of spending thanks to higher resolution and analytics readiness. Suppliers differentiate through low-light performance, cybersecurity hardening, and open-API design that simplifies integration with access-control and building-management platforms. Despite near-term resilience, the hardware share is expected to erode gradually as customers favor asset-light procurement models.
During 2026-2031, Video Surveillance as a Service is projected to post a 15.5% CAGR, outstripping all other component categories. Cloud subscriptions decouple software capabilities from replacement cycles, letting users activate new AI modules without buying fresh cameras. This shift diverts budget away from capital equipment toward recurring operating expenditure, challenging hardware-centric vendors to reinvent go-to-market strategies and bundle managed services.
On-premises installations represented 84.10% of the North America video surveillance systems market share in 2025, anchored by industries that prize deterministic performance and data sovereignty. Large retailers and airports historically favored local servers to avoid latency and bandwidth constraints. Yet the cost and complexity of scaling such infrastructures are prompting a reassessment, especially as cloud-native platforms demonstrate rapid feature release cycles.
Cloud deployments are forecast to grow 15.9% annually through 2031, propelled by centralized policy management, elastic storage, and integration with enterprise analytics workloads. The hybrid model-edge recording combined with cloud orchestration-offers a pragmatic migration path, delivering uptime assurance while exposing APIs that feed corporate dashboards with real-time insights on occupancy, queue length, or asset utilization.
Complete Report Scope:
- By Component
- Hardware
- Cameras
- Analog
- IP
- Hybrid
- Storage
- Monitors
- Accessories
- Cameras
- Software
- Video Analytics
- Video Management Software
- Services
- VSaaS
- Hosted
- Managed
- Installation and Integration
- Maintenance and Support
- VSaaS
- Hardware
- By Deployment Mode
- On-Premises
- Cloud
- By Connectivity
- Wired
- Wireless
- By Resolution
- Standard Definition (SD)
- High Definition (HD)
- Full HD
- 4K and Above
- By End-User Industry
- Commercial
- Retail
- BFSI
- Hospitality and Entertainment
- Healthcare
- Infrastructure
- Transportation (Airports, Rail, Ports)
- Smart Cities
- Energy and Utilities
- Industrial
- Manufacturing
- Oil and Gas
- Mining
- Institutional
- Education
- Religious Buildings
- Residential
- Government and Law Enforcement
- Commercial
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Avigilon (Motorola Solutions)
- Axis Communications AB
- Honeywell International Inc.
- Johnson Controls International plc
- Genetec Inc.
- Dahua Technology Co., Ltd.
- Hikvision Digital Technology Co., Ltd.
- Bosch Security Systems (Robert Bosch GmbH)
- Hanwha Vision (Hanwha Techwin)
- Panasonic i-PRO Sensing Solutions
- Eagle Eye Networks, Inc.
- March Networks
- FLIR Systems, Inc. (Teledyne FLIR)
- Verkada, Inc.
- Vivotek, Inc.
- Napco Security Technologies, Inc.
- Arecont Vision Costar, LLC
- Cisco Systems, Inc. (Meraki Cam.)
- Salient Systems Corp.
- Pelco, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Advances in Edge-AI Chips Reducing Total Cost of Ownership (TCO) in U.S. Installations
- 4.2.2 Mandated Body-Worn and In-Vehicle Cameras for U.S. Law-Enforcement Agencies
- 4.2.3 Integration of Video Surveillance with POS and Inventory Systems in Big-Box Retail Chains
- 4.2.4 Accelerated Uptake of Cloud-Native VSaaS among SME Multi-Site Franchises
- 4.2.5 Surge in Federal and State Funding for School Security Modernization
- 4.2.6 Growing Adoption of Thermal and Multi-Sensor Cameras at North-American Critical Infrastructure
- 4.3 Market Restraints
- 4.3.1 State-Level Surveillance-Sanctuary Legislation Limiting Facial Recognition Use
- 4.3.2 Escalating Cyber-Insurance Premiums for Cloud-Connected Cameras
- 4.3.3 Supply-Chain Re-Shoring Raising Hardware Costs
- 4.3.4 Video Data-Retention Rules Driving Up Storage OPEX for Municipalities
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory and Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Intensity of Competitive Rivalry
- 4.6.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.1.1 Cameras
- 5.1.1.1.1 Analog
- 5.1.1.1.2 IP
- 5.1.1.1.3 Hybrid
- 5.1.1.2 Storage
- 5.1.1.3 Monitors
- 5.1.1.4 Accessories
- 5.1.1.1 Cameras
- 5.1.2 Software
- 5.1.2.1 Video Analytics
- 5.1.2.2 Video Management Software
- 5.1.3 Services
- 5.1.3.1 VSaaS
- 5.1.3.1.1 Hosted
- 5.1.3.1.2 Managed
- 5.1.3.2 Installation and Integration
- 5.1.3.3 Maintenance and Support
- 5.1.3.1 VSaaS
- 5.1.1 Hardware
- 5.2 By Deployment Mode
- 5.2.1 On-Premises
- 5.2.2 Cloud
- 5.3 By Connectivity
- 5.3.1 Wired
- 5.3.2 Wireless
- 5.4 By Resolution
- 5.4.1 Standard Definition (SD)
- 5.4.2 High Definition (HD)
- 5.4.3 Full HD
- 5.4.4 4K and Above
- 5.5 By End-User Industry
- 5.5.1 Commercial
- 5.5.1.1 Retail
- 5.5.1.2 BFSI
- 5.5.1.3 Hospitality and Entertainment
- 5.5.1.4 Healthcare
- 5.5.2 Infrastructure
- 5.5.2.1 Transportation (Airports, Rail, Ports)
- 5.5.2.2 Smart Cities
- 5.5.2.3 Energy and Utilities
- 5.5.3 Industrial
- 5.5.3.1 Manufacturing
- 5.5.3.2 Oil and Gas
- 5.5.3.3 Mining
- 5.5.4 Institutional
- 5.5.4.1 Education
- 5.5.4.2 Religious Buildings
- 5.5.5 Residential
- 5.5.6 Government and Law Enforcement
- 5.5.1 Commercial
- 5.6 By Country
- 5.6.1 United States
- 5.6.2 Canada
- 5.6.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Avigilon (Motorola Solutions)
- 6.4.2 Axis Communications AB
- 6.4.3 Honeywell International Inc.
- 6.4.4 Johnson Controls International plc
- 6.4.5 Genetec Inc.
- 6.4.6 Dahua Technology Co., Ltd.
- 6.4.7 Hikvision Digital Technology Co., Ltd.
- 6.4.8 Bosch Security Systems (Robert Bosch GmbH)
- 6.4.9 Hanwha Vision (Hanwha Techwin)
- 6.4.10 Panasonic i-PRO Sensing Solutions
- 6.4.11 Eagle Eye Networks, Inc.
- 6.4.12 March Networks
- 6.4.13 FLIR Systems, Inc. (Teledyne FLIR)
- 6.4.14 Verkada, Inc.
- 6.4.15 Vivotek, Inc.
- 6.4.16 Napco Security Technologies, Inc.
- 6.4.17 Arecont Vision Costar, LLC
- 6.4.18 Cisco Systems, Inc. (Meraki Cam.)
- 6.4.19 Salient Systems Corp.
- 6.4.20 Pelco, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment