|
시장보고서
상품코드
2124953
아시아태평양의 프로그래머블 로직 컨트롤러(PLC) : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Asia-Pacific Programmable Logic Controller - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
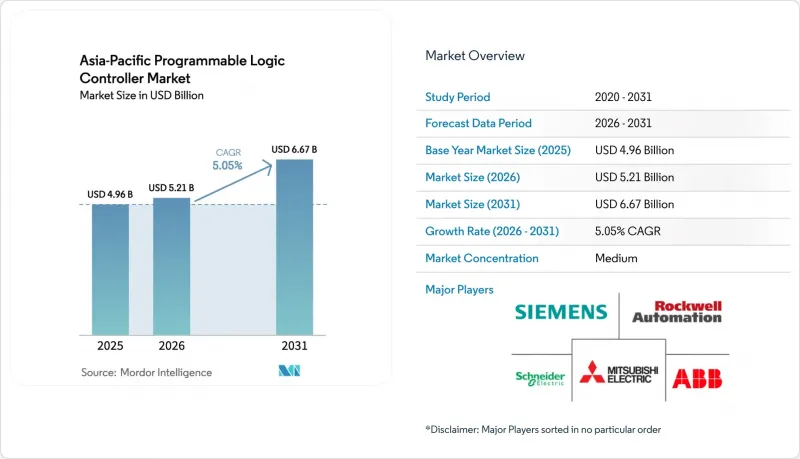
에 의하면, 아시아태평양의 프로그래머블 로직 컨트롤러(PLC) 시장 규모는 2025년 49억 6,000만 달러로 평가되었습니다. 2026년에는 52억 1,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 5.05%로 성장을 지속하여, 2031년에는 66억 7,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 유형(하드웨어, 소프트웨어, 서비스), 아키텍처(콤팩트 PLC, 모듈형 PLC, 기타), 최종 사용자(자동차, 식품·담배·음료, 화학제품 및 석유화학제품, 기타),입력/출력 유형(디지털 I/O, 아날로그 I/O, 혼합 I/O), 국가별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
아시아태평양의 프로그래머블 로직 컨트롤러(PLC) 시장 동향 및 인사이트
자동차 e-모빌리티 생산 라인의 급증
전기자동차 조립에는 배터리 팩의 정밀한 온도 관리, 다축 모터 권선의 연동, 인증된 기능 안전 제어가 요구됩니다. 중국의 각 OEM 업체들은 인근 시장에서도 현재 도입이 진행되고 있는 자동화 표준 템플릿을 확립하고 있으며, 이로 인해 PLC 벤더들은 더 빠른 처리 능력과 확장된 통신 스택의 통합을 강요받고 있습니다. e-모빌리티가 중국 밖으로 확대되는 가운데, ISO 26262의 적용으로 인해 기술적 진입 장벽은 더욱 높아지고 있습니다. 인도 및 동남아시아의 현지 생산 라인 구축 업체들은 도입 기간을 단축하기 위해 모듈형 PLC를 채택하고 있습니다. 그 결과, 벤더 간의 차별화 요소는 하드웨어의 고밀도화에서 통합 모션 라이브러리 및 전기차 전용 진단 기능으로 점차 전환되고 있습니다. 진화하는 배터리 화학 성분에 맞춘 지속적인 제품 업데이트를 통해 컨트롤러에 대한 장기적인 수요가 유지되고 있습니다.
정부 주도의 스마트 제조 보조금
중국의 ‘중국 제조 2025’, 일본의 ‘사회 5.0’, 한국의 ‘K-디지털 뉴딜’과 같은 전략적 프로그램은 자동화 도입을 가속화하기 위한 자금을 투입하고 있습니다. 보조금에 연계된 기한으로 인해 프로젝트 일정이 단축됨에 따라, 턴키 서비스 역량을 갖춘 공급업체들이 혜택을 보고 있습니다. 세액 공제 및 저리 융자를 통해 투자 회수 장벽이 낮아지면서, 중소 제조업체들이 아시아태평양의 프로그래머블 로직 컨트롤러(PLC) 시장에 진입하고 있습니다. 그러나 수요가 앞당겨짐에 따라 인센티브 종료 후 수요 둔화 위험이 발생합니다. 인도의 ‘생산 연계형 인센티브(PLI)’ 제도는 국내 조립을 촉진하여 수입 패턴에 변화를 가져올 가능성이 있습니다. 또한, 지원 대상 공장이 집적됨에 따라 생태계 내 지식 이전이 촉진되어 지역 성장의 모멘텀이 더욱 강화될 것입니다.
초기 통합 및 교육에 드는 고비용
시스템 설계, 배선, 시운전, 운영자 역량 강화 등으로 인해 프로젝트 총 비용은 하드웨어 가격의 3배에 달할 가능성이 있습니다. 인도와 동남아시아의 중소기업은 자금 조달이 어려워, 매력적인 투자 회수가 예상에도 불구하고 자동화 도입이 지연되고 있습니다. 자격을 갖춘 통합 업체 부족으로 인건비가 증가하고 공사 기간이 길어지고 있습니다. 레거시 장비와의 연동을 위해서는 대부분의 경우 맞춤형 게이트웨이가 필요하며, 이로 인해 도입 위험이 높아집니다. 장기적인 가동 중단을 우려하는 제조업체들은 자동화를 부분적으로만 실시하거나 아예 보류하는 쪽을 선택하고 있어, 아시아태평양 시장의 프로그래머블 로직 컨트롤러(PLC)에 대한 단기적인 수요를 위축시키고 있습니다. 이에 대응하여 각 벤더사는 학습 곡선을 단축하기 위해 미리 설계된 템플릿과 원격 교육 모듈을 제공합니다.
부문별 분석
각 제조업체들이 단일 하드웨어보다 통합 전문 지식, 예측 유지보수, 수명 주기 최적화를 우선시함에 따라 서비스 부문은 연평균 성장률(CAGR) 6.05%로 확대되어 가장 큰 증분 수익을 창출했습니다. 하드웨어 및 소프트웨어 구성 요소는 아시아태평양의 프로그래머블 로직 컨트롤러(PLC) 시장 점유율에서 계속해서 지배적인 위치를 차지하고 있으며, 2025년에는 75.05%를 차지했습니다. 이는 중국과 인도에서 지속되는 생산 능력 확대를 반영한 것입니다. 서비스 수익은 다년 계약의 혜택을 받고 있으며, 경기 변동에 민감한 하드웨어 판매에 비해 보다 안정적인 현금 흐름을 창출하고 있습니다. 원격 모니터링 및 클라우드 기반 분석이 이러한 변화를 뒷받침하고 있으며, 예상치 못한 가동 중지 시간을 줄이는 동시에 프리미엄 서비스 요금의 정당성을 입증하고 있습니다.
시스템 통합사업자들은 도메인 노하우를 활용하여 레거시 장비와 최신 컨트롤러를 연동함으로써 도입 기간을 단축하고 있습니다. 무선 펌웨어 업데이트와 유연한 라이선싱 체계를 통해 확장성이 향상되어 설비 투자의 장벽이 완화되고 있습니다. 석유화학 플랜트에서의 대규모 도입은 여전히 하이엔드 하드웨어에 의존하고 있지만, 분산된 IoT 노드에서는 SaaS 패키지가 탑재된 나노 컨트롤러나 마이크로컨트롤러의 도입이 확대되고 있습니다. 그 결과, 각 벤더는 포트폴리오를 성과 기반 모델로 재편하고 있으며, 아시아태평양의 프로그래머블 로직 컨트롤러(PLC) 시장에서 지속적 수익의 비중이 확대되고 있습니다.
모듈형 PLC는 복잡한 생산 라인에서의 확장성이 높이 평가되어 2025년에도 매출 점유율 55.10%를 유지했습니다. 그럼에도 불구하고, 가상화 기술을 통해 산업용 PC에서 확정적인 성능이 실현됨에 따라 소프트 PLC 플랫폼은 연평균 성장률(CAGR) 6.68%를 기록하며 기존 벤더들의 점유율을 잠식하고 있습니다. 자동차 배터리 생산 라인을 조기에 도입한 기업들은 컨테이너화된 제어 용도를 도입하여 레시피의 신속한 변경과 중앙 집중식 버전 관리를 실현하고 있습니다. 랙 마운트형 구성은 공정 산업에서 요구되는 고밀도 I/O에 대응하는 한편, 콤팩트 유닛은 스키드 장착형 장비나 OEM 기계에 적합합니다.
엣지 게이트웨이는 프로그래머블 로직, 데이터 집계, AI 추론을 단일 보드에 통합함으로써 서로 다른 기능 간의 경계를 모호하게 만들고 있습니다. 각 벤더는 실시간 하이퍼바이저, 보안 부팅 시퀀싱, IT 오케스트레이션 도구와의 호환성을 통해 차별화를 꾀하고 있습니다. 그 결과, 구매자들은 개별 컨트롤러 모델이 아닌 시스템 전체의 아키텍처를 평가하게 되었으며, 아시아태평양의 프로그래머블 로직 컨트롤러(PLC) 시장에서 조달 기준이 재구성되고 있습니다. 소프트웨어 플랫폼이 성숙해짐에 따라 하드웨어 교체 주기는 단축되고, 구독형 업그레이드가 촉진될 전망입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the Asia-Pacific programmable logic controller market size is expected to grow from USD 4.96 billion in 2025 to USD 5.21 billion in 2026 and is forecast to reach USD 6.67 billion by 2031 at 5.05% CAGR over 2026-2031.
This report is Segmented by Type (Hardware and Software and Services), Architecture (Compact PLC, Modular PLC, and More), End-User (Automotive, Food, Tobacco and Beverage, Chemical and Petrochemical, and More), Input/Output Type (Digital I/O, Analog I/O, and Mixed I/O), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Asia-Pacific Programmable Logic Controller Market Trends and Insights
Surge in Automotive E-mobility Production Lines
Electric-vehicle assembly requires precise temperature management of the battery pack, coordination of multi-axis motor windings, and certified functional safety controls. China's OEMs have established reference automation templates that neighboring markets are now replicating, compelling PLC vendors to incorporate higher-speed processing and expanded communication stacks. ISO 26262 mandates further raising technical entry barriers as e-mobility expands beyond China. Localized line-builders in India and Southeast Asia source modular PLCs to shorten deployment times. Vendor differentiation is therefore shifting from hardware density to integrated motion libraries and EV-specific diagnostics. Continuous product updates, aligning with evolving battery chemistries, sustain long-term demand for controllers.
Government-led Smart Manufacturing Subsidies
Strategic programs such as China's "Made in China 2025," Japan's Society 5.0, and South Korea's K-Digital New Deal inject funding that accelerates automation procurement. Subsidy-linked deadlines compress project timelines, benefiting suppliers with turnkey service capabilities. Tax credits and low-interest loans lower payback thresholds, drawing small and medium manufacturers into the Asia-Pacific programmable logic controller market. However, pull-forward demand risks post-incentive slowdowns. India's Production Linked Incentive scheme fosters domestic assembly, potentially altering import patterns. Clustering of subsidized plants also enhances ecosystem knowledge transfer, reinforcing regional growth momentum.
High Upfront Integration and Training Costs
Total project outlays can triple the hardware price due to system design, wiring, commissioning, and operator upskilling. SMEs in India and Southeast Asia struggle to secure financing, which delays automation despite its attractive paybacks. Shortages of qualified integrators inflate labor costs and extend timelines. Legacy equipment interfacing often requires custom gateways, which raises implementation risk. Manufacturers wary of prolonged shutdowns opt for partial or no automation, tempering near-term demand for programmable logic controllers in the Asia-Pacific market. Vendors respond with pre-engineered templates and remote training modules to compress learning curves.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Expansion of Low-cost Modular PLCs
- Migration to Industry 4.0 Cyber-secure PLC Platforms
- Prolonged Semiconductor Supply Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services generated the highest incremental revenue, expanding at a 6.05% CAGR, as manufacturers prioritize integration expertise, predictive maintenance, and lifecycle optimization over standalone hardware. Hardware and software components continued to dominate the Asia-Pacific programmable logic controller market share, accounting for 75.05% in 2025, reflecting ongoing capacity expansions in China and India. Services revenue benefits from multi-year contracts, delivering steadier cash flows than cyclical hardware sales. Remote monitoring and cloud-based analytics underpin this shift, reducing unplanned downtime and justifying premium service fees.
System integrators leverage domain know-how to bridge legacy equipment with modern controllers, compressing deployment timelines. Over-the-air firmware updates and flexible licensing enhance scalability, mitigating capital-expenditure hurdles. Large installations in petrochemical plants still rely on high-end hardware, but nano- and microcontrollers with SaaS packages are gaining traction in dispersed IoT nodes. Consequently, vendors reorient portfolios toward outcome-based models, expanding the Asia-Pacific programmable logic controller market's recurring-revenue proportion.
Modular PLCs retained 55.10% revenue leadership in 2025, favored for their expandability in complex lines. Nonetheless, soft PLC platforms posted a 6.68% CAGR, eroding incumbents' share as virtualization delivers deterministic performance on industrial PCs. Early adopters in automotive battery lines deploy containerized control applications to enable rapid recipe changes and centralized version management. Rack-mount configurations address dense I/O needs in process industries, whereas compact units cater to skid-mounted equipment and OEM machinery.
Edge gateways integrate programmable logic, data aggregation, and AI inference on a single board, thereby blurring the boundaries between different functions. Vendors differentiate through real-time hypervisors, secure boot sequences, and compatibility with IT orchestration tools. As a result, buyers evaluate total system architecture rather than discrete controller models, reshaping procurement criteria within the Asia-Pacific programmable logic controller market. Continued maturation of the soft platform will likely compress hardware refresh cycles, encouraging subscription-based upgrades.
Complete Report Scope:
- By Type
- Hardware and Software
- Large PLC
- Nano PLC
- Small PLC
- Medium PLC
- Software
- Other Types
- Services
- Hardware and Software
- By Architecture
- Compact PLC
- Modular PLC
- Rack-mount PLC
- Soft PLC (PC-based)
- By End-User
- Automotive
- Food, Tobacco and Beverage
- Chemical and Petrochemical
- Energy and Utilities
- Oil and Gas
- Water and Wastewater Treatment
- Pharmaceutical
- Pulp and Paper
- Other End-Users
- By Input / Output Type
- Digital I/O
- Analog I/O
- Mixed I/O
- By Country
- China
- Japan
- India
- South Korea
- South-East Asia
- Rest of Asia Pacific
List of Companies Covered in this Report:
- ABB Ltd.
- Mitsubishi Electric Corporation
- Schneider Electric SE
- Rockwell Automation Inc.
- Siemens AG
- Honeywell International Inc.
- Omron Corporation
- Panasonic Holdings Corporation
- Robert Bosch GmbH
- Emerson Electric Co.
- Hitachi Ltd.
- Toshiba International Corporation
- Delta Electronics Inc.
- Beckhoff Automation GmbH and Co. KG
- LS Electric Co., Ltd.
- Fuji Electric Co., Ltd.
- B and R Industrial Automation GmbH
- IDEC Corporation
- Yokogawa Electric Corporation
- WAGO Kontakttechnik GmbH and Co. KG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors
- 4.3 Market Drivers
- 4.3.1 Surge in automotive e-mobility production lines
- 4.3.2 Government-led smart-manufacturing subsidies
- 4.3.3 Rapid expansion of low-cost modular PLCs
- 4.3.4 Migration to Industry 4.0 cyber-secure PLC platforms
- 4.3.5 Demand for energy-efficient utility automation
- 4.3.6 Emerging 5G-enabled time-sensitive networking (TSN)
- 4.4 Market Restraints
- 4.4.1 High upfront integration and training costs
- 4.4.2 Prolonged semiconductor supply constraints
- 4.4.3 Availability of low-code soft-PLC substitutes
- 4.4.4 Rising cyber-security compliance expenditures
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Hardware and Software
- 5.1.1.1 Large PLC
- 5.1.1.2 Nano PLC
- 5.1.1.3 Small PLC
- 5.1.1.4 Medium PLC
- 5.1.1.5 Software
- 5.1.1.6 Other Types
- 5.1.2 Services
- 5.1.1 Hardware and Software
- 5.2 By Architecture
- 5.2.1 Compact PLC
- 5.2.2 Modular PLC
- 5.2.3 Rack-mount PLC
- 5.2.4 Soft PLC (PC-based)
- 5.3 By End-User
- 5.3.1 Automotive
- 5.3.2 Food, Tobacco and Beverage
- 5.3.3 Chemical and Petrochemical
- 5.3.4 Energy and Utilities
- 5.3.5 Oil and Gas
- 5.3.6 Water and Wastewater Treatment
- 5.3.7 Pharmaceutical
- 5.3.8 Pulp and Paper
- 5.3.9 Other End-Users
- 5.4 By Input / Output Type
- 5.4.1 Digital I/O
- 5.4.2 Analog I/O
- 5.4.3 Mixed I/O
- 5.5 By Country
- 5.5.1 China
- 5.5.2 Japan
- 5.5.3 India
- 5.5.4 South Korea
- 5.5.5 South-East Asia
- 5.5.6 Rest of Asia Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level overview, Market level overview, Core segments, Financials as available, Strategic information, Market rank/share for key companies, Products and services, and Recent developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Mitsubishi Electric Corporation
- 6.4.3 Schneider Electric SE
- 6.4.4 Rockwell Automation Inc.
- 6.4.5 Siemens AG
- 6.4.6 Honeywell International Inc.
- 6.4.7 Omron Corporation
- 6.4.8 Panasonic Holdings Corporation
- 6.4.9 Robert Bosch GmbH
- 6.4.10 Emerson Electric Co.
- 6.4.11 Hitachi Ltd.
- 6.4.12 Toshiba International Corporation
- 6.4.13 Delta Electronics Inc.
- 6.4.14 Beckhoff Automation GmbH and Co. KG
- 6.4.15 LS Electric Co., Ltd.
- 6.4.16 Fuji Electric Co., Ltd.
- 6.4.17 B and R Industrial Automation GmbH
- 6.4.18 IDEC Corporation
- 6.4.19 Yokogawa Electric Corporation
- 6.4.20 WAGO Kontakttechnik GmbH and Co. KG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment