|
시장보고서
상품코드
2125286
아시아태평양의 교류 드라이브 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Asia-Pacific Alternating Current (AC) Drive - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
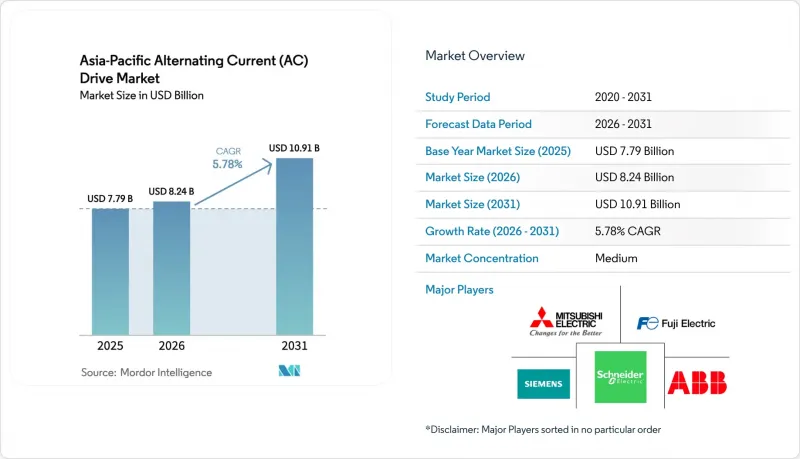
에 의하면, 2026년 아시아태평양의 교류 드라이브 시장 규모는 82억 4,000만 달러로 추정되고 2025년 77억 9,000만 달러에서 확대해, 2031년에는 109억 1,000만 달러에 이를 것으로 예측됩니다. 2026-2031년에 걸친 CAGR은 5.78%를 나타낼 전망입니다.
본 보고서는 전압별(저전압, 중전압), 정격 출력별(0.4kW 이하, 0.4-11kW, 기타), 구동 방식별(VSI, CSI, PWM), 용도별(펌프, 팬, 압축기, 기타), 최종 사용자 산업별(석유 및 가스,화학제품 및 석유화학제품, 발전, 상하수도 처리, 금속 및 광업, HVAC, 식음료, 디스크리트 제조, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러)으로 제시되어 있습니다.
아시아태평양의 교류 드라이브 시장 동향 및 인사이트
에너지 절약 및 에너지 효율화에 대한 수요 증가
모터 시스템은 아시아태평양 제조업에서 사용되는 전체 전력의 45%에 가까운 양을 소비하고 있어, 에너지 효율화 대책의 자연스러운 대상이 되고 있습니다. 중국이 2024년에 제정한 기준에 따라 0.75kW를 초과하는 모터의 최소 효율이 IE3로 상향 조정됨에 따라, 많은 공장에서 고효율 모터와 가변속 드라이브를 결합하여 사용하고 있습니다. 2024년부터 2025년에 걸쳐 산업용 전기 요금이 18% 상승함에 따라 드라이브의 평균 투자 회수 기간은 2년 미만으로 단축되었으며, 개조 프로그램이 가속화되고 있습니다. 싱가포르도 유사한 IE3 기준을 의무화함에 따라, 지역 전체적으로 규제에 따른 수요가 더욱 강화되고 있습니다. 현재 공장 관리자들은 펌프와 팬의 부하가 20-50% 감소했음을 보여주는 클라우드 대시보드를 통해 에너지 절감 효과를 확인하고 있으며, 드라이브는 업무 효율 향상의 핵심 요소로서 확고한 입지를 다지고 있습니다.
급속한 산업화와 도시 개발
인도의 1조 4,000억 달러 규모의 ‘국가 인프라 계획’에는 정밀한 모터 제어가 필요한 공항, 지하철, 스마트 공장이 추가되었습니다. 260억 달러 규모의 ‘생산 연계형 인센티브 제도’는 새로운 전자기기 및 자동차 공장의 입지를 뒷받침하고 있으며, 각 공장에서는 컨베이어, 프레스 기계, HVAC 시스템용으로 드라이브가 지정되고 있습니다. 동남아시아에서도 유사한 움직임이 관찰됩니다. 베트남의 수출 지향형 산업단지에서는 세계적 품질 기준을 확보하기 위해 가동 초기부터 첨단 드라이브가 채택되고 있습니다. 방콕, 자카르타, 마닐라의 도시 건축 기준에는 현재 그린 빌딩 요건이 포함되어 있어, 이를 통해 가변 속도로 HVAC를 운전하는 것이 암묵적으로 권장되고 있습니다. 이러한 프로젝트들이 합쳐지면, 설령 세계 무역이 둔화되더라도 높은 기준선 수요가 유지될 것입니다.
중전압 드라이브의 높은 초기 투자 비용
중전압(MV) 인버터 1대의 가격은 현장 배선 공사를 제외하고도 10만 달러를 초과하는 경우가 있어, 재무 부서는 신중한 태도를 취할 수밖에 없습니다. 소규모 광산이나 상수도 유틸리티자는 수명 주기 전반에 걸친 비용 절감이 예상에도 불구하고, 중전압 시스템의 업그레이드를 미루고 있습니다. 2024년 11월에 출시된 ABB의 ACS8080은 설치 면적을 25% 줄이고 안전 릴레이를 내장함으로써 부대 비용을 최소화했습니다. 그럼에도 불구하고 많은 구매자들은 전문 ESCO(에너지 서비스 회사)에 부담을 전가하는 에너지 성과 계약이나 DaaS(Drive-as-a-Service) 모델을 채택하고 있습니다.
부문별 분석
2025년, 저전압 드라이브는 아시아태평양의 교류 드라이브 시장 점유율의 69.05%를 차지했습니다. 이는 제조업 및 빌딩 서비스 부문에 널리 도입된 정격 전압 1kV 미만의 모터 그룹에 적합함을 반영합니다. 부품 가격 하락으로 인해 초기 비용이 중소규모 공장에서도 감당할 수 있는 수준으로 억제되고 있어, 2025년에도 이러한 제품에 대한 수요는 견조한 추세를 보였습니다. 중전압 제품은 현재 시장 점유율이 작지만, 광업, 해수 담수화, 지역 냉방 프로젝트에서 1MW를 초과하는 정격 출력이 요구됨에 따라 2031년까지 연평균 성장률(CAGR) 7.26%를 나타낼 것으로 예측됩니다.
산업용 시공업체들은 향후 개조 비용을 피하기 위해 신규 시설에 중전압 인버터를 통합하는 설계를 점점 더 늘리고 있습니다. 실리콘 카바이드(SiC) 스위치를 통해 효율이 98%로 향상되었고, 더욱 큰 에너지 절감 효과 덕분에 사업자들은 높은 설비 투자(Capex)를 정당화할 수 있게 되었습니다. 인도 및 베트남에서의 현지 조립을 통해 납품 비용이 더욱 절감되는 한편, 통합된 안전 기능으로 인해 보조 패널의 필요성이 줄어들고 있습니다. 전반적으로 전압별 구성은 저전압 유닛이 안정적인 핵심을 이루고 있으며, 중전압 솔루션의 프리미엄 부문이 가속화되고 있는 상황입니다.
2025년, 아시아태평양의 교류 드라이브 시장 규모의 37.12%를 차지한 것은 정격 0.4-11kW의 드라이브였으며, 이들은 경공업의 가동을 지원하는 펌프, 팬, 컨베이어의 동력원이 되고 있습니다. 표준화에 따라 평균 판매 가격은 완만한 하락 추세를 유지하고 있으며, 이로 인해 기존 고정 속도 모터의 개조 대상 범위가 확대되고 있습니다. 132kW를 초과하는 기종은 대수는 적지만, 2026-2031년에 걸쳐 석유화학, 지하철, 철강 프로젝트에서 에너지 사용량 감축과 공정 안정성 향상을 위해 고출력 제어가 요구됨에 따라 연평균 성장률(CAGR) 6.68%로 확대되고 있습니다.
고출력 인버터에는 현재 회생 제동 및 액티브 프론트 엔드 기술이 표준 기능으로 탑재되어 있어, 전력 규제 당국의 기대에 부응하는 계통 품질에 따른 이점을 제공합니다. 중출력 대역의 11-132kW 모델에는 클라우드 게이트웨이가 내장되어 있어, 추가 하드웨어 없이도 원격 모니터링이 가능합니다. 0.4kW 미만의 부문에서는 정밀 공구 등 틈새 용도에서 규모는 소규모이지만 안정적인 수량을 유지하고 있습니다. 이처럼 출력 등급 전반에 걸쳐 수요가 균형 있게 분산되어 있어, 공급업체는 특정 출력 대역 수요 변동으로부터 영향을 덜 받게 됩니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the Asia-Pacific AC drive market size in 2026 is estimated at USD 8.24 billion, growing from 2025 value of USD 7.79 billion with 2031 projections showing USD 10.91 billion, growing at 5.78% CAGR over 2026-2031.
This report is Segmented by Voltage (Low Voltage, and Medium Voltage), Power Rating (Less Than or Equal To 0. 4 KW, 0. 4-11 KW, and More), Drive Type (VSI, CSI, and PWM), Application (Pumps, Fans, Compressors, and More), End-User (Oil and Gas, Chemical, Power, Water, Metals, HVAC, Food, Manufacturing, and More), and Geography. Market Forecasts are Provided in Terms of Value (USD).
Asia-Pacific Alternating Current (AC) Drive Market Trends and Insights
Increasing Demand for Energy Savings and Efficiency
Motor systems consume nearly 45% of all electricity used in Asia-Pacific manufacturing, making them a natural target for energy efficiency measures. China's 2024 standard raised minimum efficiencies to IE3 for motors above 0.75 kW, prompting many factories to pair premium-efficiency machines with variable-speed drives. As industrial power tariffs increased by 18% between 2024 and 2025, the average drive payback period dropped below two years, accelerating retrofit programs. Singapore imposed similar IE3 mandates, reinforcing a regionwide regulatory pull. Factory managers now verify energy savings using cloud dashboards that show 20-50% reductions in pump and fan loads, solidifying drives as a core element of operational excellence.
Rapid Industrialization and Urban Development
India's USD 1.4 trillion National Infrastructure Pipeline adds airports, metros, and smart factories that require precise motor control. Production-Linked Incentive schemes worth USD 26 billion anchor new electronics and automotive plants, each specifying drives for conveyors, presses, and HVAC systems. Southeast Asia is a parallel story: Vietnam's export-oriented industrial parks adopt advanced drives from day one to ensure global quality standards. Urban building codes in Bangkok, Jakarta, and Manila now embed green-building requirements that implicitly favor variable-speed HVAC operation. Together, these projects sustain high baseline demand even if global trade softens.
High Up-Front Capital Cost for Medium-Voltage Drives
A single medium-voltage (MV) inverter can exceed USD 100,000 before site wiring, making finance teams cautious. Smaller mines and water utilities defer MV upgrades despite lifecycle savings. The ABB ACS8080, launched in November 2024, reduces its footprint by 25% and integrates safety relays to minimize ancillary costs. Even so, many buyers adopt energy-performance contracts or drive-as-a-service models that shift the burden to specialist ESCOs.
Other drivers and restraints analyzed in the detailed report include:
- Government Policies Favoring Industrial Electrification
- Declining Cost of Power Electronics Components
- Technical Skill-Gap in Drive Programming and Tuning
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Low-voltage drives captured 69.05% of the Asia-Pacific AC drive market share in 2025, reflecting their suitability for the vast installed base of motors with a voltage rating of less than 1 kV across manufacturing and building services. Demand for these units remains solid in 2025 because falling component prices keep initial costs within reach of small and mid-size factories. Medium-voltage products, although a smaller slice today, are expected to benefit from a 7.26% CAGR through 2031 as mining, desalination, and district cooling projects specify power ratings above 1 MW.
Industrial contractors are increasingly designing medium-voltage inverters into new facilities to avoid later retrofit expenses. Silicon-carbide switches raise efficiency to 98%, helping operators justify higher capex with sharper energy savings. Local assembly in India and Vietnam further lowers delivered costs, while integrated safety functions reduce the need for auxiliary panels. Overall, the voltage mix shows a stable core in low-voltage units and an accelerating premium tier in medium-voltage solutions.
Drives rated 0.4-11 kW accounted for 37.12% of the Asia-Pacific AC drive market size in 2025, powering pumps, fans, and conveyors that underpin light-industry operations. Standardization keeps average selling prices on a gentle downward path, widening the retrofit pool for legacy fixed-speed motors. Units above 132 kW, although fewer in number, expand at a 6.68% CAGR as petrochemical, metro, and steel projects specify high-power control to reduce energy use and improve process stability between 2026 and 2031.
High-power inverters now ship with regenerative braking and active-front-end technology as standard features, adding grid-quality benefits that align with utility regulators' expectations. Mid-range 11-132 kW models incorporate built-in cloud gateways, allowing for remote monitoring without the need for additional hardware. Below 0.4 kW, niche applications in precision tooling maintain modest yet steady volumes. This balanced spread across power classes cushions suppliers from demand swings in any single rating band.
Complete Report Scope:
- By Voltage
- Low Voltage
- Medium Voltage
- By Power Rating
- less than or equal to 0.4 kW
- 0.4 - 11 kW
- 11 - 132 kW
- Above 132 kW
- By Drive Type
- VSI Drives
- CSI Drives
- PWM Drives
- By Application
- Pumps
- Fans
- Compressors
- Conveyors
- HVAC
- Other Application
- By End-User Industry
- Oil and Gas
- Chemical and Petrochemical
- Power Generation
- Water and Wastewater
- Metals and Mining
- HVAC
- Food and Beverage
- Discrete Manufacturing
- Other End-User Industry
- By Country
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia Pacific
List of Companies Covered in this Report:
- ABB Ltd.
- Siemens AG
- Schneider Electric SE
- Mitsubishi Electric Corporation
- Fuji Electric Co. Ltd.
- Danfoss A/S
- Hitachi Ltd.
- Toshiba Infrastructure Systems and Solutions Corporation
- Yaskawa Electric Corporation
- Nidec Corporation
- WEG Equipamentos Eletricos S.A.
- Hiconics Eco-Energy Technology Co. Ltd.
- Teco Electric and Machinery Co. Ltd.
- Rockwell Automation Inc.
- Larsen and Toubro Limited
- Inovance Technology Co. Ltd.
- Delta Electronics Inc.
- KEB Automation KG
- CG Power and Industrial Solutions Limited
- Bonfiglioli Riduttori S.p.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Demand for Energy Savings and Efficiency
- 4.2.2 Rapid Industrialisation and Urban Development
- 4.2.3 Government Policies Favouring Industrial Electrification
- 4.2.4 Declining Cost of Power Electronics Components
- 4.2.5 Mandatory Motor-Efficiency Standards across Asia Pacific
- 4.2.6 Surge in Renewable-Powered Pump and Fan Installations
- 4.3 Market Restraints
- 4.3.1 High Up-Front Capital Cost for Medium-Voltage Drives
- 4.3.2 Technical Skill-Gap in Drive Programming and Tuning
- 4.3.3 Supply-Chain Volatility for IGBT and Power Modules
- 4.3.4 Price Pressure from Low-Cost Regional Manufacturers
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Threat of Substitutes
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Bargaining Power of Suppliers
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Voltage
- 5.1.1 Low Voltage
- 5.1.2 Medium Voltage
- 5.2 By Power Rating
- 5.2.1 less than or equal to 0.4 kW
- 5.2.2 0.4 - 11 kW
- 5.2.3 11 - 132 kW
- 5.2.4 Above 132 kW
- 5.3 By Drive Type
- 5.3.1 VSI Drives
- 5.3.2 CSI Drives
- 5.3.3 PWM Drives
- 5.4 By Application
- 5.4.1 Pumps
- 5.4.2 Fans
- 5.4.3 Compressors
- 5.4.4 Conveyors
- 5.4.5 HVAC
- 5.4.6 Other Application
- 5.5 By End-User Industry
- 5.5.1 Oil and Gas
- 5.5.2 Chemical and Petrochemical
- 5.5.3 Power Generation
- 5.5.4 Water and Wastewater
- 5.5.5 Metals and Mining
- 5.5.6 HVAC
- 5.5.7 Food and Beverage
- 5.5.8 Discrete Manufacturing
- 5.5.9 Other End-User Industry
- 5.6 By Country
- 5.6.1 China
- 5.6.2 India
- 5.6.3 Japan
- 5.6.4 South Korea
- 5.6.5 Australia and New Zealand
- 5.6.6 Rest of Asia Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Siemens AG
- 6.4.3 Schneider Electric SE
- 6.4.4 Mitsubishi Electric Corporation
- 6.4.5 Fuji Electric Co. Ltd.
- 6.4.6 Danfoss A/S
- 6.4.7 Hitachi Ltd.
- 6.4.8 Toshiba Infrastructure Systems and Solutions Corporation
- 6.4.9 Yaskawa Electric Corporation
- 6.4.10 Nidec Corporation
- 6.4.11 WEG Equipamentos Eletricos S.A.
- 6.4.12 Hiconics Eco-Energy Technology Co. Ltd.
- 6.4.13 Teco Electric and Machinery Co. Ltd.
- 6.4.14 Rockwell Automation Inc.
- 6.4.15 Larsen and Toubro Limited
- 6.4.16 Inovance Technology Co. Ltd.
- 6.4.17 Delta Electronics Inc.
- 6.4.18 KEB Automation KG
- 6.4.19 CG Power and Industrial Solutions Limited
- 6.4.20 Bonfiglioli Riduttori S.p.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment