|
시장보고서
상품코드
2125302
교류 모터 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Alternating Current (AC) Motor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
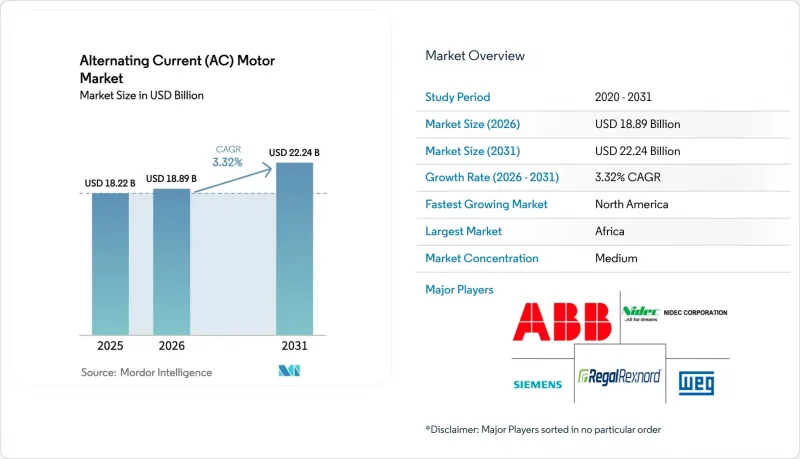
에 의하면, 교류 모터 시장 규모는 2025년 182억 3,000만 달러로 평가되었습니다. 2026년 188억 9,000만 달러에서 2031년까지 222억 4,000만 달러로 확대되고 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 3.32%를 나타낼 전망입니다.
본 보고서는 모터의 유형(유도 교류 모터·동기 교류 모터), 전압 등급(저전압, 중전압, 고전압), 정격 출력(1kW 미만, 1-100kW, 그 이상), 효율 등급(IE1, IE2, 그 이상), 최종 사용자 산업(석유 및 가스,화학, 발전, 기타) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 교류 모터 시장 동향 및 인사이트
의무화된 에너지 효율 규제가 교체 주기의 가속화를 뒷받침하고 있습니다.
유럽연합(EU)에서는 0.75kW를 초과하는 모터에 대해 IE4 기준이 의무화되어 있으며, 중국, 미국, 인도의 IE3 최저 기준 또한 기존의 IE1-IE2 규격 모터군의 조기 퇴역을 촉진하고 있습니다. 규제 준수에 따라 전 세계 제품 라인은 초프리미엄 플랫폼으로 수렴되고 있으며, 대규모 제조 능력과 통일된 인증을 보유한 공급업체가 유리한 입장에 있습니다. 최종 사용자에게 있어 연간 7,000시간 가동되는 75kW IE4 모터는 전력 비용을 1,200달러 가까이 절감할 수 있으며, 초기 비용 차액을 3년 이내에 회수할 수 있습니다. 따라서 운영 예산의 60% 이상을 모터의 전력 소비에 지출하고 있는 전력 회사와 공정 산업은 수년 단위의 조달 계획을 확정하고 있습니다. 그 결과, 규제 기준이 지속적으로 상향 조정되는 가운데, 교류 모터 시장에서는 고효율 설계로의 구조적 전환이 진행되고 있습니다.
산업용 자동화 및 로봇의 급속한 보급이 모터 수요를 재편
2024년, 전 세계 로봇 설치 대수는 54만 대를 돌파했으며, 밀리초 미만의 위치 결정 정밀도를 가진 수백만 대의 영구자석 서보 모터가 탑재되었습니다. 자동차 및 전자기기 조립 라인에서는 공기압 실린더에서 서보 구동으로의 전환이 진행되고 있으며, 사이클 타임을 15% 이상 단축하고 에너지 소비를 최대 50% 절감하고 있습니다. 협동 로봇의 도입이 가장 빠르게 확대되고 있으며, 10밀리초의 안전 정지 응답이 가능한 저관성 프레임리스 모터가 요구되고 있습니다. 창고 자동화도 추가적인 수요를 견인하고 있으며, 각 자율 주행 로봇에는 여러 대의 소형 교류 드라이브가 탑재되어 있습니다. 중국, 한국, 일본에서의 집중적인 도입으로 인해 아시아태평양은 계속해서 교류 모터 시장 수요를 주도하고 있습니다.
구리와 희토류 가격 변동이 이익률을 압박하여 수주를 지연시키고 있습니다.
2024년부터 2025년에 걸쳐 구리 가격은 1미터톤당 8,000달러에서 1만 500달러 사이를 오가며 고정 가격 계약의 수익성을 저해하고, 공급업체들이 견적 유효 기간을 30일 미만으로 단축하는 요인이 되었습니다. 중국의 수출 할당량 축소로 인해 네오디뮴·철·붕소 자석 가격이 12-18% 상승하여, 영구 자석 모터의 재료비는 20kW급 모터 1대당 최대 120달러 증가했습니다. 가격에 민감한 시장에서는 구매자들이 희토류에 대한 의존을 피하기 위해 IE3 유도 전동기를 사후 장착 사양으로 지정하고 있으며, 이로 인해 교류(AC) 전동기 시장의 고효율화 진전이 둔화되고 있습니다. 각 제조업체들은 페라이트 자석이나 구리 로터와 같은 대안을 검토하고 있으나, 이러한 선택지는 토크 밀도를 저하시키고 열 설계를 복잡하게 만듭니다.
부문별 분석
2025년, 유도 교류 모터는 견고한 구조와 유지보수가 거의 필요 없다는 점 덕분에 매출 점유율 67.23%를 기록하며 교류 모터 시장을 주도했습니다. 이 모터들은 모든 산업 현장에서 가동되는 펌프, 팬, 컨베이어를 지배하고 있습니다. 동기 기술은 생산량은 적지만, 영구 자석 로터가 전 부하 시 최대 4퍼센트 포인트의 효율 향상을 가져오기 때문에 연평균 성장률(CAGR) 3.68%로 발전하고 있습니다. 로봇 제조업체, 공작기계 제조업체, 전기차(EV) OEM 기업들은 현재 자석에 의해 실현되는 민감한 토크 응답과 콤팩트한 프레임 덕분에 동기 구동 장치를 지정하고 있습니다.
정책적 압력도 이러한 전환을 가속화하고 있습니다. 유럽연합(EU)의 IE4 규제와 미국에서 제안되고 있는 IE4 의무화 안은 동기 모터를 채택하는 기업에 이점을 가져다주고 있으며, 전 세계 OEM 업체들은 제품 라인의 통합과 재고 합리화를 추진하고 있습니다. 광물 가공 업체들은 메가와트급 동기 모터를 중전압 실리콘 카바이드 드라이브와 결합함으로써 전기 손실과 개폐 장치의 설치 면적을 줄이고 있습니다(IEC.CH). 라이프사이클 분석에서 kW시(kWh) 절감이 중요시됨에 따라, 향후 10년 동안 교류 모터 시장 규모는 동기식 모터로 더욱 이동할 전망입니다.
1 kV 미만의 저전압 모터는 2025년 매출의 84.23%를 차지했으며, 이는 HVAC, 식품 가공, 포장 분야에서의 보급 현황을 반영합니다. 이러한 장치에 결합된 가변 주파수 드라이브를 통해 소프트 스타트 및 에너지 절약형 속도 제어가 가능해집니다. 반면, 1 kV에서 11 kV에 이르는 중전압 플랫폼은 연평균 성장률(CAGR) 3.89%로 가장 빠르게 성장하고 있습니다. 이는 석유 및 가스·금속 업계의 사업자들이 여러 개의 저전압 피더를 단일 고출력 샤프트로 통합하여 설치당 구리 사용량을 최대 30%까지 줄이고 있기 때문입니다.
현재 효율 관련 규제는 1 kV까지만 적용되고 있으므로, 프로젝트 소유자는 디지털 트윈을 통해 현장 효율을 검증할 수 있는 공급업체를 우대하는 등 독자적인 성능 기준에 대해 협상할 여지가 있습니다. 현재 6.6kV 및 11kV 구동 장치에 채택되고 있는 실리콘 카바이드(SiC) 파워 디바이스는 스위칭 손실을 절반으로 줄여, 더 소형화된 방열판과 캐비닛을 구현할 수 있게 해줍니다. 이러한 공간 및 에너지상의 이점은 중동 및 아시아의 정유시설, LNG, 해수 담수화 메가 프로젝트와 맞물려 중전압 교류 모터 시장을 전략적 성장 분야로 확고히 자리매김하고 있습니다.
지역별 분석
2025년, 아시아태평양은 전 세계 매출의 56.41%를 차지했으며, 그중에서도 중국의 국내 생산 대수가 3억 대를 넘어설 것이 주요 요인이 되었습니다. 한국의 로봇 도입 밀도(근로자 1,000명당 3.8대)가 서보 수요를 공고히 하고 있는 반면, 인도에서는 0.75kW를 초과하는 모터에 대한 IE3 기준 의무화가 섬유·철강 업계 전반에 걸쳐 조기 교체 붐을 주도하고 있습니다. 일본에서는 정밀 기기에 대한 IE5 규격의 급속한 보급으로 고가 대의 가격이 유지되고 있으며, 호주의 광업 부문에서는 운반 및 파쇄에 500kW를 초과하는 구동 장치가 사용되고 있어 지역의 부가가치가 향상되고 있습니다.
북미와 유럽을 합치면 2025년 매출의 약 35%를 차지했습니다. 미국에서는 수자원 부문에 대한 500억 달러 규모의 보조금이 주기의 중반에 접어들어, 2025년부터 2026년에 걸쳐 조달량이 정점에 달할 전망이며, 이에 따라 지자체 하수 처리 시설에서의 IE4 도입이 가속화되고 있습니다. 유럽의 에코디자인 규정 2019/1781에서는 2025년 중반까지 IE4의 전력 소비량을 0.12kW 이하로 억제하는 것이 의무화되었으며, 건축 설비 및 경공업 분야의 업그레이드 일정이 엄격해지고 있습니다. 독일만 해도, 해당국의 기계 수출업체들이 서보 시스템 현대화를 추진하는 가운데 유럽 매출의 28%를 차지하고 있으며, 한편 영국은 건축물의 난방 탈탄소화를 위해 히트펌프용 압축기로의 전환을 추진하고 있습니다.
아프리카는 가장 빠르게 성장하는 지역으로, 이집트, 남아프리카공화국, 나이지리아를 대상으로 한 아프리카개발은행의 250억 달러 규모의 전기화 프로젝트를 배경으로, 2031년까지의 연평균 성장률(CAGR)은 4.22%로 전망됩니다. 남아프리카의 광산에서는 운영비의 40% 이상의 전력 비용을 억제하기 위해 IE3-IE4 규격의 환풍기로의 교체가 진행되고 있으며, 이집트에서 계획 중인 산업 도시에서는 급수 및 HVAC 부하용으로 수만 대의 모터가 필요할 것으로 전망됩니다. 나이지리아의 새로운 철도 회랑은 시멘트, 식품 가공, 섬유 산업의 집적을 촉진하고 있습니다. 중동에서는 해수 담수화 및 지역 냉방 시설로부터 안정적인 수요가 발생하고 있으며, 남미의 성장은 브라질이 주도하고 있습니다. 브라질에서는 현지 제조업체인 WEG사가 5주라는 리드타임을 활용하여 수입품을 능가하는 판매 실적을 올리고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the alternating current motor market size is projected to expand from USD 18.23 billion in 2025 and USD 18.89 billion in 2026 to USD 22.24 billion by 2031, registering a CAGR of 3.32% between 2026 to 2031.
This report is Segmented by Motor Type (Induction AC Motors, and Synchronous AC Motors), Voltage Class (Low Voltage, Medium Voltage, and High Voltage), Power Rating (less Than 1 KW, 1 To 100 KW, and More), Efficiency Class (IE1, IE2, and More), End-User Industry (Oil and Gas, Chemicals, Power Generation, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Alternating Current (AC) Motor Market Trends and Insights
Mandatory Energy-Efficiency Regulations Drive Accelerated Replacement Cycles
IE4 rules are now obligatory for motors above 0.75 kilowatts in the European Union, and IE3 minimums in China, the United States, and India are triggering early retirement of legacy IE1-IE2 fleets. Compliance converges global product lines on super-premium platforms, favoring suppliers with scale manufacturing and harmonized certifications. For end users, a 75-kilowatt IE4 motor running 7,000 hours per year saves close to USD 1,200 in electricity costs, recovering the upfront price delta in under 3 years. Utilities and process industries that spend 60% or more of their operating budgets on motor power are therefore locking in multi-year procurement pipelines. As a result, the alternating current (AC) motor market is witnessing a structural pivot toward higher-efficiency design as the regulatory floor continues to rise.
Rapid Industrial Automation and Robotics Uptake Reshapes Motor Demand
Global robot installations topped 540,000 units in 2024, embedding millions of permanent-magnet servo motors with sub-millisecond positional accuracy. Automotive and electronics assembly lines are shifting from pneumatic cylinders to servo actuation, cutting cycle times by more than 15% and energy draw by up to 50%. Collaborative-robot deployments are scaling fastest, requiring low-inertia frameless motors capable of a 10-millisecond safe-stop response. Warehouse automation adds further pull, with each autonomous mobile robot containing multiple small AC drives. Concentrated adoption in China, South Korea, and Japan ensures that Asia-Pacific remains the volume anchor of the alternating current (AC) motor market.
Copper and Rare-Earth Volatility Compresses Margins and Delays Orders
Copper traded between USD 8,000 and USD 10,500 per metric ton during 2024-2025, eroding the profitability of fixed-price contracts and prompting vendors to shorten quote validity to less than 30 days. Neodymium-iron-boron magnet prices rose 12-18% on tighter Chinese export quotas, raising material cost in permanent-magnet motors by up to USD 120 for a 20-kilowatt unit. In price-sensitive markets, buyers are back-specifying IE3 induction motors to sidestep rare-earth exposure, slowing the premium-efficiency trajectory of the alternating current (AC) motor market. Manufacturers are exploring ferrite-magnet or copper-rotor alternatives, but these options sacrifice torque density and complicate thermal design.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Renewable-Energy Assets Multiplies Auxiliary-Motor Demand
- HVAC/R Build-Out in Commercial Real Estate Sustains Baseline Growth
- High Upfront Cost of Premium-Efficiency Motors Limits Penetration in Capital-Constrained Segments
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Induction AC motors led the alternating current (AC) motor market in 2025 with a 67.23% revenue share, underpinned by their rugged construction and low maintenance needs. They dominate pumps, fans, and conveyors that run across every industrial floor. Synchronous technology, although smaller in volume, is advancing at a 3.68% CAGR because permanent-magnet rotors add up to four percentage points of efficiency at full load. Robot builders, machine-tool makers, and electric-vehicle OEMs now specify synchronous drives for the tight torque response and compact frames that magnets enable.
Policy pressure is amplifying the shift. IE4 rules in the European Union and proposed U.S. mandates for IE4 reward synchronous adopters, prompting global OEMs to harmonize product lines and streamline inventory. Minerals processors are pairing megawatt-class synchronous motors with medium-voltage silicon-carbide drives, trimming electrical losses and switchgear footprints IEC.CH. As life-cycle analyses place a premium on kilowatt-hour savings, the alternating current (AC) motor market size is likely to tilt further toward synchronous formats through the decade.
Low-voltage motors below 1 kV captured 84.23% of 2025 revenue, reflecting their ubiquity in HVAC, food processing, and packaging. Variable-frequency drives coupled to these units allow soft starts and energy-saving speed control. Medium-voltage platforms between 1 kV and 11 kV are, however, the fastest risers at a 3.89% CAGR, as oil, gas, and metals operators consolidate several low-voltage feeders into single high-horsepower shafts, slicing copper mass by as much as 30% per installation.
Efficiency mandates currently stop at 1 kV, giving project owners latitude to negotiate bespoke performance benchmarks that favor vendors able to verify field efficiency through digital twins. Silicon-carbide power devices now featured in 6.6 kV and 11 kV drives cut switching losses by half, enabling smaller heat sinks and cabinets. These space and energy benefits dovetail with refinery, LNG, and desalination megaprojects in the Middle East and Asia, cementing medium-voltage as a strategic growth segment of the alternating current (AC) motor market.
Complete Report Scope:
- By Motor Type
- Induction AC Motors
- Single-Phase
- Poly-Phase
- Synchronous AC Motors
- DC-Excited Rotor
- Permanent-Magnet
- Hysteresis
- Reluctance
- Induction AC Motors
- By Voltage Class
- Low Voltage (Less Than 1 kV)
- Medium Voltage (1 to 11 kV)
- High Voltage (More Than 11 kV)
- By Power Rating
- Less Than 1 kW
- 1 to 100 kW
- 100 to 500 kW
- Greater Than 500 kW
- By Efficiency Class
- IE1 (Standard)
- IE2 (High)
- IE3 (Premium)
- IE4 (Super-Premium)
- IE5 (Ultra-Premium)
- By End-User Industry
- Oil and Gas
- Chemicals and Petrochemicals
- Power Generation
- Water and Wastewater
- Metals and Mining
- Food and Beverage
- Discrete Manufacturing
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific produced 56.41% of global revenue in 2025, headlined by China's domestic output of more than 300 million units. Robot deployment density, 3.8 units per 1,000 workers in South Korea, locks in servo demand, while India's IE3 mandate for motors above 0.75 kW is driving an early replacement wave across textiles and steel. Japan commands premium pricing thanks to the rapid uptake of IE5 frames in precision equipment, and Australia's mining sector relies on >500 kW drives for haulage and crushing, boosting regional value intensity.
North America and Europe together delivered about 35% of 2025 revenue. The United States is mid-cycle on USD 50 billion in water-sector grants, with procurements peaking in 2025-2026, advancing the adoption of IE4 in municipal treatment works. Europe's Ecodesign Regulation 2019/1781 already requires IE4 to be down to 0.12 kW by mid-2025, tightening upgrade timetables for building services and light manufacturing. Germany alone accounted for 28% of European sales as its machinery exporters modernize servo footprints, while the United Kingdom is pivoting toward heat-pump compressors to decarbonize building heating.
Africa is the fastest-growing region, charting a 4.22% CAGR to 2031 on the back of USD 25 billion in African Development Bank electrification projects targeting Egypt, South Africa, and Nigeria. South African mines are retrofitting IE3-IE4 ventilators to curb power costs that exceed 40% of operating expense, and Egypt's planned industrial cities will need tens of thousands of motors for water and HVAC loads. Nigeria's new rail corridor is stimulating cement, food-processing, and textiles clusters. The Middle East adds steady volume from desalination and district-cooling, while South America's growth is anchored by Brazil, where local producer WEG leverages five-week lead times to outsell imports.
- ABB Ltd.
- Siemens AG
- WEG Equipamentos Eletricos S.A.
- Nidec Corporation
- Regal Rexnord Corporation
- Johnson Electric Holdings Limited
- Yaskawa Electric Corporation
- Rockwell Automation, Inc.
- Franklin Electric Co., Inc.
- Bosch Rexroth AG
- Kirloskar Electric Company Ltd.
- SEVA-tec GmbH
- Toshiba Corporation
- Mitsubishi Electric Corporation
- TECO Electric and Machinery Co., Ltd.
- Leroy-Somer Holding (Nidec)
- ATB Austria Antriebstechnik AG
- Getriebebau NORD GmbH and Co. KG
- Oriental Motor Co., Ltd.
- Brook Crompton UK Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Mandatory Energy-Efficiency Regulations (IE3/IE4)
- 4.2.2 Rapid Industrial Automation and Robotics Uptake
- 4.2.3 Expansion of Renewable-Energy Assets (Wind, Solar)
- 4.2.4 HVAC/R Build-Out in Commercial Real Estate
- 4.2.5 Rise of Axial-Flux PM AC Motors in E-Mobility
- 4.2.6 AI-Enabled Predictive-Maintenance Ecosystems
- 4.3 Market Restraints
- 4.3.1 Volatile Copper and Rare-Earth Metal Prices
- 4.3.2 High Upfront Cost of Premium-Efficiency Motors
- 4.3.3 Power-Electronics (IGBT) Supply-Chain Bottlenecks
- 4.3.4 End-of-Life Recycling and Take-Back Compliance
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value / Supply-Chain Analysis
- 4.6 Regulatory Landscape and Standards
- 4.7 Technological Outlook (Edge and AI Analytics)
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Degree of Competition
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Motor Type
- 5.1.1 Induction AC Motors
- 5.1.1.1 Single-Phase
- 5.1.1.2 Poly-Phase
- 5.1.2 Synchronous AC Motors
- 5.1.2.1 DC-Excited Rotor
- 5.1.2.2 Permanent-Magnet
- 5.1.2.3 Hysteresis
- 5.1.2.4 Reluctance
- 5.1.1 Induction AC Motors
- 5.2 By Voltage Class
- 5.2.1 Low Voltage (Less Than 1 kV)
- 5.2.2 Medium Voltage (1 to 11 kV)
- 5.2.3 High Voltage (More Than 11 kV)
- 5.3 By Power Rating
- 5.3.1 Less Than 1 kW
- 5.3.2 1 to 100 kW
- 5.3.3 100 to 500 kW
- 5.3.4 Greater Than 500 kW
- 5.4 By Efficiency Class
- 5.4.1 IE1 (Standard)
- 5.4.2 IE2 (High)
- 5.4.3 IE3 (Premium)
- 5.4.4 IE4 (Super-Premium)
- 5.4.5 IE5 (Ultra-Premium)
- 5.5 By End-User Industry
- 5.5.1 Oil and Gas
- 5.5.2 Chemicals and Petrochemicals
- 5.5.3 Power Generation
- 5.5.4 Water and Wastewater
- 5.5.5 Metals and Mining
- 5.5.6 Food and Beverage
- 5.5.7 Discrete Manufacturing
- 5.5.8 Other End-User Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Russia
- 5.6.3.5 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Egypt
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Vendor Ranking Analysis
- 6.5 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.5.1 ABB Ltd.
- 6.5.2 Siemens AG
- 6.5.3 WEG Equipamentos Eletricos S.A.
- 6.5.4 Nidec Corporation
- 6.5.5 Regal Rexnord Corporation
- 6.5.6 Johnson Electric Holdings Limited
- 6.5.7 Yaskawa Electric Corporation
- 6.5.8 Rockwell Automation, Inc.
- 6.5.9 Franklin Electric Co., Inc.
- 6.5.10 Bosch Rexroth AG
- 6.5.11 Kirloskar Electric Company Ltd.
- 6.5.12 SEVA-tec GmbH
- 6.5.13 Toshiba Corporation
- 6.5.14 Mitsubishi Electric Corporation
- 6.5.15 TECO Electric and Machinery Co., Ltd.
- 6.5.16 Leroy-Somer Holding (Nidec)
- 6.5.17 ATB Austria Antriebstechnik AG
- 6.5.18 Getriebebau NORD GmbH and Co. KG
- 6.5.19 Oriental Motor Co., Ltd.
- 6.5.20 Brook Crompton UK Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment