

|
시장보고서
상품코드
2125297
서보 모터 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Servo Motor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 서보 모터 시장 규모는 2025년 145억 7,000만 달러로 평가되었고, 2026년에는 153억 8,000만 달러로 추정되고, 2031년까지 201억 4,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 5.53%로 성장할 전망입니다.
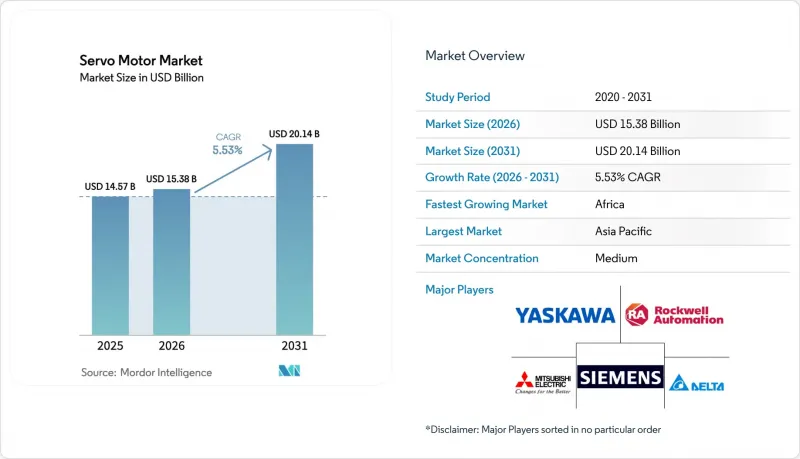
본 보고서는 모터 유형별(AC 서보 모터 및 DC 서보 모터), 축 구성별(단축 및 다축), 정격 출력별(750W 이하, 750W-2kW, 2kW 초과), 통신 인터페이스별(아날로그/PWM, 디지털 필드버스), 최종 사용자 산업별(석유 및 가스, 화학제품 및 석유화학제품, 기타), 지역별(북미, 유럽, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 서보 모터 시장 동향 및 인사이트
국제적인 에너지 효율 기준의 도입
IEC 61800-9-2:2025에서는 IE4 및 IE5 벤치마크가 규정되어 있으며, 공급업체는 구동 시스템의 손실을 줄이기 위해 권선, 자석, 펌웨어의 재설계를 불가피하게 수행해야 합니다. EU 회원국들은 2025년 중반까지 이 규격을 공공 조달 규정에 반영할 전망이며, 이로 인해 지방자치단체의 상수도 네트워크에서 대규모 개보수가 촉진될 것으로 예측됩니다. 일본과 한국에서는 세액 공제를 기준 준수와 연계함으로써 자동차 도장 공장 및 반도체 제조 공장에서의 도입이 가속화되고 있습니다. 또한, 이 규정에서는 전부하 효율 곡선의 공개가 의무화되어 있어, 경쟁의 초점이 정가에서 수명 주기 운영 비용으로 이동하고 있습니다. 북미는 뒤처져 있지만, 미국 에너지부가 2027년 규정 제정 시 이 규격을 참조할 예정이므로, 따라잡을 가능성이 높다고 여겨집니다.
산업 전반에 걸친 스마트하고 유연한 자동화 추진
각 제조업체는 고정식 트랜스퍼 라인을 폐지하고, 서보 구동 갠트리와 확정성 이더넷을 통해 연결된 코봇을 갖춘 재구성 가능한 워크셀로 전환하고 있습니다. 2023년 말 기준, 가동 중인 산업용 로봇은 428만 대에 달했습니다. 2024년, 독일 기계 제조업체의 EtherCAT 보급률은 62%에 달했으며, 분산 클럭형 모션 네트워크로의 전환이 두드러지고 있습니다. 드라이브에 탑재된 엣지 AI 칩은 최대 30일 후까지 베어링 고장을 예측하여, 파일럿 라인에서 발생하는 예기치 못한 정지를 40% 줄이고 있습니다. 따라서 서보 모터 시장은 기계적 정밀도뿐만 아니라 데이터 기반의 가동률 향상에서도 혜택을 보고 있습니다.
저비용 스테퍼 모터 및 BLDC 모터 대체품의 보급
오픈 루프 스테퍼 모터와 센서식 BLDC 모터는 서보 시스템에 비해 40-60% 저렴하며, 이러한 가격 차이는 아프리카나 남미 등 가격에 민감한 구매자들에게 매력적입니다. 중국 공급업체들은 2024년에 1,200만 대 이상의 스테퍼 모터를 출하했으며, 주요 용도는 3D 프린터, CNC 라우터, 섬유 기계의 유지보수용입니다. 텍사스 기기(Texas Instruments)의 5달러짜리 인코더 IC는 BLDC 모터에 폐쇄 루프 피드백을 추가함으로써 두 제품의 경계를 모호하게 만들고 있습니다. 그 결과, 가격 탄력성이 높은 시장에서는 서보 모터 도입이 최대 3년 연기되고 있습니다.
부문 분석
서보 모터 시장에서 브러쉬리스 DC 모터의 점유율이 가장 빠르게 확대되고 있으며, 의료, 농업, 이동형 로봇 OEM 업체들이 컴팩트한 폼 팩터를 우선시함에 따라 연평균 성장률(CAGR) 6.47%로 성장하고 있습니다. 한편, AC 모터는 2025년 기준 매출 점유율 71.47%를 차지하며 여전히 시장을 독점했는데, 이는 3상 전원을 사용하는 중공업 공정에서 AC 모터가 확고한 입지를 차지하고 있음을 반영합니다. 배터리 구동식 수술용 로봇이나 외골격 로봇에서는 프레임리스 BLDC 유닛이 선호되고 있습니다. 한편, 실리콘 카바이드 인버터를 통해 기존 유도 모터 플랫폼과의 효율 차이가 좁혀지고 있습니다.
AC 설계는 회생 에너지 회수 측면에서 여전히 우위를 유지하고 있으며, 이는 수직축 CNC 및 하이베이 크레인 용도에서 결정적인 특징이 되고 있습니다. 야스카와 전기(Yaskawa Electric)와 같은 공급업체들은 23비트 엔코더와 실리콘 카바이드 구동 장치를 차세대 AC 플랫폼에 통합하고, 평균 고장 간격(MTBF)을 10만 시간으로 연장함으로써 서보 모터 시장에서의 입지를 강화하고 있습니다.
2025년에도 단일 축 시스템의 도입 비율은 여전히 63.41%를 차지했으며, 주로 컨베이어의 인덱스 동작이나 밸브 작동에 사용되고 있습니다. 그러나 6개의 관절을 협동시켜야 하는 코봇의 보급에 힘입어 다축 아키텍처는 연평균 성장률(CAGR) 7.32%로 확대되고 있습니다. EtherCAT 및 PROFINET 백본을 통해 축 간 마이크로초 미만의 동기화가 실현되어, 케이지가 필요 없는 유연한 동작이 가능해졌습니다.
자동차 용접 라인에서는 고정식 스폿 건에서 패널의 변형에 실시간으로 적응하는 다축 갠트리로의 전환이 진행되고 있습니다. 지멘스는 비전 가이드와 다축 드라이브를 통합한 턴키 패키지를 출시하여 프로그래밍 작업을 60% 줄이는 동시에 서보 모터 시장으로의 침투를 더욱 심화하고 있습니다.
지역별 분석
아시아태평양은 스마트폰 조립 부문에서 중국의 압도적인 우위와 한국의 440억 달러 규모의 반도체 설비 투자(CAPEX) 열풍에 힘입어 2025년 매출의 43.74%를 차지했습니다. 인도에서는 ‘생산 연계 인센티브(PLI)’ 제도에 따른 정부 보조금으로 자동화 비용의 25%가 환급되므로, 자동차 및 제약 산업의 생산 라인에서 서보 도입이 가속화되고 있습니다.
아프리카는 현재 서보 모터 시장에서 극히 일부에 불과하지만, 남아프리카공화국의 전기차(EV) 프로그램, 나이지리아의 식품 가공 설비 현대화, 케냐의 섬유 제품 수출에 힘입어 2031년까지 연평균 성장률(CAGR) 8.13%로 확대될 것으로 예측됩니다. 그러나 전력망의 신뢰성 문제와 유지보수 기술 부족으로 인해 저비용 스테퍼 모터가 여전히 유력한 선택지로 남아 있어 성장세가 주춤하고 있습니다.
북미와 유럽은 여전히 성숙한 시장이지만, 의료기기 및 항공우주 부문에서는 두 자릿수 성장을 보이는 지역도 있습니다. 이러한 부문에서는 IP69K 규격을 충족하는 스테인리스 모터나 DO-178 인증을 획득한 소프트웨어 스택에 대해, 가격이 비싸더라도 기꺼이 지불할 의향이 있습니다. 남미는 거시경제의 변동으로 인해 수입 장비 비용이 상승하면서 성장세가 뒤처지고 있지만, 브라질의 자동차 부문의 경우 차입 비용이 10% 미만으로 떨어지면 다시 성장세가 가속화될 가능성이 있습니다. 중동에서는 사우디아라비아의 ‘비전 2030’을 선두로, 새로운 산업 단지에서 서보 구동식 CNC 및 적층 가공 셀이 선별적으로 도입되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the servo motor market size is expected to increase from USD 14.57 billion in 2025 to USD 15.38 billion in 2026 and reach USD 20.14 billion by 2031, growing at a CAGR of 5.53% over 2026-2031.
This report is Segmented by Motor Type (AC Servo Motor, and DC Servo Motor), Axis Configuration (Single-Axis, and Multi-Axis), Power Rating (<=750 W, 750 W - 2 KW, and >2 KW), Communication Interface (Analog/PWM, and Digital Fieldbus), End-User Industry (Oil and Gas, Chemical and Petrochemical, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Servo Motor Market Trends and Insights
Adoption Of International Energy-Efficiency Standards
IEC 61800-9-2:2025 established IE4 and IE5 benchmarks, forcing vendors to redesign windings, magnets, and firmware to lower drivetrain losses. EU member states are expected to embed the standard in public procurement rules by mid-2025, triggering large-scale retrofits in municipal water networks. Japan and South Korea linked tax credits to compliance, accelerating adoption across automotive paint shops and semiconductor fabs. The rule also mandates the disclosure of full-load efficiency curves, shifting competition from sticker price to life-cycle operating costs. North America is lagging but is likely to catch up as the U.S. Department of Energy references the standard in its 2027 rulemaking.
Industry-Wide Drive Toward Smart And Flexible Automation
Manufacturers are abandoning hard-tooled transfer lines for reconfigurable work-cells equipped with servo-driven gantries and cobots connected over deterministic Ethernet. Operational industrial robots reached 4.28 million units by the end of 2023. EtherCAT penetration among German machine builders reached 62% in 2024, underscoring the shift toward distributed-clock motion networks. Edge AI chips mounted on drives are predicting bearing failures up to 30 days in advance, cutting unplanned stoppages by 40% in pilot lines. The servo motor market, therefore, benefits not only from mechanical precision but from data-driven uptime improvements.
Proliferation Of Low-Cost Stepper And BLDC Alternatives
Open-loop stepper and sensor-based BLDC motors cost 40-60% less than servo systems, a gap that appeals to price-sensitive buyers in Africa and South America. Chinese suppliers shipped over 12 million steppers in 2024, primarily for use in servicing 3D printers, CNC routers, and textile machinery. Texas Instruments' USD 5 encoder IC blurs the line by adding closed-loop feedback to BLDC motors. As a result, servo adoption is deferred in cost-elastic markets by up to three years.
Other drivers and restraints analyzed in the detailed report include:
- Rising Deployment Of Industrial And Collaborative Robots
- Integration Of Servo Drives With Edge AI Chips For On-Motor Analytics
- Rare-Earth Magnet Supply Risks Amid Geopolitical Tensions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Brushless DC motors accounted for the fastest-growing share within the servo motor market, advancing at a 6.47% CAGR as medical, agricultural, and mobile-robot OEMs prioritize compact form factors. AC counterparts still dominated with 71.47% revenue share in 2025, reflecting their hold on heavy industrial processes that tap three-phase grids. Battery-powered surgical robots and exoskeletons favor frameless BLDC units, while silicon-carbide inverters narrow the efficiency gap to legacy induction platforms.
AC designs nonetheless retain an advantage in regenerative energy recovery, a decisive feature in vertical-axis CNC and high-bay crane applications. Vendors such as Yaskawa integrated 23-bit encoders and silicon-carbide drives into next-gen AC platforms, extending mean time between failures to 100,000 hours and reinforcing their presence in the servo motor market.
Single-axis systems still accounted for 63.41% of installations in 2025, primarily used for conveyor indexing and valve actuation tasks. Yet, multi-axis architectures are expanding at a 7.32% CAGR, propelled by cobots that require six coordinated joints. EtherCAT and PROFINET backbones deliver sub-microsecond synchronization across axes, enabling compliant motion without the need for cages.
Automotive welding lines are transitioning from fixed spot guns to multi-axis gantries that adapt in real-time to panel distortion. Siemens launched turnkey packages integrating vision guidance with multi-axis drives, reducing programming labor by 60% and deepening penetration of the servo motor market.
Complete Report Scope:
- By Motor Type
- AC Servo Motor
- DC Servo Motor
- By Axis Configuration
- Single-Axis
- Multi-Axis
- By Power Rating
- <750 W
- 750 W - 2 kW
- >2 kW
- By Communication Interface
- Analog / PWM
- Digital Fieldbus (CANopen, EtherCAT, PROFINET)
- By End-User Industry
- Oil and Gas
- Chemical and Petrochemical
- Power Generation
- Water and Wastewater
- Metal and Mining
- Food and Beverage
- Discrete Industries
- Automotive
- Electronics and Semiconductor
- Packaging
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- North America
Geography Analysis
Asia Pacific generated 43.74% of 2025 revenue, anchored by China's dominance in smartphone assembly and South Korea's USD 44 billion semiconductor CAPEX wave. Government subsidies in India under the Production-Linked Incentive scheme reimburse 25% of automation spend, accelerating servo adoption across automotive and pharma lines.[3]
Africa, although only a small portion of the current servo motor market, is forecast to expand at an 8.13% CAGR through 2031, driven by South Africa's EV program, Nigerian food-processing upgrades, and Kenyan textile exports. Limited grid reliability and servicing expertise, however, keep low-cost stepper alternatives in contention, tempering upside.
North America and Europe remain mature but show pockets of double-digit growth in medical devices and aerospace, segments willing to pay premiums for IP69K stainless motors or DO-178-certified software stacks. South America lags as macro volatility lifts imported-equipment costs, although Brazil's automotive sector could reaccelerate once borrowing costs retreat below 10%. The Middle East, led by Saudi Arabia's Vision 2030, is selectively installing servo-driven CNC and additive manufacturing cells in new industrial zones.
- Yaskawa Electric Corporation
- Mitsubishi Electric Corp.
- Siemens AG
- Rockwell Automation Inc.
- Delta Electronics Inc.
- ABB Ltd.
- FANUC Corp.
- Schneider Electric SE
- Bosch Rexroth AG
- Kollmorgen Corporation
- Omron Corporation
- Parker Hannifin Corp.
- Nidec Corporation
- Oriental Motor Co. Ltd.
- Lenze SE
- Panasonic Industry Co.
- Toshiba Infrastructure Systems
- Estun Automation Co. Ltd.
- Maxon Group
- Sanyo Denki (SANMOTION)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry ValueChain Analysis
- 4.3 Market Drivers
- 4.3.1 Adoption of International Energy-Efficiency Standards
- 4.3.2 Industry-Wide Drive Toward Smart and Flexible Automation
- 4.3.3 Rising Deployment of Industrial and Collaborative Robots
- 4.3.4 Integration of Servo Drives with Edge AI Chips for On-motor Analytics
- 4.3.5 Miniaturized Servo Solutions for Medical Exoskeletons
- 4.3.6 High-Torque Servo Use in Autonomous Agricultural Equipment
- 4.4 Market Restraints
- 4.4.1 Proliferation of Low-Cost Stepper and BLDC Alternatives
- 4.4.2 High Upfront Capital Expenditure for Multi-Axis Servo Systems
- 4.4.3 Rare-Earth Magnet Supply Risks Amid Geopolitical Tensions
- 4.4.4 Cyber-Security Concerns in Networked Motion Control
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Motor Type
- 5.1.1 AC Servo Motor
- 5.1.2 DC Servo Motor
- 5.2 By Axis Configuration
- 5.2.1 Single-Axis
- 5.2.2 Multi-Axis
- 5.3 By Power Rating
- 5.3.1 <750 W
- 5.3.2 750 W - 2 kW
- 5.3.3 >2 kW
- 5.4 By Communication Interface
- 5.4.1 Analog / PWM
- 5.4.2 Digital Fieldbus (CANopen, EtherCAT, PROFINET)
- 5.5 By End-User Industry
- 5.5.1 Oil and Gas
- 5.5.2 Chemical and Petrochemical
- 5.5.3 Power Generation
- 5.5.4 Water and Wastewater
- 5.5.5 Metal and Mining
- 5.5.6 Food and Beverage
- 5.5.7 Discrete Industries
- 5.5.7.1 Automotive
- 5.5.7.2 Electronics and Semiconductor
- 5.5.7.3 Packaging
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Australia
- 5.6.4.6 New Zealand
- 5.6.4.7 Rest of Asia Pacific
- 5.6.5 Middle East
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Kenya
- 5.6.6.4 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Yaskawa Electric Corporation
- 6.4.2 Mitsubishi Electric Corp.
- 6.4.3 Siemens AG
- 6.4.4 Rockwell Automation Inc.
- 6.4.5 Delta Electronics Inc.
- 6.4.6 ABB Ltd.
- 6.4.7 FANUC Corp.
- 6.4.8 Schneider Electric SE
- 6.4.9 Bosch Rexroth AG
- 6.4.10 Kollmorgen Corporation
- 6.4.11 Omron Corporation
- 6.4.12 Parker Hannifin Corp.
- 6.4.13 Nidec Corporation
- 6.4.14 Oriental Motor Co. Ltd.
- 6.4.15 Lenze SE
- 6.4.16 Panasonic Industry Co.
- 6.4.17 Toshiba Infrastructure Systems
- 6.4.18 Estun Automation Co. Ltd.
- 6.4.19 Maxon Group
- 6.4.20 Sanyo Denki (SANMOTION)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


