|
시장보고서
상품코드
2125361
임상시험 공급 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Clinical Trial Supply - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
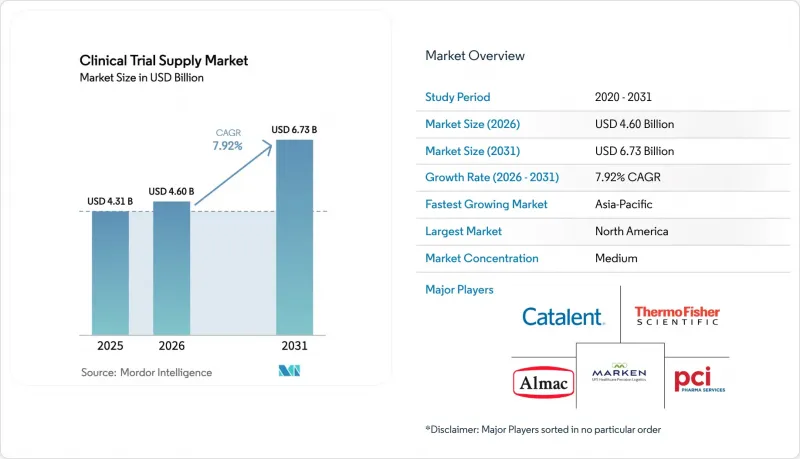
에 의하면, 임상시험 공급 시장 규모는 2025년에 43억 1,000만 달러로 평가되었고, 2026년 46억 달러에서 2031년까지 67억 3,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 7.92%를 나타낼 전망입니다.
본 보고서는 서비스별(물류·유통, 보관·저장, 포장, 라벨링·블라인드화, 제조 등), 단계별(생체이용률/생물학적 동등성 등), 치료 분야별(심혈관 질환 등), 최종 사용자별(제약 회사 등), 지역별(북미 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 임상시험 공급 시장 동향 및 인사이트
3상 다국가의 임상시험 건수 증가
2025년 1월에 발표된 전자 공통 기술 문서(eCTD) 제출에 관한 FDA의 최종 지침에 따라 중복되는 행정 절차가 줄어들고 심사 주기가 약 15% 단축되었습니다. 현재 각 스폰서사는 지역별 거점에서 포장 및 라벨 부착을 통합하여 언어 및 아트워크의 다양한 요구 사항을 충족하는 동시에, 클라우드 기반의 무작위 배정 및 임상시험 용품 관리 플랫폼을 통해 종단간 재고 가시성을 유지하고 있습니다. 종양학 및 희귀질환 프로그램은 20개국 이상에 걸쳐 진행되는 경우가 많아, 국경을 초월한 대조약 조달에 능숙한 물류 파트너에 대한 수요가 증가하고 있습니다. 2025년 초부터 운영이 시작된 EMA(유럽의약품청)의 임상시험 정보 시스템 덕분에 단 한 건의 신청으로 EU 회원국 27개국 전역을 커버할 수 있게 되어, 규모 확대와 품질 프로세스 통합에 대한 수요가 더욱 높아지고 있습니다. 이러한 변화로 인해 출하량이 증가하고, 보관 거점에서의 처리 건수도 늘어나면서 임상시험 공급 시장 전체에서 수익 기회가 확대되고 있습니다.
분산형·환자 직배송형 물류 모델의 확대
2024년 5월 FDA 지침에서는 엄격한 위험 관리 하에 임상시험용 의약품의 자택 배송이 공식 승인됨에 따라, 환자 직접 배송 모델의 도입이 가속화되고 있습니다. 스폰서의 보고에 따르면, 이동 부담이 경감되면 피험자 등록이 30% 빨라지고, 스크리닝 불합격률이 25% 감소하여, 결과적으로 신청 시기 앞당김과 상품화 가속화로 이어지고 있습니다. 현재 택배 업체들은 GPS 추적 및 전자 배송 증명을 갖춘 상온·냉장·냉동 배송 경로를 제공하고 있으며, 블록체인 기반 로그 기록을 통해 21 CFR Part 11 및 EU Annex 11을 준수하는 변조 불가능한 감사 추적이 보장되고 있습니다. 이러한 도입이 가장 활발한 분야는 재택 투여에 적합한 치료법이 사용되는 만성 심혈관 질환, 호흡기 질환, 중추신경계 임상시험입니다. 그 결과, 라스트 마일 분야의 전문 지식은 임상시험 공급 시장에서 프리미엄 서비스 라인으로 자리 잡고 있습니다.
국경을 초월한 규제 차이의 확대가 규정 준수 비용을 상승시키고 있습니다.
중국의 NMPA는 2024년 6월, 해외 포장 공장에 대한 승인 전 감사를 시작했으며, 이로 인해 임상시험 시작 일정에 8-12주 정도의 지연이 발생했습니다. 브라질의 ANVISA도 2025년 3월에 이에 발맞추어 현지에서 조제된 대조군 약물의 사용을 의무화하는 규정을 도입함에 따라, 스폰서는 이중 공급망을 운영할 수밖에 없게 되었습니다. 2025년에 다수의 스폰서를 대상으로 실시된 조사에 따르면, 15개국을 대상으로 한 3상 임상시험의 규제 준수 비용은 2022년 이후 19% 상승하여 이익률을 압박하고 프로젝트 일정을 촉박하게 만들고 있습니다. 다양한 라벨 사양과 품질 관리 시험을 유지하는 것은 임상시험 공급망 시장 전체의 자원을 소모시키고 있습니다.
부문 분석
제조 부문은 절대액으로는 물류 부문보다 규모가 작지만, 2031년까지 연평균 성장률(CAGR)이 9.32%로 임상시험 용품 시장 전체를 상회하는 성장이 예상됩니다. 이는 충전 및 마무리, 동결 건조, 대조약 조달에 있어 위탁 개발·제조 기관(CDMO)에 대한 의존도가 높아지고 있음을 반영합니다. 2025년에는 물류·유통 부문이 매출의 29.65%를 차지했으며, 전 세계 각 거점 간 임상시험용 의약품을 운송하는 데 있어 이 부문의 기반적인 역할이 부각되었습니다. 포장, 라벨 부착, 맹검화는 특히 이중 맹검 심혈관계·중추신경계(CNS) 임상시험에서 여전히 필수적이며, 자동화를 통해 출하 주기의 소요 시간이 단축되고 있습니다. 규제 당국이 안정성 관련 의무를 확대함에 따라 보관·보존 분야는 전반적인 성장 추세를 유지하고 있습니다. 공급망 수요 예측 서비스는 과잉 재고를 줄임으로써 새로운 틈새 시장을 개척하고 있으며, 2025년 유럽의 사례 연구에서는 재고가 22% 감소한 것으로 보고되어 AI가 차별화 요인으로 주목받고 있습니다.
대조약 조달의 경우, 특히 라틴아메리카에서 규제 당국이 참조 배치를 현지 제제와 일치시킬 것을 요구하게 됨에 따라 프리미엄 가격 책정이 예상됩니다. 세포 및 유전자 치료의 부상으로 인해 극저온 충전·마무리·주입 센터 인근에서의 적시(JIT) 포장 수요가 가속화되고 있습니다. GMP에 더해 ISO 13485 인증을 취득한 공급업체는 의약품 및 의료기기 조합 시험을 지원할 때 우위를 점하며, 임상시험 공급 시장에서의 영향력을 확대되고 있습니다.
3상 임상시험은 대규모 환자 코호트와 장기간의 시험 기간으로 인해 2025년 시장 가치의 41.24%를 차지했고, 적응형 강화 전략을 통해 개발 기간이 단축됨에 따라, 제2상 임상시험은 2031년까지 연평균 성장률(CAGR) 10.72%를 기록할 전망이며, 각 상 중에서 가장 높은 성장률을 보일 것으로 예측됩니다. FDA의 ‘프로젝트 옵티머스(Project Optimus)’에서는 종양학 분야의 제2상 임상시험에서 여러 용량에 대한 검토가 의무화되어 있으며, 이로 인해 SKU 수가 두 배로 증가함에 따라 유연한 보관 시설이 요구되고 있습니다. 생체이용률 및 생물학적 동등성 시험은 틈새 시장이지만 안정적인 시장을 유지하고 있으며, 제네릭 의약품 진출기업을 뒷받침하고 있습니다. 1상 임상시험의 규모가 소규모에 그치는 이유는 피험자 코호트의 규모가 제한적이고, 현장에서 제조가 이루어지기 때문입니다. 시판 후 안전성에 초점을 맞춘 4상 임상시험은 점차 확대되고 있으며, 속도는 완만하지만 지속적인 수요가 예상됩니다.
적응형 설계의 경우, 시험 도중에 시험군 간 약물 전환이 필요한 경우가 많으며, 이에 대응하기 위해서는 임상시험 기관의 재고 상황을 실시간으로 파악할 수 있는 공급업체가 가장 적합합니다. 그 결과, 세심한 추적 관리와 신속한 재공급을 제공하는 물류 파트너가 새로운 제2상 임상시험 계약을 수주하며, 임상시험 공급 시장에서 점유율을 확대되고 있습니다.
지역별 분석
북미는 2025년 매출의 35.77%를 차지한 것으로 평가되었고, 그 기반이 되는 것은 밀집된 임상시험 시설 네트워크, 성숙한 물류 거점, 그리고 암 및 희귀질환 환자 대상 직접 투여 파일럿 임상시험을 가속화하는 FDA의 선구적인 분산형 임상시험 지침입니다. 캐나다와 멕시코는 니어쇼어링의 혜택을 받고 있으며, 2025년까지 미국 후원사의 40%가 관세 리스크를 상쇄하기 위해 일부 포장 공정을 멕시코로 이전했습니다. GMP 포장 및 품질 보증 분야의 인력 부족은 특히 중대서양 연안 지역 및 중서부 지역의 거점에서 비용 증가와 공정 지연을 초래하고 있으며, 이는 자동화에 대한 투자를 촉진하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 9.44%를 나타낼 것으로 예측되며, 지역별로는 가장 빠른 성장세를 보일 것으로 전망됩니다. 중국의 조건부 승인 제도와 인도의 GMP 인증 시설 확대로 인해 후기 임상시험이 동아시아로 이동하고 있습니다. 일본은 2025년에 eCTD 규정을 ICH M8에 부합하도록 조정하여 원활한 세계 신청이 가능하게 했습니다. 한국과 호주는 공동 자금 지원 인센티브를 통해 심혈관 및 대사 질환 임상시험을 유치하고 있습니다. 그럼에도 불구하고 동남아시아의 콜드체인 미비로 인해 온도 이탈률은 여전히 높은 수준을 유지하고 있습니다. 2024년 조사에서는 출하 물량의 11%가 온도 제한을 초과한 것으로 나타났습니다.
유럽은 EMA(유럽의약품청)의 집중 신청 시스템을 활용하여 다국간 임상시험을 효율화하고 있으며, 대규모 심혈관·호흡기 임상시험의 거점으로서의 지위를 유지하고 있습니다. 스페인과 이탈리아는 환자 1인당 비용이 낮아 시장 점유율을 확대하고 있는 반면, 독일, 프랑스, 영국은 복잡한 종양학 프로토콜 분야에서 주도적인 위치를 유지하고 있습니다. 중동에서는 두바이와 리야드에 온도 관리가 가능한 허브를 건설하며, 걸프 지역을 북미 진출의 교두보로 삼고 있습니다. 남미의 기여도는 미미하지만, 브라질과 아르헨티나는 유전적 다양성이 풍부한 피험자 집단과 비용 면에서의 우위를 갖추고 있어, ANVISA의 2025년 규정에 따른 대조군 확보의 어려움에도 불구하고 대규모 3상 심혈관 프로그램에게 매력적인 지역으로 부상하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the clinical trial supply market size was valued at USD 4.31 billion in 2025 and is estimated to grow from USD 4.60 billion in 2026 to reach USD 6.73 billion by 2031, at a CAGR of 7.92% during the forecast period (2026-2031).
This report is Segmented by Service (Logistics & Distribution, Storage & Retention, Packaging, Labelling & Blinding, Manufacturing, and More), Phase (Bioavailability / Bioequivalence, and More), Therapeutic Area (Cardiovascular Diseases, and More), End User (Pharmaceutical Companies, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Clinical Trial Supply Market Trends and Insights
Increasing Volume of Phase III Multicountry Trials
Final FDA guidance on electronic common technical document (eCTD) submissions, issued in January 2025, has cut duplicate paperwork and shortened review cycles by roughly 15%. Sponsors now consolidate packaging and labeling in regional hubs to manage divergent language and artwork needs while still keeping end-to-end inventory visibility through cloud-based randomization and trial supply management platforms. Oncology and rare-disease programs frequently span 20-plus countries, pushing demand for logistics partners skilled at cross-border comparator sourcing. The EMA's Clinical Trials Information System, operational since early 2025, lets a single application cover all 27 EU member states, further amplifying the need for scale and harmonized quality processes. These shifts enlarge shipment volumes, increase depot touchpoints, and elevate revenue opportunities across the clinical trial supply market.
Expansion of Decentralized & Direct-To-Patient Logistics Models
May 2024 FDA guidance formally endorsed home delivery of investigational products under rigorous risk controls, accelerating deployment of direct-to-patient models. Sponsors report 30% faster enrollment and 25% lower screen-failure rates when travel burdens drop, leading to earlier submissions and faster commercialization. Couriers now offer ambient, refrigerated, and frozen lanes with GPS tracking and electronic proof of delivery, while blockchain logs ensure immutable audit trails compliant with 21 CFR Part 11 and EU Annex 11. Adoption has been strongest in chronic cardiovascular, respiratory, and central-nervous-system trials whose treatments lend themselves to home administration. As a result, last-mile expertise is becoming a premium service line within the clinical trial supply market.
Rising Cross-Border Regulatory Divergence Inflating Compliance Costs
China's NMPA began pre-approval audits of overseas packaging plants in June 2024, adding 8-12 weeks to study start-up timelines. Brazil's ANVISA followed in March 2025 with rules demanding local-formulation comparators, forcing sponsors to run duplicate supply chains. A 2025 multi-sponsor survey found regulatory compliance costs for a 15-country Phase III trial had climbed 19% since 2022, eroding margins and stretching project calendars. Maintaining multiple labeling versions and quality-control tests drains resources across the clinical trial supply market.
Other drivers and restraints analyzed in the detailed report include:
- Growth in Temperature-Sensitive Biologics & ATMP Pipelines
- AI-Driven Demand Forecasting Reducing Overage & Waste
- Persistent Temperature-Excursion Losses in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Manufacturing, while smaller in absolute value than logistics, is projected to outpace the overall clinical trial supply market with a 9.32% CAGR through 2031, reflecting deeper reliance on contract development and manufacturing organizations for fill-finish, lyophilization, and comparator procurement. In 2025 logistics and distribution retained 29.65% of revenue, underscoring the sector's foundational role in moving investigational medicinal products between global nodes. Packaging, labeling, and blinding remain indispensable, particularly for double-blind cardiovascular and CNS studies, and automation is reducing release-cycle times. Storage and retention track overall growth as regulators stretch stability obligations. Supply-chain forecasting services are carving a new niche by cutting overage; a 2025 European case study logged a 22% inventory reduction, spotlighting AI as a differentiator.
The comparator sourcing is poised for premium pricing because regulators now insist that reference batches match local formulations, especially in Latin America. The rise of cell and gene therapies is accelerating demand for cryogenic fill-finish and just-in-time packaging close to infusion centers. Providers earning ISO 13485 alongside GMP enjoy an edge when supporting drug-device combination trials, extending their influence within the clinical trial supply market size envelope.
Phase III dominated 41.24% of 2025 value due to large patient cohorts and long study durations, yet Phase II is forecast to post a 10.72% CAGR to 2031, the highest among phases, as adaptive enrichment strategies compress development timelines. The FDA's Project Optimus mandates explorations of multiple dose levels in oncology Phase II trials, multiplying SKU counts and requiring flexible depots. Bioavailability and bioequivalence remain niche but stable, serving generic entrants. Phase I's modest volumes stem from tight cohort sizes and on-site manufacturing. Phase IV studies, tied to post-marketing safety, are expanding gradually, ensuring sustained if slower demand.
Adaptive designs often demand mid-study drug transfer between arms, a capability best served by providers with real-time visibility into site inventory. As a result, logistics partners offering granular tracking and rapid resupply are winning new Phase II contracts and broadening their clinical trial supply market share.
Complete Report Scope:
- By Service
- Logistics & Distribution
- Storage & Retention
- Packaging, Labelling & Blinding
- Manufacturing
- Comparator Sourcing
- Supply-Chain Management / Forecasting
- By Phase
- Bioavailability / Bioequivalence
- Phase I
- Phase II
- Phase III
- Phase IV / Post-Marketing
- By Therapeutic Area
- Cardiovascular Diseases
- Oncology
- Respiratory Diseases
- CNS & Mental Disorders
- Infectious Diseases
- Rare & Orphan Disorders
- By End User
- Pharmaceutical Companies
- Biologics / Biotech Companies
- Contract Research Organisations (CROs & CDMOs)
- Medical-Device Companies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 35.77% of 2025 revenue, anchored by dense site networks, mature depots, and pioneering FDA decentralized-trial guidance that accelerates direct-to-patient pilots in oncology and rare diseases. Canada and Mexico benefit from near-shoring; 40% of U.S. sponsors shifted some packaging to Mexico by 2025 to offset tariff risk. Labor shortages in GMP packaging and quality assurance inflate costs and lengthen timelines, particularly in Mid-Atlantic and Midwest hubs, prompting automation investments.
Asia-Pacific is projected to post a 9.44% CAGR to 2031, the fastest regional climb. China's conditional-approval pathway and India's expansion of GMP-certified facilities pull late-stage studies eastward. Japan aligned eCTD rules with ICH M8 in 2025, allowing seamless global dossiers. South Korea and Australia capture cardiovascular and metabolic trials via co-funding incentives. Nevertheless, cold-chain gaps in Southeast Asia keep excursion rates high; 11% of shipments breached temperature limits in a 2024 study.
Europe leverages the EMA's centralized application system to streamline multicountry studies and remains a powerhouse for large cardiovascular and respiratory trials. Spain and Italy are winning share because of lower per-patient costs, while Germany, France, and the U.K. retain leadership in complex oncology protocols. The Middle East is building temperature-controlled hubs in Dubai and Riyadh, positioning the Gulf as a springboard into North Africa. South America's contribution is smaller, yet Brazil and Argentina offer genetically diverse populations and cost advantages, making them attractive for large Phase III cardiovascular programs despite comparator-sourcing hurdles under ANVISA's 2025 rules.
- Almac Group
- Biocair International
- Catalent
- DHL Global Forwarding / Life Sciences
- Eurofins
- FedEx HealthCare Logistics
- ICON
- IQVIA Supply Chain Services
- KLIFO A/S
- Lonza Group
- Marken (UPS Healthcare)
- Movianto (Yusen Logistics)
- Myonex
- N-SIDE
- Parexel International
- PCI Pharma Services
- Piramal Group
- Sharp Services LLC
- Thermo Fisher Scientific (Patheon)
- World Courier ( Cencora)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Volume of Phase III Multicountry Trials
- 4.2.2 Expansion of Decentralized & Direct-To-Patient Logistics Models
- 4.2.3 Growth in Temperature-Sensitive Biologics & ATMP Pipelines
- 4.2.4 AI-Driven Demand Forecasting Reducing Overage & Waste
- 4.2.5 Tariff-Driven Near-Shoring of Packaging and Depot Networks
- 4.2.6 Sustainability & ESG Mandates Driving Adoption of Reusable, Low-Carbon Packaging
- 4.3 Market Restraints
- 4.3.1 Rising Cross-Border Regulatory Divergence Inflating Compliance Costs
- 4.3.2 Persistent Temperature-Excursion Losses in Emerging Markets
- 4.3.3 Skilled-Labor Shortages in GMP Packaging & QA Functions
- 4.3.4 Cyber-Security Risks to IRT / RTSM Platforms
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Service
- 5.1.1 Logistics & Distribution
- 5.1.2 Storage & Retention
- 5.1.3 Packaging, Labelling & Blinding
- 5.1.4 Manufacturing
- 5.1.5 Comparator Sourcing
- 5.1.6 Supply-Chain Management / Forecasting
- 5.2 By Phase
- 5.2.1 Bioavailability / Bioequivalence
- 5.2.2 Phase I
- 5.2.3 Phase II
- 5.2.4 Phase III
- 5.2.5 Phase IV / Post-Marketing
- 5.3 By Therapeutic Area
- 5.3.1 Cardiovascular Diseases
- 5.3.2 Oncology
- 5.3.3 Respiratory Diseases
- 5.3.4 CNS & Mental Disorders
- 5.3.5 Infectious Diseases
- 5.3.6 Rare & Orphan Disorders
- 5.4 By End User
- 5.4.1 Pharmaceutical Companies
- 5.4.2 Biologics / Biotech Companies
- 5.4.3 Contract Research Organisations (CROs & CDMOs)
- 5.4.4 Medical-Device Companies
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 France
- 5.5.2.3 United Kingdom
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Almac Group
- 6.3.2 Biocair International
- 6.3.3 Catalent Inc.
- 6.3.4 DHL Global Forwarding / Life Sciences
- 6.3.5 Eurofins Scientific
- 6.3.6 FedEx HealthCare Logistics
- 6.3.7 ICON plc
- 6.3.8 IQVIA Supply Chain Services
- 6.3.9 KLIFO A/S
- 6.3.10 Lonza Group
- 6.3.11 Marken (UPS Healthcare)
- 6.3.12 Movianto (Yusen Logistics)
- 6.3.13 Myonex
- 6.3.14 N-SIDE
- 6.3.15 Parexel International
- 6.3.16 PCI Pharma Services
- 6.3.17 Piramal Pharma Solutions
- 6.3.18 Sharp Services LLC
- 6.3.19 Thermo Fisher Scientific (Patheon)
- 6.3.20 World Courier ( Cencora)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment