|
시장보고서
상품코드
2125366
아시아태평양의 용적식 펌프 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Asia-Pacific Positive Displacement Pumps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
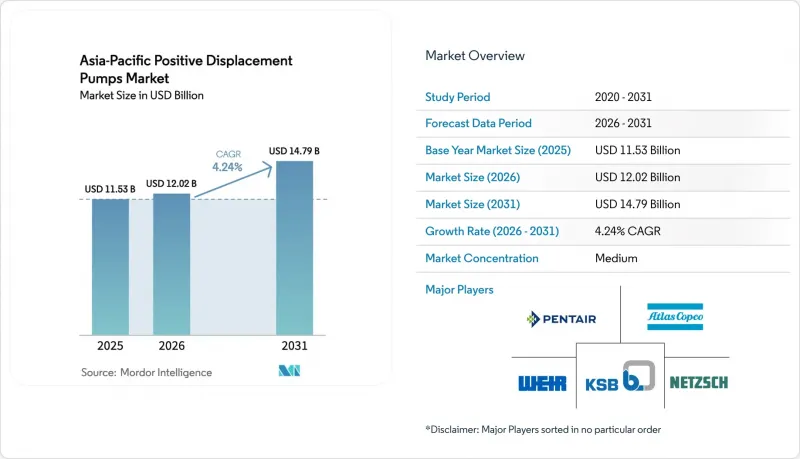
에 의하면, 아시아태평양의 용적식 펌프 시장 규모는 2025년에 115억 3,000만 달러로 평가되었고, 2026년 120억 2,000만 달러에서 2031년까지 147억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.24%를 나타낼 전망입니다.
본 보고서는 펌프 유형별(왕복식, 회전식, 프로그레시브 캐비티, 페리스타틱), 구동 방식별(전기 모터, 디젤/내연 기관 등), 재질별(주철, 스테인리스 스틸, 기타), 최종 사용자 산업별(석유 및 가스, 화학, 식품 및 음료, 폐기물 및 폐수 등), 국가별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
아시아태평양의 용적식 펌프 시장 동향 및 인사이트
아시아의 도시 하수 인프라 급속한 확충
도시 하수 네트워크의 확장에 따라, 점성이 있는 슬러지를 안정적인 유량으로 처리할 수 있는 프로그레시브 캐비티 펌프 및 스크류 펌프에 대한 지속적인 수주가 촉진되고 있으며, 이러한 펌프는 생물학적 처리 및 약품 주입 분야에서 선호되는 선택지가 되고 있습니다. 중국과 인도는 분산형 처리 시설에 막대한 규모의 인센티브를 할당하고 있으며, 동남아시아 국가들은 도시 주변 지역에 신속하게 도입할 수 있는 모듈형 스키드 패키지를 요구하고 있습니다. 따라서 프로그레시브 캐비티 펌프 공급업체들은 로터 및 스테이터의 마모를 감지하기 위한 모니터링 센서를 세트로 판매하여 현장 서비스 요청 횟수를 줄이고 있습니다. 인도네시아와 베트남의 현지 제조업체들도 예산에 민감한 지자체들을 대상으로 주철 모델의 생산을 확대하고 있지만, 수명 주기 평가(LCA)에서는 여전히 스테인리스 스틸 모델이 주류를 차지하고 있습니다. 아시아태평양(APAC) 지역의 용적식 펌프 시장은 상수도 유틸리티자가 10년간의 운영권 기간 동안 처리 능력을 보장하는 장기 서비스 계약을 체결하고 있다는 점에서 혜택을 보고 있습니다.
중국 특수 화학제품 클러스터의 VOC 배출 기준 강화
2,000 ppm 미만의 누출 감지 임계값을 의무화하는 엄격한 규제로 인해, 가공 업체들은 자기 구동식·밀폐형 설계를 지정할 수밖에 없게 되었으며, 재료 비용은 상승했지만 누출 배출에 대한 법적 책임은 경감되었습니다. 펌프 제조업체들은 초기 검사에서 규제 감사를 확실하게 통과할 수 있도록 센서가 탑재된 압력 보상 기능을 갖춘 이중 기계식 씰을 통합하고 있습니다. 규제 준수 기한이 다가옴에 따라 장쑤성, 산둥성, 광둥성의 산업 단지에서는 교체 주기가 가속화되고 있으며, 아시아태평양의 용적식 펌프 시장은 개보수 공사를 통한 수익 창출의 호기를 맞이하고 있습니다. VOC 모니터링 분석 서비스를 제공하는 기업들은 지역 환경 당국에 실시간 보고를 의무화해야 하는 특수 폴리머 제조업체들과 기본 계약을 체결하고 있습니다.
스테인리스 스틸과 구리 가격 변동이 펌프의 BOM 비용을 상승시키고 있습니다.
원자재비는 완제품 펌프 비용의 최대 60%를 차지하고 있으며, 스테인리스 스틸 가격의 15% 급등은 신속히 비용 전가가 이루어지지 않을 경우, 매출총이익률을 300 베이시스 포인트 낮출 가능성이 있습니다. 각 공급업체는 듀플렉스강 및 저몰리브덴강으로 제품군을 확대하는 한편, 내압 성능을 저하시키지 않으면서 두께를 얇게 만들기 위해 하우징 재설계를 추진하고 있습니다. 대형 OEM 제조업체들은 제철소와 연간 계약을 체결하고 있지만, 중소 제조업체들은 현금 흐름이 악화될 위험에 직면해 있으며, 이는 아시아태평양의 용적식 펌프 시장에서 업계 재편을 촉진하고 있습니다. ‘비용 중심 설계(Design-for-Cost)’에 따라 중요도가 낮은 하우징 부품의 복합 폴리머 부품으로의 전환이 가속화되면서, 가격 변동 위험에 대한 노출이 완화되고 있습니다.
부문 분석
로터리식 유닛은 2025년 매출의 51.12%를 차지했으며, 아시아태평양의 용적식 펌프 시장 규모에서 가장 큰 점유율을 기록하고 있는데, 이는 화학, 석유 및 가스, 식품 가공 분야에서의 다용도성이 뒷받침되고 있음을 보여줍니다. 한편, 페리스탈틱 펌프는 제로 오염이 절대 조건인 일회용 바이오프로세싱 프로토콜 및 화학 약품 공급 업무의 요구를 충족함으로써 연평균 성장률(CAGR) 7.06%라는 높은 성장률로 출하 대수 증가를 주도하고 있습니다.
기어 펌프 및 트윈 스크류 펌프 제품에는 현재 OEM의 클라우드 대시보드로 데이터를 전송하는 진동 센서 및 압력 센서가 탑재되어 있어, APAC의 용적식 펌프 시장 전체에서 예측 유지보수의 도입이 가속화되고 있습니다. 로브 펌프는 유제품 및 음료 산업의 확장에 따른 수요에 힘입어 성장하고 있는 반면, 베인 펌프는 윤활 회로에서 틈새 시장 역할을 유지하고 있습니다.
전동 모터 모델은 2025년 매출의 63.21%를 차지했으며, APAC 용적식 펌프 시장에서 공장 자동화 및 이송 용도로 확고한 입지를 뒷받침하고 있습니다. 태양광 발전식 패키지는 여전히 틈새 분야이긴 하지만, 농업용 관개 및 외딴 지역 급수 프로젝트에서 태양광 발전 비용의 하락이 호재로 작용하여 연평균 성장률(CAGR) 9.32%를 달성하고 있습니다.
고효율 IE4 모터와 결합된 가변 주파수 드라이브는 수명 주기 동안 에너지 소비를 줄이는 한편, 배기 가스 규제가 강화됨에 따라 디젤 유닛은 비상용 및 Off-grid 용도로 후퇴하고 있습니다. 공압 시스템은 에너지 효율보다 본질 안전성이 우선시되는 위험한 환경에서 여전히 확고한 입지를 유지하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the APAC positive displacement pumps market size was valued at USD 11.53 billion in 2025 and estimated to grow from USD 12.02 billion in 2026 to reach USD 14.79 billion by 2031, at a CAGR of 4.24% during the forecast period (2026-2031).
This report is Segmented by Pump Type (Reciprocating, Rotary, Progressive Cavity, and Peristaltic), Driving Method (Electric Motor, Diesel/IC Engine, and More), Material (Cast Iron, Stainless Steel, and Other Materials), End-User Industry (Oil and Gas, Chemicals, Food and Beverage, Waste and Wastewater, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Asia-Pacific Positive Displacement Pumps Market Trends and Insights
Rapid Build-out of Asia's Municipal Wastewater Infrastructure
Expanding municipal wastewater networks spur recurring orders for progressive cavity and screw units that handle viscous sludges with stable flow, making these pumps a preferred choice for biological treatment and chemical dosing. China and India allocate significant stimulus to decentralized plants, and Southeast Asian nations seek modular skid packages that can be deployed quickly in peri-urban areas. Progressive cavity suppliers therefore bundle monitoring sensors to flag wear on rotors and stators, reducing on-site service calls. Local fabricators in Indonesia and Vietnam also scale up cast iron models for budget-sensitive municipalities, but stainless variants continue to dominate lifecycle assessments. The APAC positive displacement pumps market benefits as water utilities anchor long-term service agreements that guarantee throughput performance across 10-year concessions.
Tightening VOC Discharge Limits in China's Specialty-Chemicals Clusters
Stringent rules mandating leak detection thresholds below 2,000 ppm push processors to specify magnetic-drive and hermetically sealed designs, creating a material premium yet reducing fugitive emissions liability. Pump makers integrate dual mechanical seals with sensor-enabled pressure compensation to ensure regulatory audits pass on first inspection. Compliance deadlines intensify replacement cycles in Jiangsu, Shandong and Guangdong complexes, positioning the APAC positive displacement pumps market for retrofit revenue. Companies offering VOC-monitoring analytics secure framework agreements with specialty polymer producers that require real-time reporting to local environmental bureaus.
Volatile Stainless-Steel and Copper Prices Inflate Pump BOM Cost
Raw materials account for up to 60% of finished-pump cost; a 15% spike in stainless price can cut gross margins by 300 bps if not passed through swiftly. Suppliers diversify into duplex or low-molybdenum grades and redesign housings to reduce wall thickness without compromising pressure ratings. Larger OEMs lock annual contracts with mills, while smaller fabricators risk cash-flow tightness, prompting consolidation within the APAC positive displacement pumps market. Design-for-cost engineering accelerates the transition to composite polymer components in non-critical housings, easing volatility exposure.
Other drivers and restraints analyzed in the detailed report include:
- Electrification of Offshore Platforms Raises Demand for Low-Shear Pumps
- Mini-Bulk Biopharma Facilities Adopting Single-Use Peristaltic Skids
- Skilled-Labor Shortage for Complex Progressive-Cavity Pump MRO
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rotary units contributed 51.12% of 2025 revenue, equating to the largest slice of the APAC positive displacement pumps market size and validating their versatility in chemicals, oil and gas and food handling applications. Peristaltic pumps, however, lead volume growth at a 7.06% CAGR by satisfying single-use bioprocessing protocols and chemical-feed duties where zero contamination is non-negotiable.
Gear and twin-screw products now ship with vibration and pressure sensors that feed OEM cloud dashboards, accelerating predictive-maintenance uptake across the APAC positive displacement pumps market. Lobe designs ride demand from dairy and beverage expansions, while vane variants maintain niche roles in lubrication circuits.
Electric-motor models delivered 63.21% of 2025 revenue, underscoring their entrenched role in factory automation and conveying applications across the APAC positive displacement pumps market share. Solar-powered packages, though still a niche, achieve a 9.32% CAGR as agricultural irrigation and remote water supply projects benefit from declining photovoltaic costs.
Variable-frequency drives paired with high-efficiency IE4 motors cut lifecycle energy use, while diesel units retreat to emergency and off-grid roles under tightening emission norms. Pneumatic systems retain a foothold in hazardous environments where intrinsic safety trumps energy efficiency.
Complete Report Scope:
- By Pump Type
- Reciprocating Pumps
- Piston
- Diaphragm
- Rotary Pumps
- Gear
- Lobe
- Screw
- Vane
- Progressive Cavity
- Peristaltic
- Reciprocating Pumps
- By Driving Method
- Electric Motor
- Diesel/IC Engine
- Pneumatic
- Hydraulic
- Solar
- By Material
- Cast Iron
- Stainless Steel
- Other Materials
- By End-user Industry
- Oil and Gas
- Chemicals
- Food and Beverage
- Waste and Wastewater
- Pharmaceutical and Biotech
- Power Generation
- Pulp and Paper
- Mining and Metals
- Other Industries
- By Country
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- Atlas Copco AB
- The Weir Group PLC
- KSB SE and Co. KGaA
- NETZSCH Holding GmbH
- Pentair plc
- SPX FLOW, Inc.
- Sulzer Ltd.
- Xylem Inc.
- Grundfos Holding A/S
- Tsurumi Manufacturing Co., Ltd.
- Ebara Corporation
- Flowserve Corporation
- Dover Corporation (PSG)
- IDEX Corporation
- Alfa Laval AB
- Kirloskar Brothers Ltd.
- Shakti Pumps (India) Ltd.
- Yamada Corporation
- Sepex Corporation
- Tapflo Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid build-out of Asia's municipal wastewater infrastructure
- 4.2.2 Tightening VOC discharge limits in China's specialty-chemicals clusters
- 4.2.3 Electrification of offshore platforms raises demand for low-shear pumps
- 4.2.4 Mini-bulk biopharma facilities adopting single-use peristaltic skids
- 4.2.5 OEM shift to smart sensor-enabled rotary pumps (mainstream)
- 4.2.6 Post-COVID capex rebound in FandB processing lines (mainstream)
- 4.3 Market Restraints
- 4.3.1 Volatile stainless-steel and copper prices inflate pump BOM cost
- 4.3.2 Skilled-labor shortage for complex progressive-cavity pump MRO
- 4.3.3 Rising preference for seal-less mag-drive centrifugals in pharma
- 4.3.4 Lengthy BIS certification cycle delays India roll-outs
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macro Economic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Pump Type
- 5.1.1 Reciprocating Pumps
- 5.1.1.1 Piston
- 5.1.1.2 Diaphragm
- 5.1.2 Rotary Pumps
- 5.1.2.1 Gear
- 5.1.2.2 Lobe
- 5.1.2.3 Screw
- 5.1.2.4 Vane
- 5.1.3 Progressive Cavity
- 5.1.4 Peristaltic
- 5.1.1 Reciprocating Pumps
- 5.2 By Driving Method
- 5.2.1 Electric Motor
- 5.2.2 Diesel/IC Engine
- 5.2.3 Pneumatic
- 5.2.4 Hydraulic
- 5.2.5 Solar
- 5.3 By Material
- 5.3.1 Cast Iron
- 5.3.2 Stainless Steel
- 5.3.3 Other Materials
- 5.4 By End-user Industry
- 5.4.1 Oil and Gas
- 5.4.2 Chemicals
- 5.4.3 Food and Beverage
- 5.4.4 Waste and Wastewater
- 5.4.5 Pharmaceutical and Biotech
- 5.4.6 Power Generation
- 5.4.7 Pulp and Paper
- 5.4.8 Mining and Metals
- 5.4.9 Other Industries
- 5.5 By Country
- 5.5.1 China
- 5.5.2 Japan
- 5.5.3 India
- 5.5.4 South Korea
- 5.5.5 Australia and New Zealand
- 5.5.6 Rest of Asia-Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Atlas Copco AB
- 6.4.2 The Weir Group PLC
- 6.4.3 KSB SE and Co. KGaA
- 6.4.4 NETZSCH Holding GmbH
- 6.4.5 Pentair plc
- 6.4.6 SPX FLOW, Inc.
- 6.4.7 Sulzer Ltd.
- 6.4.8 Xylem Inc.
- 6.4.9 Grundfos Holding A/S
- 6.4.10 Tsurumi Manufacturing Co., Ltd.
- 6.4.11 Ebara Corporation
- 6.4.12 Flowserve Corporation
- 6.4.13 Dover Corporation (PSG)
- 6.4.14 IDEX Corporation
- 6.4.15 Alfa Laval AB
- 6.4.16 Kirloskar Brothers Ltd.
- 6.4.17 Shakti Pumps (India) Ltd.
- 6.4.18 Yamada Corporation
- 6.4.19 Sepex Corporation
- 6.4.20 Tapflo Group
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment