

|
시장보고서
상품코드
2125402
영국의 웨어러블 기술 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United Kingdom Wearable Technology - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
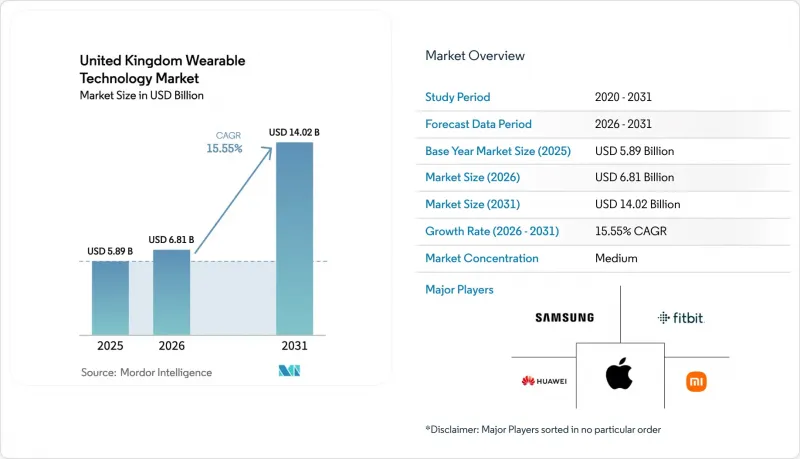
에 의하면, 영국의 웨어러블 기술 시장 규모는 2025년 58억 9,000만 달러로 평가되었습니다. 2026년에는 68억 1,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 15.55%로 성장을 지속하여, 2031년에는 140억 2,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 기기 유형(스마트 워치, 헤드마운트 디스플레이, 손목 밴드 등), 연결 기술(블루투스, 셀룰러 등), 운영 체제(watchOS, Wear OS 등),용도(소비자용 피트니스, 헬스케어 모니터링 등), 유통 채널(온라인 소매 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
영국의 웨어러블 기술 시장 동향 및 인사이트
NHS 디지털 헬스 이니셔티브의 확대
2024년에는 가상 병동이 영국의 환자 400만 명을 지원했으며, 웨스트 요크셔, 험버, 노스 요크셔, 그리고 케임브리지와 피터버러 지역의 통합 의료 위원회는 더 광범위한 대상 범위 확대를 계획하고 있습니다. 통합된 조달 프레임워크를 통해 임상 검증에서 전국적 전개에 이르는 과정이 단축되므로, MHRA의 승인을 받은 바이오센서가 탑재된 기기 공급업체가 우선적으로 검토되고 있습니다. 스코틀랜드와 웨일스는 잉글랜드의 모델을 본받고 있으며, 검증된 웨어러블 기기에 대한 꾸준한 수요를 뒷받침하는 원격 환자 모니터링이 전국적으로 채택되고 있는 것으로 나타났습니다. NHS의 목표는 만성 호흡기 질환 및 심혈관 질환 프로그램을 우선시하고 있으며, 이는 스마트 워치의 혈압 및 맥박 산소 측정기 기능과 부합합니다. 예측 분석 플랫폼은 원시 데이터를 실무 의료진을 위한 경보로 변환함으로써 기기의 유용성을 더욱 높이고 있습니다.
건강 보험 인센티브를 위한 웨어러블 기기와 영국 핀테크 생태계의 통합
핀테크 계열 보험사들은 걸음 수, 심박 변이도, 수면 점수를 동적인 보험료 할인과 연계하여, 디지털 네이티브 세대를 중심으로 한 젊은 층의 이용을 촉진하고 있습니다. 오픈 뱅킹 기준과 FCA(금융행위감독청)의 감독을 통해 웨어러블 앱과 금융 대시보드 간의 안전한 데이터 교환이 보장되어 도입에 대한 신뢰도가 높아지고 있습니다. 고용주는 동일한 데이터 흐름을 활용하여 웰니스 보너스를 지급하고, 단체 건강보험 비용을 절감하고 있습니다. 보험사가 장기적인 데이터 접근 권한을 대가로 하드웨어 비용을 보조함으로써, 기기 제조업체는 지속적인 수익을 얻을 수 있습니다. 크로스 플랫폼 API는 사용자 편의성을 높이고, 생태계의 유지율을 강화하며, 해지율을 낮게 유지합니다.
GDPR(EU 개인정보보호규정) 시행 이후 영국의 데이터 개인정보 보호 규제 강화
정보위원회(ICO)는 건강 데이터 처리 업체에 대한 감사를 강화하고, 동의 관련 미비 사항에 대해 막대한 벌금을 부과하고 있어, 소규모 브랜드들은 제한된 자금을 규정 준수 대응에 투입하거나 영국 시장에서 철수하고 있습니다. 의무화된 데이터 보호 영향 평가로 인해 신기능 출시가 지연되고, 시장 출시까지의 기간이 길어지고 있습니다. 미국 클라우드 서버로의 국경 간 데이터 전송에는 추가적인 계약상 보호 조치가 필요하며, 이로 인해 운영 비용이 증가합니다. 오래된 벤더들은 성숙한 개인정보 보호 인프라를 활용하고 있지만, 그들조차도 사용자 참여를 저해하지 않으면서 세심한 동의를 얻기 위해 사용자 흐름을 재설계하고 있습니다. 제품에 명시된 개인정보 보호 성과에 대한 메시지는 현재 배터리 수명이나 방수 성능과 동등하거나 그 이상으로 구매 결정에 큰 영향을 미치고 있습니다.
부문별 분석
2025년, 스마트 워치는 영국의 웨어러블 기술 시장 점유율의 56.16%를 차지했으며, Apple Watch의 고혈압 치료에 대한 승인으로 그 임상적 유용성이 입증됨에 따라 가장 큰 수익을 창출했습니다. 귀 착용형 기기는 메타(Meta)의 AR 오디오 글라스와 EEG 및 EMG 신호를 눈에 띄지 않게 기록하는 센서를 풍부하게 탑재한 애플의 에어팟(AirPods)에 힘입어 연평균 성장률(CAGR) 16.11%로 성장을 주도하고 있습니다.
수요는 스마트 링과 섬유에 통합된 스마트웨어로 다양화되고 있습니다. Oura사는 2025년 링 출하 대수를 2배로 늘리며, 화면으로 인한 피로감 없이 지속적인 모니터링을 실현하는 미니멀한 디자인에 대한 높은 수요를 보여주었습니다. 노인 요양 시설에서의 스마트웨어 시범 도입에서는 세탁 가능한 섬유를 통해 낙상 위험 및 수분 섭취량 데이터가 기록되고 있으며, 이는 패션, 의료 모니터링, ESG 준수 소재의 향후 융합 가능성을 시사하고 있습니다.
2025년에는 연결의 65.95%를 블루투스가 차지했으나, 병원이나 창고에서 센티미터 단위의 실내 위치 측정이 요구됨에 따라 울트라 와이드밴드(Ultra-Wideband)의 채택률은 연평균 16.80%의 속도로 증가하고 있습니다. 또한, 끊김 없는 원격 환자 모니터링이 필요한 고위험 환자를 위한 셀룰러 방식의 손목 밴드에는 5G 모뎀이 탑재되기 시작했습니다.
메쉬 네트워크용 펌웨어를 통해 스마트 링은 데이터를 손목시계로, 나아가 스마트폰으로 중계할 수 있게 되어, 실시간 전송을 유지하면서 전력 소비를 줄이고 있습니다. Ofcom의 주파수 대역 할당은 공존을 보장하며, 기기 제조업체들은 대역폭 요구 사항과 배터리 상태에 따라 자동으로 전환되는 듀얼 라디오 칩셋을 설계하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the UK wearable technology market size is expected to grow from USD 5.89 billion in 2025 to USD 6.81 billion in 2026 and is forecast to reach USD 14.02 billion by 2031 at 15.55% CAGR over 2026-2031.
This report is Segmented by Device Type (Smart Watches, Head-Mounted Displays, Wristbands, and More), Connectivity Technology (Bluetooth, Cellular, and More), Operating System (watchOS, Wear OS, and More), Application (Consumer Fitness, Healthcare Monitoring, and More), Distribution Channel (Online Retail, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Wearable Technology Market Trends and Insights
Proliferation of NHS Digital Health Initiatives
Virtual wards supported 4 million UK patients in 2024 and integrated care boards across West Yorkshire, Humber and North Yorkshire, and Cambridge and Peterborough plan broader coverage. Unified procurement frameworks shorten the path from clinical validation to national rollout, so device vendors with MHRA-cleared biosensors receive preferential consideration. Scotland and Wales mirror England's model, evidencing nation-wide adoption of remote patient monitoring that underpins steady demand for validated wearables. NHS targets prioritize chronic respiratory and cardiovascular programs, aligning with smart-watch blood-pressure and pulse-ox features. Predictive analytics platforms further amplify device utility by translating raw data into actionable care-team alerts.
Integration of Wearables with UK Fintech Ecosystem for Health-Insurance Incentives
Fintech insurers link step counts, heart-rate variability, and sleep scores to dynamic premium discounts, spurring usage across younger, digitally native groups. Open banking standards and FCA oversight ensure secure data exchange between wearable apps and financial dashboards, improving adoption confidence. Employers deploy the same data flows to trigger wellness bonuses that lower group health-cover costs. Device makers benefit from recurring revenue when insurers subsidize hardware in exchange for long-term data access. Cross-platform APIs reduce user friction, reinforcing ecosystem stickiness and keeping churn low.
Stricter UK Data Privacy Enforcement Post-GDPR
The Information Commissioner's Office intensifies audits of health-data processors and levies heavy fines for consent mis-steps, so smaller brands divert scarce funds into compliance or retreat from the UK. Mandatory data-protection-impact assessments slow new-feature rollouts, stretching time-to-market. Cross-border transfers to U.S. cloud servers trigger additional contractual safeguards that elevate operating expense. Established vendors capitalize on their mature privacy infrastructures, yet even they redesign user flows to gain granular consent without hurting engagement. Clear privacy victory messages on packaging now influence purchasing almost as strongly as battery life or waterproof ratings.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of AI-Powered Predictive Health Analytics in Consumer Wearables
- Rise of Workplace Wellness Regulations in the UK
- Consumer Skepticism on Long-Term Accuracy of Biosensors
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Smart watches accounted for 56.16% of UK wearable technology market share in 2025 and generated the highest revenue as Apple Watch's hypertension clearance validated clinical utility. Ear-wearables lead growth at 16.11% CAGR, propelled by Meta's AR audio glasses and Apple's sensor-rich AirPods that discreetly record EEG and EMG signals.
Demand diversifies into smart rings and textile-embedded smart clothing. Oura doubled 2025 ring shipments, demonstrating appetite for minimalist form factors that deliver continuous monitoring without screen fatigue. Smart clothing pilots in elder-care homes record fall risk and hydration data through washable fibers, pointing to future convergence between fashion, medical monitoring, and ESG-compliant materials.
Bluetooth covered 65.95% of connections in 2025, but Ultra-Wideband adoption is rising 16.80% annually as hospitals and warehouses seek centimeter-level indoor location. 5G modems appear in cellular wristbands targeted at high-risk patients who require uninterrupted remote patient monitoring.
Mesh networking firmware lets smart rings relay data to a watch, then to a phone, cutting power draw while maintaining real-time transmission. Ofcom spectrum allocations guarantee coexistence, and device makers design dual-radio chipsets that switch automatically based on bandwidth needs and battery status.
Complete Report Scope:
- By Device Type
- Smart Watches
- Head-mounted Displays
- Wristbands
- Ear-wearables
- Smart Clothing
- Smart Rings
- Other Device Types
- By Connectivity Technology
- Bluetooth
- Wi-Fi
- Cellular
- NFC
- Ultra-Wideband
- 5G
- Other Connectivity Technologies
- By Operating System
- watchOS
- Wear OS
- Proprietary OS
- RTOS
- Linux
- Other Operating Systems
- By Application
- Consumer Fitness
- Healthcare Monitoring
- Remote Patient Monitoring
- Corporate Wellness
- Sports Performance
- Medical Diagnostics
- Other Applications
- By Distribution Channel
- Online Retail
- Offline Consumer Electronics
- Specialist Health Stores
- Pharmacies
- Department Stores
- Other Distribution Channels
- By Geography
- England
- Scotland
- Wales
- Northern Ireland
List of Companies Covered in this Report:
- Apple Inc.
- Samsung Electronics Co. Ltd.
- Fitbit LLC
- Huawei Technologies Co. Ltd.
- Xiaomi Inc.
- Garmin Ltd.
- Fossil Group Inc.
- OnePlus Technology (Shenzhen) Co. Ltd.
- Sekonda Ltd.
- Honor Device Co.
- Huami Corporation (Amazfit) Ltd.
- Withings SA
- Polar Electro Oy
- Suunto Oy
- Oura Health Oy
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of NHS Digital Health Initiatives
- 4.2.2 Integration of Wearables with UK Fintech Ecosystem for Health Insurance Incentives
- 4.2.3 Adoption of AI-Powered Predictive Health Analytics in Consumer Wearables
- 4.2.4 Rise of Workplace Wellness Regulations in the UK
- 4.2.5 Expansion of 5G and IoT Infrastructure Across the UK
- 4.2.6 Growing Demand for Remote Patient Monitoring in Ageing Population
- 4.3 Market Restraints
- 4.3.1 Stricter UK Data Privacy Enforcement Post-GDPR
- 4.3.2 Wearable Device VAT Reclassification Risk
- 4.3.3 Battery Waste Regulations Increasing Compliance Cost
- 4.3.4 Consumer Skepticism on Long-Term Accuracy of Biosensors
- 4.4 Industry Ecosystem Analysis
- 4.5 Regulatory Landscape
- 4.6 Impact of Macroeconomic Factors
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Device Type
- 5.1.1 Smart Watches
- 5.1.2 Head-mounted Displays
- 5.1.3 Wristbands
- 5.1.4 Ear-wearables
- 5.1.5 Smart Clothing
- 5.1.6 Smart Rings
- 5.1.7 Other Device Types
- 5.2 By Connectivity Technology
- 5.2.1 Bluetooth
- 5.2.2 Wi-Fi
- 5.2.3 Cellular
- 5.2.4 NFC
- 5.2.5 Ultra-Wideband
- 5.2.6 5G
- 5.2.7 Other Connectivity Technologies
- 5.3 By Operating System
- 5.3.1 watchOS
- 5.3.2 Wear OS
- 5.3.3 Proprietary OS
- 5.3.4 RTOS
- 5.3.5 Linux
- 5.3.6 Other Operating Systems
- 5.4 By Application
- 5.4.1 Consumer Fitness
- 5.4.2 Healthcare Monitoring
- 5.4.3 Remote Patient Monitoring
- 5.4.4 Corporate Wellness
- 5.4.5 Sports Performance
- 5.4.6 Medical Diagnostics
- 5.4.7 Other Applications
- 5.5 By Distribution Channel
- 5.5.1 Online Retail
- 5.5.2 Offline Consumer Electronics
- 5.5.3 Specialist Health Stores
- 5.5.4 Pharmacies
- 5.5.5 Department Stores
- 5.5.6 Other Distribution Channels
- 5.6 By Geography
- 5.6.1 England
- 5.6.2 Scotland
- 5.6.3 Wales
- 5.6.4 Northern Ireland
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Apple Inc.
- 6.4.2 Samsung Electronics Co. Ltd.
- 6.4.3 Fitbit LLC
- 6.4.4 Huawei Technologies Co. Ltd.
- 6.4.5 Xiaomi Inc.
- 6.4.6 Garmin Ltd.
- 6.4.7 Fossil Group Inc.
- 6.4.8 OnePlus Technology (Shenzhen) Co. Ltd.
- 6.4.9 Sekonda Ltd.
- 6.4.10 Honor Device Co.
- 6.4.11 Huami Corporation (Amazfit) Ltd.
- 6.4.12 Withings SA
- 6.4.13 Polar Electro Oy
- 6.4.14 Suunto Oy
- 6.4.15 Oura Health Oy
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


