|
시장보고서
상품코드
2125415
미국의 컴퓨터 단층촬영(CT) 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)United States Computed Tomography - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 미국 컴퓨터 단층촬영(CT) 시장 규모는 2025년 34억 8,000만 달러에서 2026년에는 37억 1,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 6.66%로 성장을 지속하여, 2031년에는 51억 3,000만 달러에 이를 것으로 예측됩니다.
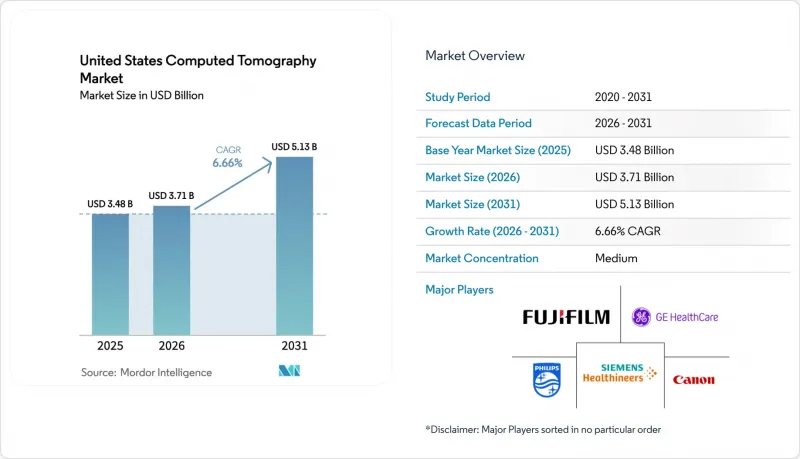
본 보고서는 제품 유형(저슬라이스, 중슬라이스, 고슬라이스), 용도(종양학, 신경학 등), 이동성(고정식 시스템, 이동식 시스템) 및 최종 사용자(병원, 영상진단센터 등)별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
미국 컴퓨터 단층촬영(CT) 시장 동향 및 인사이트
만성 질환 유병률 증가가 영상 진단 수요를 견인
2050년까지 심혈관 질환은 미국 성인 4,500만 명에게 영향을 미칠 것으로 예상되며, 고혈압 유병률은 2020년 51.2%에서 2050년에는 61.0%로 상승할 것으로 전망됩니다. 비만, 우울증, 고지혈증의 병행 증가로 인해 2013년부터 2023년까지 젊은 성인의 다중 질환 유병률은 52.5%에서 59.5%로 상승했습니다. 임상적 복잡성 증가는 검사 건수 증가로 이어지고 있으며, CT 이용률은 2055년까지 25.1% 증가할 것으로 예측됩니다. 각 병원 시설에서는 2030년까지 시설당 검사 건수가 175% 급증할 것으로 전망됨에 따라, 심장 CT 프로그램 확충을 추진하고 있습니다. 메디케어가 가상 CT 대장내시경 검사의 보험 적용을 결정한 것은 정책 입안자들이 예방적 영상 진단을 비용 절감 전략으로 간주하고 있음을 보여주는 또 다른 징후입니다.
고령 인구 증가가 첨단 영상 진단의 도입을 가속화
65세 이상 성인은 가장 빠르게 증가하는 인구층으로, 예약이 빠르고 주차도 편리한 외래 진료를 선호합니다. 2023년 병원 지출은 10.4% 증가했는데, 그 원인 중 하나는 고령자 진단의 복잡화 때문입니다. Vizient사는 향후 10년 동안 CT와 PET를 필두로 외래 진료에서의 고도 영상 진단 검사 건수가 13% 증가할 것으로 예측했습니다. 이러한 변화는 CT 시장에 호재가 될 것입니다. 외래 진료 센터에서는 심장 검사 기능을 갖추면서도 초기 투자 비용이 낮은 중급형 스캐너가 자주 도입되기 때문입니다. 그러나 인력 유출이 이러한 성장을 복잡하게 만들고 있습니다. 남성 방사선과 의사의 이직률은 13.5%에 달하고, 인력 부족이 심화되고 있습니다.
높은 장비 도입 비용이 시장 침투를 저해
100만 달러를 초과하는 스캐너의 초기 도입 비용은 지방 의료기관의 재무 상황을 압박하고 있습니다. 병원 폐쇄로 인해 현재 지역 내 CT 검사를 받을 수 없는 카운티에 거주하는 미국인은 전체의 20%에 달할 전망입니다. 의료기관이 지불을 수익 주기에 맞추려 노력하는 가운데, 매니지드 서비스 계약이나 현금 흐름에 영향을 주지 않는 자금 조달 방식이 보급되고 있습니다. 지멘스의 ‘SOMATOM Pro.Pulse’는 전력 소비를 20% 절감하여 소규모 시설의 총 비용을 낮춥니다.
부문 분석
2025년, 고슬라이스 수 플랫폼은 컴퓨터 단층촬영(CT) 시장 점유율의 35.12%를 차지하며, 이는 빠른 시간 분해능이 필수적인 심장, 외상 및 종양학 영상 진단 분야에서 이 플랫폼이 가진 우위를 반영합니다. 중간 슬라이스 수 시스템은 연평균 성장률(CAGR) 7.53%를 나타낼 것으로 예측되며, 256슬라이스 플래그십 모델만큼의 비용을 들이지 않고도 심장 진단 기능을 원하는 외래 진료 센터에서 점점 더 많이 선택되고 있습니다. GE 헬스케어의 ‘Revolution Vibe’는 중저가 대에서 1회 심박 이미징을 실현하고 있으며, 시장이 가치 중심의 업그레이드로 전환되고 있음을 보여줍니다. 저슬라이스 스캐너는 방사선 피폭량 최소화가 최우선으로 고려되는 소아의 경과 관찰이나 기본적인 외상 검사에서 여전히 중요한 역할을 하고 있습니다. 특히 도시 외곽의 시설에서는 자본 예산이 제한적이기 때문에 중가대 기종으로의 교체를 선호하며, 이에 따라 공급업체들은 구성 가능한 옵션과 AI 번들 확충을 촉진하고 있습니다.
2000년대 초반에 도입된 16슬라이스 주력 기종을 의료기관들이 순차적으로 퇴역시키면서, 도입 장비 구성의 변화가 진행되고 있습니다. 리퍼비시 프로그램은 안전망 병원을 대상으로 하는 반면, 사모펀드가 지원하는 영상진단 체인은 보험사로부터 용량 인센티브를 확보하기 위해 신규 도입을 선호하고 있습니다. 중규모 구성의 CT는 병원 직영 센터와 경쟁하는 외래 진료 분야에서 견실한 ROI를 가져다주기 때문에 CT 시장은 그 혜택을 누리고 있습니다. 후처리 과정에서의 벤더 중립성도 락인(lock-in) 현상을 완화하고 있어, 중규모 기종의 도입을 더욱 뒷받침하고 있습니다. 전반적으로, 예산의 일관성과 처리량 요구 사항으로 인해 2031년까지 중형 슬라이스 기술이 주목받는 부문이 될 것입니다.
2025년에는 정기적인 모니터링이 필요한 면역요법 프로토콜의 확대에 힘입어 종양학 분야가 CT 시장 규모의 33.05%를 차지했습니다. 반면, 신경학 분야는 AI 트리아지 도구를 통해 뇌졸중 스캔에서 치료까지의 시간이 단축됨에 따라 연평균 성장률(CAGR) 7.44%로 가장 빠르게 성장하는 분야가 될 것입니다. RapidAI사의 ‘Lumina 3D’는 두경부 CTA의 재구성 시간을 몇 시간에서 몇 분으로 단축하여, 기술자가 1교대당 더 많은 환자를 처리할 수 있도록 합니다. 또한, CMS가 관상동맥 CTA의 보험 적용 범위를 확대함에 따라, 플라크 분석을 위해 128슬라이스 이상의 스캐너를 도입하는 의료기관이 증가하여, 순환기 분야의 검사 건수도 증가하고 있습니다.
광자 계수형 검출기는 골다공증 관리에 유용한 해면골의 미세 구조를 규명함으로써 근골격 분야에 새로운 전망을 열어주고 있습니다. 응급실에서는 여전히 전신 외상 프로토콜에 의존하고 있지만, 선량을 최적화한 반복 재구성을 통해 소아 검사에서 ALARA 지침을 준수할 수 있게 되었습니다. 그 결과, 각 벤더사는 임상 서비스 분야별로 구성 가능한 다목적 스캐너의 출하를 촉진하는 수요 구조가 형성되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the United States computed tomography market size is expected to grow from USD 3.48 billion in 2025 to USD 3.71 billion in 2026 and is forecast to reach USD 5.13 billion by 2031 at 6.66% CAGR over 2026-2031.
This report is Segmented by Product Type (Low Slice, Medium Slice, and High Slice), Application (Oncology, Neurology, and More), Mobility (Fixed Systems and Mobile Systems), and End User (Hospitals, Diagnostic Imaging Centers, and Others). The Market and Forecasts are Provided in Terms of Value (USD).
United States Computed Tomography Market Trends and Insights
Rising Prevalence of Chronic Diseases Drives Imaging Demand
Cardiovascular disease is projected to affect 45 million U.S. adults by 2050, and hypertension prevalence is forecast to climb from 51.2% in 2020 to 61.0% in 2050. Parallel increases in obesity, depression, and hyperlipidemia have lifted multimorbidity from 52.5% to 59.5% among younger adults between 2013 and 2023. Greater clinical complexity translates into higher examination volumes; CT utilization is expected to rise 25.1% through 2055 . Hospitals are expanding cardiac CT programs in anticipation of a 175% surge in procedures per site by 2030. Medicare's decision to cover virtual CT colonography is another signal that policymakers see preventive imaging as a cost-saving strategy.
Growing Geriatric Population Accelerates Advanced Imaging Adoption
Adults aged 65+ represent the fastest-growing cohort and prefer outpatient settings that offer faster appointments and easier parking. Hospital spending rose 10.4% in 2023 due in part to geriatric diagnostic complexity. Vizient projects a 13% advance in outpatient advanced imaging volumes over the next decade, led by CT and PET. The shift favors the computed tomography market because ambulatory centers often adopt mid-tier scanners that combine cardiac capability with lower capital cost. Workforce attrition complicates this growth: male radiologists face a 13.5% exit rate, intensifying staffing gaps.
High Equipment Acquisition Costs Constrain Market Penetration
Upfront scanner prices exceeding USD 1 million strain rural balance sheets; 20% of Americans live in counties now lacking local CT access after hospital closures. Managed service agreements and cash-flow-neutral financing have gained traction as providers seek to match payments with revenue cycles. Siemens' SOMATOM Pro.Pulse reduces energy draw by 20%, lowering total cost for small facilities.
Other drivers and restraints analyzed in the detailed report include:
- Continuous Technological Advancements Transform Clinical Workflows
- Expanded CMS Reimbursement Enhances Access to Preventive Screening
- Radiology Workforce Shortages Limit Scanner Utilization Potential
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
High-slice platforms held 35.12% of the computed tomography market share in 2025, reflecting their dominance in cardiac, trauma, and oncology imaging where rapid temporal resolution is critical. Medium-slice systems are forecast to deliver a 7.53% CAGR and are increasingly selected by outpatient centers seeking cardiac capability without the cost of 256-slice flagships. GE Healthcare's Revolution Vibe offers single-heartbeat imaging at a mid-tier price, illustrating the market's pivot toward value-centric upgrades. Low-slice scanners remain relevant for pediatric follow-up and basic trauma studies when dose minimization is paramount. Constrained capital budgets, especially in non-urban facilities, favor mid-range replacements, encouraging suppliers to expand configurable options and AI bundles.
An installed-base shift is under way as providers retire 16-slice workhorses introduced in the early 2000s. Refurbishment programs target safety-net hospitals, whereas private equity-backed imaging chains prefer new installations to capture capacity incentives from payers. The computed tomography market benefits as medium configurations deliver robust ROI in outpatient corridors competing with hospital-owned centers. Vendor neutrality in post-processing has also reduced lock-in, further supporting mid-range adoption. Overall, budget alignment and throughput requirements make medium-slice technology the segment to watch through 2031.
Oncology captured 33.05% of the computed tomography market size in 2025, supported by expanding immunotherapy protocols that require serial monitoring. Neurology, however, will be the fastest climber at 7.44% CAGR because AI triage tools cut scan-to-treatment time for stroke. RapidAI's Lumina 3D slashes head-and-neck CTA reconstructions from hours to minutes, allowing technologists to move more patients per shift. Cardiovascular volumes also rise as CMS broadens coronary CTA reimbursement, prompting providers to install scanners with >=128 slices for plaque analytics.
Photon-counting detectors are opening new musculoskeletal horizons by resolving trabecular microarchitecture, valuable in osteoporosis management. Emergency departments still rely on whole-body trauma protocols, yet dose-optimized iterative reconstruction helps comply with ALARA guidelines in pediatric workups. The net effect is a demand mix that encourages vendors to ship multipurpose scanners configurable per clinical service line.
Complete Report Scope:
- By Product Type
- Low Slice
- Medium Slice
- High Slice
- By Application
- Oncology
- Neurology
- Cardiovascular
- Musculoskeletal
- Other Applications
- By Mobility
- Fixed Systems
- Mobile Systems
- By End User
- Hospitals
- Diagnostic Imaging Centers
- Others
List of Companies Covered in this Report:
- GE Healthcare
- Siemens Healthineers
- Koninklijke Philips
- Canon Medical Systems USA, Inc.
- FUJIFILM
- Carestream Health
- United Imaging Healthcare
- Samsung Neurologica Corp.
- Neusoft
- Planmeca Group (Planmed Oy)
- Koning
- Accuray
- Imris Deerfield Imaging
- Analogic
- CurveBeam
- Xoran Technologies
- Spectrum Dynamics Medical
- Epica Medical Innovations
- Animage
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising prevalence of chronic diseases
- 4.2.2 Growing geriatric population
- 4.2.3 Continuous technological advancements in CT
- 4.2.4 Expanded CMS reimbursement for low-dose lung cancer screening (LDCT)
- 4.2.5 Adoption of mobile CT in outpatient & trauma settings
- 4.2.6 Rapid AI-based workflow & image-quality upgrades
- 4.3 Market Restraints
- 4.3.1 High equipment acquisition & maintenance costs
- 4.3.2 Stringent FDA regulatory pathway & 510(k) backlog
- 4.3.3 Radiation-dose related patient safety concerns
- 4.3.4 Radiology workforce shortages constraining scanner utilization
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porters Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Low Slice
- 5.1.2 Medium Slice
- 5.1.3 High Slice
- 5.2 By Application
- 5.2.1 Oncology
- 5.2.2 Neurology
- 5.2.3 Cardiovascular
- 5.2.4 Musculoskeletal
- 5.2.5 Other Applications
- 5.3 By Mobility
- 5.3.1 Fixed Systems
- 5.3.2 Mobile Systems
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Diagnostic Imaging Centers
- 5.4.3 Others
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 GE Healthcare
- 6.3.2 Siemens Healthineers AG
- 6.3.3 Koninklijke Philips NV
- 6.3.4 Canon Medical Systems USA, Inc.
- 6.3.5 Fujifilm Holdings Corporation
- 6.3.6 Carestream Health
- 6.3.7 United Imaging Healthcare
- 6.3.8 Samsung Neurologica Corp.
- 6.3.9 Neusoft Medical Systems Co. Ltd
- 6.3.10 Planmeca Group (Planmed Oy)
- 6.3.11 Koning Corporation
- 6.3.12 Accuray Incorporated
- 6.3.13 Imris Deerfield Imaging
- 6.3.14 Analogic Corporation
- 6.3.15 CurveBeam
- 6.3.16 Xoran Technologies
- 6.3.17 Spectrum Dynamics Medical
- 6.3.18 Epica Medical Innovations
- 6.3.19 Animage LLC
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment