|
시장보고서
상품코드
2125446
인도의 컴퓨터 단층촬영(CT) 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)India Computed Tomography - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
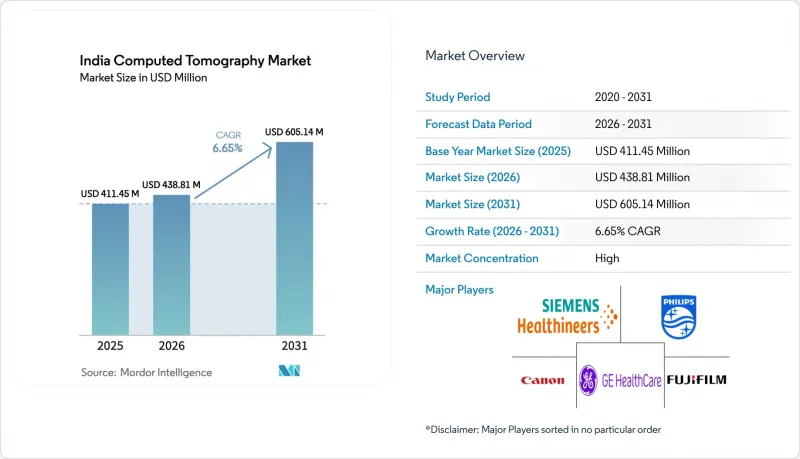
에 의하면, 인도의 컴퓨터 단층촬영(CT) 시장 규모는 2025년에 4억 1,145만 달러로 평가되었고, 2026년 4억 3,881만 달러로 추정되며, 2031년까지 6억 514만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 6.65%를 나타낼 전망입니다.
본 보고서는 기술별(저슬라이스, 중슬라이스, 고슬라이스), 제품 유형별(고정형 CT 스캐너, 휴대용/모바일형 CT 스캐너),용도별(종양학, 순환기학, 신경학 등), 최종 사용자별(병원, 영상진단센터 등), 장치 아키텍처별(나선형/헬리컬 CT, 링 갠트리 CT 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
인도의 컴퓨터 단층촬영(CT) 시장 동향 및 인사이트
암 유병률 증가와 선별 검사 프로그램 확대
2040년까지 연간 약 200만 건의 신규 암 사례가 예상에 따라, CT를 활용한 적시 진단에 대한 필요성이 높아지고 있습니다. ‘내셔널 캔서 그리드(National Cancer Grid)’에 따른 표준화된 진료 경로를 통해, 64슬라이스 이상의 장비를 갖춘 영상진단센터로 더 많은 환자가 유도되고 있습니다. ‘MegCan Care’와 같은 정부 프로젝트를 통해 비용 측면의 장벽이 해소되면서 공립 병원의 검사 건수가 증가하고 있습니다. AIIMS 델리에 도입된 AI 기반 종양학 솔루션은 영상 분석 알고리즘을 통해 검사 보고서 작성 시간을 단축하고 종양 감지 정확도를 향상시킬 수 있음을 입증하고 있습니다. 인도의 컴퓨터 단층촬영(CT) 시장에서 종양학은 이미 가장 큰 임상 부문으로 자리 잡았으며, 보다 광범위한 선별 검사 프로토콜로 인해 대도시권의 장비 교체 주기가 가속화되고 있으며, 이는 이후 2선 도시로 확산되고 있습니다.
공공 부문 병원의 설비 투자 증가(‘아유슈만 바라트’, 주 정부 입찰)
‘프라단 만트리 아유슈만 바라트 보건 인프라 미션’은 인도 전역의 신규 및 개보수된 진단 시설에 77억 달러를 배정하고 있습니다. 조달 지침은 국내 생산 스캐너를 우선시하고 있어, PLI 인증 공장을 보유한 공급업체로의 수주가 가속화되고 있습니다. 정부 외상 센터에 최근 도입된 128슬라이스 장비는 응급 의료 분야의 영상 품질 기준을 한 단계 높이고 있습니다. 또한 16곳의 AIIMS 캠퍼스가 신설될 예정이며, 각 캠퍼스에는 여러 개의 영상진단 부서가 필요하기 때문에 향후 10년 동안 지속적인 입찰이 예상됩니다. CGHS(중앙정부 공무원 건강보험 제도)의 환급 기준 재검토로 인해 인증 시설에 대한 지급 단가가 인상됨에 따라, 피폭 선량이 적은 CT 플랫폼에 투자하는 공립 병원의 영업 이익률이 뒷받침되고 있습니다.
64슬라이스 이상 시스템의 높은 도입 및 수명 주기 비용
특히 병상당 설비 투자액 상한선이 1만 8,000달러 가까이 설정된 경우, 하이엔드 시스템은 중규모 병원의 총 설비 예산을 초과할 가능성이 있습니다. 서비스 계약, X선관 교체, 소프트웨어 업데이트 비용은 10년 동안 초기 청구 금액의 40-60%에 달하는 경우가 많습니다. 이러한 경제적 요인으로 인해 심장 CT 혈관조영술에 대한 임상적 수요가 증가하고 있음에도 불구하고, 대도시권 이외 지역에서의 도입은 제한되고 있습니다. 국내 제조업체들의 정가 인하가 있기는 하지만, 인도 컴퓨터 단층촬영(CT) 시장에 대한 추가적인 침투를 위해서는 자금 조달 방식의 혁신이 계속해서 필수적일 것입니다.
부문 분석
2025년, 인도의 컴퓨터 단층촬영(CT) 시장에서 중간 슬라이스 수의 스캐너가 42.78%를 차지했으며, 가격과 성능의 최적의 균형을 확인했습니다. 심장 질환 및 외상 사례 수가 증가함에 따라, Tier 1 병원에서는 128슬라이스 플랫폼으로의 업그레이드가 진행되고 있으며, 이 시장은 2031년까지 연평균 성장률(CAGR) 7.08%로 확대되고 있습니다. 인도의 컴퓨터 단층촬영(CT) 시장에서 64슬라이스 장치 시장 규모는 여전히 크지만, 조달 사양이 엄격해짐에 따라 시장 점유율은 슬라이스 수가 더 많은 기종으로 이동하고 있습니다. 각 벤더사는 반복 재구성 엔진을 탑재한 AI 지원 중슬라이스 모델을 출시하며, 예산에 민감한 지역에서 이 부문의 중요성을 유지하고 있습니다. 향후에는 총 소유 비용(TCO) 절감과 듀얼 에너지 기능 추가로 인해 64슬라이스 미만 장비에서의 전환이 가속화될 것으로 예측됩니다.
AOCR 2025에서 공개된 2세대 광자 계수형 프로토타입은 장기적인 혁신의 방향을 보여주고 있지만, 상업적 보급은 인도 컴퓨터 단층촬영(CT) 시장에 적합한 가격 곡선에 달려 있습니다. 또한, 정부 입찰에서는 방사선 피폭량 상한선이 규정되어 있어 AI 지원형 128슬라이스 장비에 유리하게 작용하고 있습니다. 그 결과, 기술 동향으로는 중간 슬라이스 수를 진입점으로 삼고, 높은 슬라이스 수를 임상적 목표로 삼는 단계적인 확대 추세가 나타날 것으로 보입니다.
2025년 시점에서 인도의 컴퓨터 단층촬영(CT) 시장 규모의 88.22%를 고정형 플랫폼이 차지했습니다. PACS, 전력 인프라, 차폐 설비와의 통합을 통해 이들은 다학제 병원의 기반이 되고 있습니다. 한편, 휴대형 스캐너는 중환자실(ICU)에서 병상 옆 신경 영상 진단을 실현함으로써 7.56%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 각 제조업체는 임시 격리 병동에 대응하기 위해 gantry의 설치 면적을 축소하고 리튬 이온 전원 팩을 채택하고 있습니다. 재난 대응 팀에 모바일 CT 밴을 배치하는 정책적 노력도 병행된 성장의 길을 열어주고 있습니다. 외상 대응 프로토콜이 성숙해짐에 따라, 응급실과 수술실을 오가는 ‘듀얼 듀티(Dual Duty)’ 방식의 도입이 인도 컴퓨터 단층촬영(CT) 시장에서 모바일 기기의 기여도를 높일 가능성이 있습니다.
금융 관계자들은 임시 방사선 진료 캠프를 위해 ‘일 단위 임대 계약’을 시범적으로 도입하고 있으며, 이를 통해 외딴 지역에서의 첫 도입이 촉진되고 있습니다. 그러나 화질 제한과 냉각 요건으로 인해 이동식 장치는 특정 임상 시나리오로만 제한됩니다. 따라서 병상 확충 프로그램이 진료 건수의 안정성을 뒷받침함에 따라, 고정식 부문은 구조적 우위를 유지할 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the India computed tomography (CT) market size was valued at USD 411.45 million in 2025 and estimated to grow from USD 438.81 million in 2026 to reach USD 605.14 million by 2031, at a CAGR of 6.65% during the forecast period (2026-2031).
This report is Segmented by Technology (Low-Slice, Mid-Slice, High-Slice), Product Type (Stationary CT Scanners, Portable/Mobile CT Scanners), Application (Oncology, Cardiology, Neurology, and More), End-User (Hospitals, Diagnostic Imaging Centers, and More), Device Architecture (Spiral/Helical CT, Ring-Gantry CT, and More). The Market Forecasts are Provided in Terms of Value (USD).
India Computed Tomography Market Trends and Insights
Escalating Cancer Prevalence & Screening Programs
Nearly 2 million new cancer cases are expected annually by 2040, heightening the need for timely CT-based diagnosis. Standardized pathways from the National Cancer Grid are funneling more patients to imaging centers equipped with 64-slice or higher platforms. Government projects such as MegCan Care are removing cost barriers, lifting examination volume at public hospitals. AI-powered oncology suites introduced at AIIMS Delhi demonstrate how image-analysis algorithms can cut report turnaround time and improve tumor detection accuracy. With oncology already the largest clinical segment inside the India Computed Tomography (CT) market, broader screening protocols are reinforcing equipment replacement cycles in metropolitan hubs before diffusing to tier-2 cities.
Rising Public-Sector Hospital Capex (Ayushman Bharat, State Tenders)
The Pradhan Mantri Ayushman Bharat Health Infrastructure Mission allocates USD 7.7 billion for new and upgraded diagnostic suites across India. Procurement guidelines favor domestically manufactured scanners, accelerating order flow for vendors with PLI-certified plants. Recent installations of 128-slice units in government trauma centers are raising the benchmark for image quality in emergency medicine. Sixteen additional AIIMS campuses, each requiring multi-room imaging departments, promise recurring tenders through the decade. Reimbursement revisions under CGHS, with higher tariffs for accredited facilities, are cushioning operating margins for public hospitals that invest in dose-efficient CT platforms.
High Acquisition & Lifecycle Costs of >=64-Slice Systems
Premium systems can exceed total equipment budgets of mid-sized hospitals, especially where per-bed capital outlay is capped near USD 18,000. Service contracts, tube replacements and software updates often equal 40-60% of the original invoice across a decade. These economics constrain adoption beyond metropolitan centers despite rising clinical demand for cardiac CT angiography. Although domestic manufacturing trims list prices, financing innovations will remain critical for broader penetration of the India Computed Tomography (CT) market.
Other drivers and restraints analyzed in the detailed report include:
- Rapid AI/ML Integration for Dose-Optimized Scans & Workflow
- PLI-Led Domestic CT Manufacturing Push
- Shortage of Radiologists / Service Engineers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Mid-slice scanners accounted for 42.78% of the India Computed Tomography (CT) market in 2025, confirming their sweet-spot balance between price and performance. Rising cardiology and trauma volumes are prompting tier-1 hospitals to upgrade to 128-slice platforms, which are advancing at 7.08% CAGR through 2031. The India Computed Tomography (CT) market size for 64-slice equipment remains substantial, but share is drifting toward higher arrays as procurement specifications tighten. Vendors are launching AI-ready mid-slice models with iterative reconstruction engines, preserving the segment's relevance in budget-sensitive districts. Over time, lower total cost of ownership and dual-energy add-ons are expected to accelerate the shift away from <64-slice machines.
Second-generation photon-counting prototypes showcased at AOCR 2025 spotlight long-term innovation pathways, yet commercial uptake will hinge on price curves suitable for the India Computed Tomography (CT) market. Government tenders are also specifying radiation dose caps, giving AI-assisted 128-slice units an edge. Consequently, the technology landscape will feature a gradual laddering effect, with mid-slice as entry point and high-slice as clinical aspiration.
Stationary platforms held 88.22% share of the India Computed Tomography (CT) market size in 2025. Their integration with PACS, power infrastructure and shielding makes them the backbone of multispecialty hospitals. Portable scanners, however, are registering the quickest 7.56% CAGR by delivering bedside neuro imaging in intensive-care units. Manufacturers are shrinking gantry footprints and using lithium-ion power packs to suit makeshift isolation wards. Policy efforts to equip disaster-response teams with mobile CT vans are opening a parallel growth track. As trauma protocols mature, dual-duty deployments that swing between emergency departments and operating suites are likely to lift mobility's contribution inside the India Computed Tomography (CT) market.
Financiers are experimenting with pay-per-day rental contracts for pop-up radiology camps, fostering first-time adoption in remote areas. Yet image-quality limitations and cooling requirements confine mobile units to targeted clinical scenarios. The stationary segment will thus preserve its structural dominance, aided by hospital-bed expansion programs that anchor volume stability.
Complete Report Scope:
- By Technology (Slice Count)
- Low-slice (<64)
- Mid-slice (64)
- High-slice (128-256)
- By Product Type
- Stationary CT Scanners
- Portable / Mobile CT Scanners
- By Application
- Oncology
- Lung Cancer Screening
- Head & Neck Oncology
- Colorectal Oncology
- Other Oncology
- Cardiology
- Coronary CT Angiography
- Calcium Scoring
- Structural Heart Disease
- Neurology
- Stroke Assessment
- Brain Trauma
- Vascular
- Peripheral Vascular Disease
- Pulmonary Angiography
- Musculoskeletal
- Orthopedic Trauma
- Sports Injuries
- Dental & Maxillofacial
- Trauma & Emergency
- Other Applications
- Oncology
- By End-User
- Hospitals
- Public Hospitals
- Private Hospitals
- Diagnostic Imaging Centers
- Dental Clinics
- Veterinary Clinics & Hospitals
- Academic & Research Institutes
- Hospitals
- By Device Architecture
- Spiral / Helical CT
- Ring-Gantry CT
- C-arm CT
- O-arm CT
- Flat-Panel Detector CT
List of Companies Covered in this Report:
- GE HealthCare Technologies Inc.
- Siemens Healthineers
- Koninklijke Philips
- Canon
- United Imaging Healthcare Co., Ltd.
- Hitachi
- FUJIFILM
- Trivitron Healthcare
- Allengers Medical Systems Ltd.
- Carestream Health
- Neusoft
- Shenzhen Anke High-tech Co., Ltd.
- Planmed
- Shimadzu
- Samsung Group
- Vatech Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating cancer prevalence & screening programmes
- 4.2.2 Rising public-sector hospital capex (Ayushman Bharat, state tenders)
- 4.2.3 Rapid AI/ML integration for dose-optimized scans & workflow
- 4.2.4 PLI-led domestic CT manufacturing push
- 4.2.5 Teleradiology uptake in Tier-2/3 cities enabling scanner demand
- 4.2.6 Micro-leasing & NBFC financing models for stand-alone diagnostics
- 4.3 Market Restraints
- 4.3.1 High acquisition & lifecycle costs of >=64-slice systems
- 4.3.2 Shortage of radiologists / service engineers
- 4.3.3 Low reimbursement tariffs under CGHS & private insurers
- 4.3.4 Radiation-safety licensing delays (AERB)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Technology (Slice Count)
- 5.1.1 Low-slice (<64)
- 5.1.2 Mid-slice (64)
- 5.1.3 High-slice (128-256)
- 5.2 By Product Type
- 5.2.1 Stationary CT Scanners
- 5.2.2 Portable / Mobile CT Scanners
- 5.3 By Application
- 5.3.1 Oncology
- 5.3.1.1 Lung Cancer Screening
- 5.3.1.2 Head & Neck Oncology
- 5.3.1.3 Colorectal Oncology
- 5.3.1.4 Other Oncology
- 5.3.2 Cardiology
- 5.3.2.1 Coronary CT Angiography
- 5.3.2.2 Calcium Scoring
- 5.3.2.3 Structural Heart Disease
- 5.3.3 Neurology
- 5.3.3.1 Stroke Assessment
- 5.3.3.2 Brain Trauma
- 5.3.4 Vascular
- 5.3.4.1 Peripheral Vascular Disease
- 5.3.4.2 Pulmonary Angiography
- 5.3.5 Musculoskeletal
- 5.3.5.1 Orthopedic Trauma
- 5.3.5.2 Sports Injuries
- 5.3.6 Dental & Maxillofacial
- 5.3.7 Trauma & Emergency
- 5.3.8 Other Applications
- 5.3.1 Oncology
- 5.4 By End-User
- 5.4.1 Hospitals
- 5.4.1.1 Public Hospitals
- 5.4.1.2 Private Hospitals
- 5.4.2 Diagnostic Imaging Centers
- 5.4.3 Dental Clinics
- 5.4.4 Veterinary Clinics & Hospitals
- 5.4.5 Academic & Research Institutes
- 5.4.1 Hospitals
- 5.5 By Device Architecture
- 5.5.1 Spiral / Helical CT
- 5.5.2 Ring-Gantry CT
- 5.5.3 C-arm CT
- 5.5.4 O-arm CT
- 5.5.5 Flat-Panel Detector CT
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.3.1 GE HealthCare Technologies Inc.
- 6.3.2 Siemens Healthineers AG
- 6.3.3 Koninklijke Philips N.V.
- 6.3.4 Canon Medical Systems Corporation
- 6.3.5 United Imaging Healthcare Co., Ltd.
- 6.3.6 Hitachi, Ltd.
- 6.3.7 Fujifilm Holdings Corporation
- 6.3.8 Trivitron Healthcare Pvt. Ltd.
- 6.3.9 Allengers Medical Systems Ltd.
- 6.3.10 Carestream Health, Inc.
- 6.3.11 Neusoft Medical Systems Co., Ltd.
- 6.3.12 Shenzhen Anke High-tech Co., Ltd.
- 6.3.13 Planmed Oy
- 6.3.14 Shimadzu Corporation
- 6.3.15 Samsung Electronics Co., Ltd.
- 6.3.16 Vatech Co., Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment