

|
시장보고서
상품코드
2125472
유럽의 목재 펠릿 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Wood Pellet - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
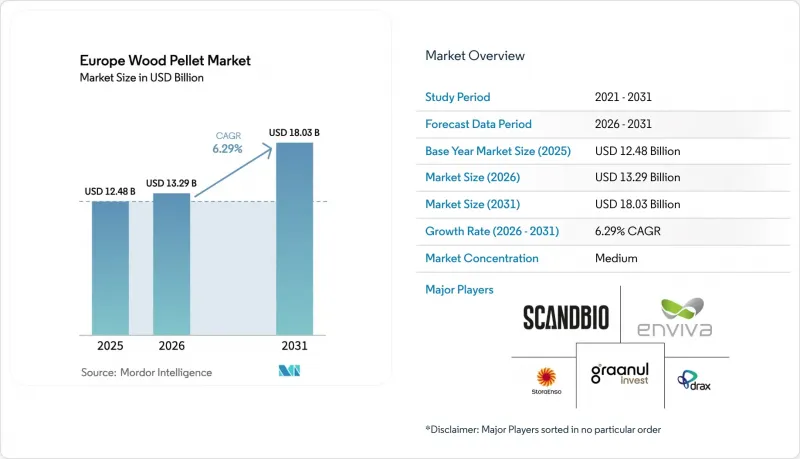
에 의하면, 유럽 목재 펠릿 시장 규모는 2025년에 124억 8,000만 달러, 2026년에 132억 9,000만 달러가 되어, 2031년까지 180억 3,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년까지 CAGR 6.29%로 성장할 전망입니다.
본 보고서는 원료(임업·목재 잔재물, 농업 잔재물, 에너지 작물과 톱밥의 혼합물), 등급(유틸리티 등급, 프리미엄 등급,스탠다드 등급 등), 용도(난방, 열전병급, 기타), 최종 사용자(주택, 산업·유틸리티, 기타), 지역(영국, 독일, 프랑스, 스페인, 북유럽 국가, 러시아, 기타 유럽)별로 분류되어 있습니다.
유럽 목재 펠릿 시장 동향 및 인사이트
화석 연료 가격이 사상 최고 수준을 기록하는 가운데, 견조한 주거용 난방 수요
2024년 내내 유럽의 가스 가격이 높은 수준을 유지함에 따라, 목재 펠릿은 단독주택 및 소규모 사업자의 난방 연료로서 비용 경쟁력 있는 선택지가 되었습니다. 오스트리아에서는 인센티브 제도가 변경되지 않아 보일러 설치 대수가 견조한 추세를 보였으며, 독일과 프랑스에서도 보조금 제도가 재검토되었음에도 불구하고 여전히 상당한 수준 수요가 유지되었습니다. ENplus 인증은 연소 품질을 보장함으로써 국경을 초월한 펠릿 거래를 촉진했습니다. 2024년에는 주택용 수요 점유율이 유럽 전체 소비량의 7%에 달했습니다. 2024년 8월 독일의 BEG 개혁으로 바이오매스 단독에 대한 보조금이 삭감되었지만, 주택용 공급업체들은 장비 금융 및 개별 판매 프로그램으로 사업을 확대함으로써 수익의 평준화를 도모하고 있습니다. 따라서 현물 거래에 기반한 판매에 내재된 가격 변동을 상쇄하기 위해서는 수직 통합이 필수적이어지고 있습니다.
EU 발전소의 석탄에서 바이오매스로의 전환 가속화
2024년 드랙스 그룹이 4호기를 재가동함에 따라 약 300만 톤의 추가 펠릿 수요가 발생했고, 영국의 바이오매스 발전량이 회복되었습니다. 아르셀로미탈의 벨기에 트레로 시설 등 신규 프로젝트는 제철 고로에 바이오 석탄을 공급함으로써, 배출 감축이 어려운 산업 분야에서 바이오매스를 활용하는 사례를 보여주고 있습니다. 유럽투자은행(EIB)의 지원을 받은 스페인의 라 로브라 발전소는 국내 농업 잔여물을 연료로 전환함으로써 물류에 따른 배출량을 줄이는 동시에 원료의 유연성을 높였습니다. 기존 송전망 연결 및 터빈을 재사용할 수 있어 기존 설비의 개조를 통한 경제성은 여전히 양호하지만, 영국의 2027년 이후 정책 불확실성으로 인해 인수량이 절반으로 줄어들 가능성이 있어 수요 포트폴리오의 다각화가 필요하다는 점이 부각되고 있습니다. 원목보다 잔여물을 우선시하는 EU의 캐스케이드 이용 원칙 또한 마찬가지로 향후 공급 확대 가능성을 제한하고 있습니다.
펠릿 보일러에 대한 국가 보조금 폐지와 히트 펌프와의 경쟁
독일은 2024년 8월에 바이오매스 단독 인센티브를 폐지했으며, 그 결과 2023년부터 2024년까지 보일러 판매 대수가 55% 급감했습니다. 프랑스에서는 인센티브가 전기 히트펌프로 전환됨에 따라 73%라는 더욱 급격한 하락을 기록했습니다. 네덜란드는 신축 주택의 바이오매스 난방에 대한 보조금을 중단하고, 자금을 전기로만 전환하고 있습니다. 중국의 생산 규모 확대로 인해 히트펌프 장비 가격이 15-20% 하락하여 펠릿의 비용 우위가 훼손되었습니다. 또한, 도시 지역의 대기질 규제로 인해 미세먼지 배출 기준이 강화되면서 인구 밀집 지역에서의 펠릿 보급이 제한되었습니다. 보조금 폐지와 저렴한 전기식 대체품의 등장이 맞물리면서 주택용 수요가 약화되었고, 생산자들은 이익률이 낮은 장기 계약을 협상하는 산업용 구매자에 대한 의존도를 높일 수밖에 없게 되었습니다.
부문 분석
2025년 유럽 목재 펠릿 시장 규모의 70.2%는 산림 및 목재 잔여물이 차지하고 있으며, 이는 견고한 제재소 네트워크와 성숙한 ENplus 물류 체계를 반영합니다. 한편, 농업 잔여물은 운송 에너지를 38% 절감하는 이동식 펠릿화 플랫폼의 도입으로 연평균 성장률(CAGR) 7.8%를 기록하며 증가하고 있습니다. 스페인 라 로브라 공장에서는 공급망의 탄소 배출량을 줄이기 위해 현지산 짚을 원료로 채택하는 것이 입증되었습니다. 농업 유래 원료는 회분(2-5%)이 높고 에너지 밀도가 낮은 데다, EU의 산림 파괴 규제로 인해 우대 조치가 시행되고 있어, 열병합발전(CHP) 시설에서의 혼합 시험이 촉진되고 있습니다. 생산자들은 품질 편차를 관리하기 위해 정교한 선별 및 첨가제 투입을 도입하고 있으며, 이는 장기적으로 여러 원료를 조달하는 전략으로의 전환을 시사합니다.
2026년부터 2031년까지 산림 잔재물은 여전히 유럽 목질 펠릿 시장의 기반을 이루겠지만, 농업 유래 원료는 유틸리티자 수요를 충족시키면서 과도하게 벌채된 산림에 가해지는 압력을 완화하는 데 필요한 증분 성장을 가져올 것입니다. 또한, 주택 건설 사이클의 둔화로 제재소 생산량이 감소할 경우, 혼합은 잔재물 부족에 대한 헤지 역할도 수행합니다. 유틸리티자가 규제 준수 요건을 충족한 펠릿을 요구하는 가운데, 다양한 원료 풀을 인증할 수 있는 이해관계자는 새로운 계약을 확보할 수 있을 것으로 전망됩니다.
2025년, 유럽 목재 펠릿 시장 점유율의 55.8%를 차지한 것은 전력 회사를 대상으로 한 화이트 펠릿이었으며, 이는 고품질 사양보다 낮은 납품 비용을 중시하는 대규모 발전 프로젝트에 공급되고 있습니다. 유럽의 토레파이션 처리된 목질 펠릿 시장 규모는 핀란드의 ANDRITZ사가 연산 6만 톤 규모의 요엔수 바이오콜 공장을 가동한 것을 계기로 연평균 성장률(CAGR) 9.4%로 확대되고 있습니다. 열분해 처리를 통해 에너지 밀도가 22-28 GJ/t로 향상되어, 대규모 설비 개조 없이도 석탄 화력 발전소에서 혼소할 수 있게 됩니다. 조기 도입 기업으로는 열분해 펠릿을 제철로에 투입하고 있는 아르셀로미탈이 있으며, 이는 산업 전반에 걸친 가능성을 보여주고 있습니다. 자본 집약도는 여전히 100-150유로/t의 상한선을 유지하고 있어, 도입은 CHP(열전병급)의 폐열로 건조 공정을 충당할 수 있고 잔재물이 풍부한 지역에 집중되고 있습니다. 유럽에서 석탄 화력 발전소의 폐지가 진행되는 가운데, 각 전력사는 탈탄소화로의 전환 경로로 트로팩션을 검토하고 있습니다.
업계의 공감대로는 2031년까지 열처리 펠릿의 점유율이 두 자릿수에 달할 것으로 예상되며, 특히 석탄 자산이 조정 가능한 발전 용량을 차지하는 북유럽 및 중부 유럽에서 이러한 경향이 두드러집니다. 표준 등급 및 프리미엄 등급은 가정용 보일러 시장에서 계속해서 중요성을 유지할 것이지만, 하이브리드 시스템 및 히트 펌프의 보급에 따라 그 성장세는 완만해질 전망입니다. 등급 포트폴리오를 다각화하는 제조업체는 수요 변동을 완화하면서 높은 수익률을 자랑하는 열처리 펠릿 계약을 확보할 수 있을 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the Europe wood pellet market size is projected to be USD 12.48 billion in 2025, USD 13.29 billion in 2026, and reach USD 18.03 billion by 2031, growing at a CAGR of 6.29% from 2026 to 2031.
This report is Segmented by Feedstock (Forest/Wood Residue, Agricultural Residue, and Energy-Crop and Sawdust Mix), Grade (Utility-Grade, Premium-Grade, Standard-Grade, and More), Application (Heating, Combined Heat and Power, and More), End-User (Residential, Industrial and Utility, and More), and Geography (United Kingdom, Germany, France, Spain, NORDIC Countries, Russia, and Rest of Europe).
Europe Wood Pellet Market Trends and Insights
Robust Residential Heating Demand Amid Record Fossil-Fuel Prices
Gas prices in Europe stayed elevated through 2024, making wood pellets a cost-competitive option for space heating in single-family homes and small businesses. Austria maintained solid boiler installations thanks to unchanged incentives, while Germany and France still absorbed considerable volumes despite subsidy revisions. ENplus certification encouraged cross-border pellet trade by guaranteeing burn quality. The share of residential demand reached 7% of total European consumption in 2024. Although Germany's August 2024 BEG reform curtailed standalone biomass subsidies, residential suppliers are smoothing earnings by expanding into appliance financing and doorstep retail programs. Vertical integration is therefore becoming essential to offset the inherent volatility of spot-based sales.
Accelerated Coal-to-Biomass Conversion of EU Power Plants
Drax Group's restart of Unit 4 in 2024 injected about 3 million t of extra pellet demand and revived UK biomass electricity output. New projects, such as ArcelorMittal's Torero facility in Belgium, illustrate biomass applications in hard-to-abate industries by delivering bio-coal to steel blast furnaces. Spain's La Robla plant, backed by the European Investment Bank, shifted to domestic agricultural residues, cutting logistics emissions and broadening feedstock flexibility. Retrofit economics remain favorable because existing grid connections and turbines are reused, but post-2027 policy uncertainty in the UK may halve offtake, underscoring the need for diversified demand portfolios. EU cascading-use principles, which prioritize residues over roundwood, likewise cap future supply scalability.
Termination of National Pellet Boiler Subsidies and Heat-Pump Competition
Germany scrapped standalone biomass incentives in August 2024, causing a 55% plunge in boiler sales from 2023 to 2024. France recorded an even steeper 73% drop as incentives shifted toward electric heat pumps. The Netherlands stopped subsidizing biomass heat in new homes, funneling funds exclusively to electrification. Accelerated manufacturing scale in China lowered heat-pump equipment prices by 15-20%, eroding pellets' cost advantage. Urban air-quality rules also tightened particulate limits, limiting pellet uptake in dense areas. Together, subsidy withdrawal and cheaper electric alternatives weaken residential demand, forcing producers to rely more heavily on industrial buyers that negotiate longer-term contracts at thinner margins.
Other drivers and restraints analyzed in the detailed report include:
- New EU-ETS Incentives for Negative-Emission BECCS Projects
- Surge in Heat-Pump / Pellet-Hybrid Boiler Retrofits
- Feed-Wood Fiber Scarcity, Price Spikes, and EUDR Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Forest and wood residues generated 70.2% of the European wood pellet market size in 2025, reflecting robust sawmill networks and mature ENplus logistics. Agricultural residues, however, are rising at a 7.8% CAGR, aided by mobile pelletizing platforms that shrink transport energy by 38%. Spain's La Robla plant validated local straw sourcing to cut supply-chain emissions. Even though agricultural streams carry higher ash (2-5%) and lower energy density, the EU Deforestation Regulation treats them preferentially, spurring trial blends at CHP units. Producers are adopting advanced sieving and additive dosing to manage quality variability, signaling a longer-term pivot toward multi-feedstock procurement strategies.
Over 2026-2031, forest residues will still underpin the European wood pellet market, but agricultural inputs provide the incremental growth needed to meet utility demand while easing pressure on over-harvested forests. Blending also hedges against residue shortages when housing cycles slow sawmill output. Stakeholders that can certify diverse feedstock pools stand to capture new contracts as utilities seek compliance-ready pellets.
Utility-grade white pellets accounted for 55.8% of the European wood pellet market share in 2025, supplying large-scale power projects that value low delivered cost over premium specs. The European wood pellet market size for torrefied variants is expanding at a 9.4% CAGR, catalyzed by ANDRITZ's 60,000 t Joensuu Biocoal plant in Finland. Torrefaction raises energy density to 22-28 GJ t, enabling coal-plant co-firing without major retrofit. Early adopters include ArcelorMittal, which feeds torrefied pellets into steel furnaces, demonstrating cross-sector potential. Capital intensity remains EUR 100-150 t cap, so deployment concentrates near residue-rich clusters where CHP waste heat can supply the drying step. As more European coal units face retirement, utilities weigh torrefaction as a transitional decarbonization pathway.
Industry consensus sees torrefied pellets reaching double-digit share by 2031, particularly in Northern and Central Europe, where coal assets represent dispatchable capacity. Standard and premium grades will maintain relevance in residential boilers, but growth moderates as hybrids and heat pumps take hold. Manufacturers that diversify across grade portfolios will mitigate demand swings while capturing high-margin torrefied contracts.
Complete Report Scope:
- By Feedstock
- Forest/Wood Residue
- Agricultural Residue
- Energy-Crop and Sawdust Mix
- By Grade
- Utility-Grade (White)
- Premium-Grade
- Standard-Grade
- Torrefied "Black" Pellets
- By Application
- Heating
- Power Generation
- Combined Heat and Power (CHP)
- By End-user
- Residential
- Commercial
- Industrial and Utility
- Animal Bedding
- By Geography
- United Kingdom
- Germany
- France
- Spain
- NORDIC Countries
- Russia
- Rest of Europe
List of Companies Covered in this Report:
- Stora Enso Oyj
- Enviva Inc.
- AS Graanul Invest
- Drax Group plc
- Segezha Group PJSC
- Svenska Cellulosa AB (SCA)
- German Pellets GmbH
- Pure Biofuel Ltd
- Pfeifer Group
- Erdenwerk Gregor Ziegler GmbH
- Scandbio AB
- RZ Pellets GmbH
- Ante-Holz GmbH
- CM Biomass Partners A/S
- Lignetics of Idaho Inc.
- Wismar Pellets GmbH
- Vida AB
- Balcas Energy
- Burpellet SL
- FRP Pellets SpA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Robust residential-heating demand amid record fossil-fuel prices
- 4.2.2 Accelerated coal-to-biomass conversion of EU power plants
- 4.2.3 New EU-ETS incentives for negative-emission BECCS projects
- 4.2.4 Surge in heat-pump / pellet-hybrid boiler retrofits
- 4.2.5 Fast-track permitting for post-Russia supply-chain localization
- 4.3 Market Restraints
- 4.3.1 Termination of national pellet boiler subsidies in core markets
- 4.3.2 Rising competition from heat-pump only solutions
- 4.3.3 Feed-wood fibre scarcity & price spikes post-Ukraine war
- 4.3.4 EUDR sustainability compliance costs
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products & Services
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Feedstock
- 5.1.1 Forest/Wood Residue
- 5.1.2 Agricultural Residue
- 5.1.3 Energy-Crop and Sawdust Mix
- 5.2 By Grade
- 5.2.1 Utility-Grade (White)
- 5.2.2 Premium-Grade
- 5.2.3 Standard-Grade
- 5.2.4 Torrefied "Black" Pellets
- 5.3 By Application
- 5.3.1 Heating
- 5.3.2 Power Generation
- 5.3.3 Combined Heat and Power (CHP)
- 5.4 By End-user
- 5.4.1 Residential
- 5.4.2 Commercial
- 5.4.3 Industrial and Utility
- 5.4.4 Animal Bedding
- 5.5 By Geography
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Spain
- 5.5.5 NORDIC Countries
- 5.5.6 Russia
- 5.5.7 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Stora Enso Oyj
- 6.4.2 Enviva Inc.
- 6.4.3 AS Graanul Invest
- 6.4.4 Drax Group plc
- 6.4.5 Segezha Group PJSC
- 6.4.6 Svenska Cellulosa AB (SCA)
- 6.4.7 German Pellets GmbH
- 6.4.8 Pure Biofuel Ltd
- 6.4.9 Pfeifer Group
- 6.4.10 Erdenwerk Gregor Ziegler GmbH
- 6.4.11 Scandbio AB
- 6.4.12 RZ Pellets GmbH
- 6.4.13 Ante-Holz GmbH
- 6.4.14 CM Biomass Partners A/S
- 6.4.15 Lignetics of Idaho Inc.
- 6.4.16 Wismar Pellets GmbH
- 6.4.17 Vida AB
- 6.4.18 Balcas Energy
- 6.4.19 Burpellet SL
- 6.4.20 FRP Pellets SpA
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


