|
시장보고서
상품코드
2125514
동남아시아의 컨설팅 서비스 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)South-East Asia Consulting Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
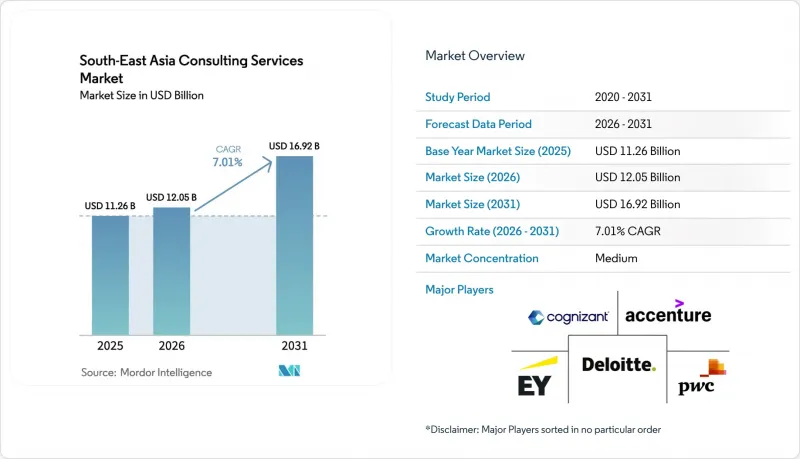
에 의하면, 2026년 동남아시아의 컨설팅 서비스 시장 규모는 120억 5,000만 달러로 추정되고, 2025년 112억 6,000만 달러에서 성장하여 2031년에는 169억 2,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 7.01%가 될 것으로 전망됩니다.
본 보고서는 서비스 유형별(인사 컨설팅, 재무 컨설팅, 기타), 최종 사용자 산업별(금융 서비스, 생명과학 및 헬스케어, IT 및 통신, 기타), 컨설팅 모델별(프로젝트 기반 자문, 리테이너 기반 자문, 기타), 기업 규모별(중소기업(SME) 및 대기업), 국가별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
동남아시아의 컨설팅 서비스 시장 동향 및 인사이트
디지털 퍼스트(Digital First) 변혁 프로그램
싱가포르의 ‘스마트 네이션(Smart Nation)’ 이니셔티브와 말레이시아의 ‘디지털 투자청(Digital Investment Agency)’과 같은 정부 주도 프로그램을 통해, 지역 전체의 변혁 프로젝트에 총 480억 달러가 투입되고 있습니다. 인도네시아가 2만 7,000개의 공공 부문용 앱을 9개의 슈퍼 앱으로 통합할 계획은 전문적인 자문이 필요한 변경 관리, 사이버 보안, 클라우드 전환과 같은 과제의 복잡성을 여실히 보여줍니다. 현재 1,600명 이상의 공공 부문 사용자를 지원하고 있는 싱가포르의 ‘Analytics.gov’ 플랫폼은 데이터 거버넌스, AI 모델 구축, 여러 기관에 걸친 프로세스 통합을 위해 필요한 컨설팅 업무의 중요성을 부각시키고 있습니다. 태국 전력 공사는 송전망 최적화를 위해 PLEXOS를 도입했습니다. 이는 에너지 및 공공 서비스 전반에 걸쳐 자원 계획에 관한 자문 서비스에 대한 수요가 증가하고 있음을 시사합니다. 이러한 노력은 엔터프라이즈 아키텍처, 거버넌스, 인재 역량 강화와 관련된 다년간의 계약이 동남아시아 컨설팅 서비스 시장에 견실한 수익원이 되고 있는 이유를 여실히 보여줍니다.
중소기업(SME) 및 스타트업의 급증에 따른 확장성 있는 자문 수요
아세안 기업의 97%는 MSME(중소·영세 기업)이며, 3,000억 달러의 자금 부족에 직면해 있습니다. 이러한 상황에 따라 각국 정부와 기부 기관들은 컨설팅 서비스 이용에 대한 보조금을 지원하고 있습니다(HSBC.COM). 기존의 1일당 350-1,500달러에 달하던 요금을 대폭 하회하는 구독형 모델이 보급되면서, 창업자들은 1일당 250-1,600달러의 보수를 받는 독립 전문가로부터 수시 상담을 받을 수 있게 되었습니다. InnoVen Capital의 190건에 달하는 투자로 뒷받침된 베트남의 벤처 생태계는 고성장 스타트업들 사이에서 자금 조달, 유닛 이코노믹스, 시장 진출 전략에 관한 컨설팅 수요가 증가하고 있음을 보여줍니다. ‘아세안 사회적 기업 개발 프로그램 4.0’과 같은 기관 주도의 프로그램에서는 교육 및 최대 4만 달러의 시드 보조금이 제공되어 컨설팅 고객 기반을 더욱 확대되고 있습니다. 창업자들이 지속 가능한 수익성을 우선시함에 따라, 자본 효율성과 ESG 통합에 정통한 컨설턴트에 대한 수요가 증가하고 있으며, 이는 동남아시아 컨설팅 서비스 시장의 장기적인 성장세를 뒷받침하고 있습니다.
기업 내 컨설팅 체계 구축
DBS와 같은 금융 기관은 사내 디지털 전환 전문 팀을 육성하고 있으며, 일상적인 분석, 사이버 보안, DevOps 관련 업무에서 외부 자문가에 대한 의존도를 낮추고 있습니다. 이러한 사내 팀은 조직적인 인사이트력을 축적하고 기업 문화와 긴밀히 연계되어 있기 때문에 실행 속도 면에서 외부 컨설턴트와 동등하거나 심지어 이를 능가하는 경우도 적지 않습니다. 이 모델을 모방하는 기업이 늘어남에 따라 일상적인 자문 비용의 일부가 사내로 이전되면서, 상품화된 서비스의 수익 성장을 억제하고 있습니다. 그러나 복잡한 여러 시장에 걸친 변혁, 익숙하지 않은 규제 변경, 이사회가 지시한 독립적인 검토에는 여전히 외부의 객관성이 요구되므로, 고부가가치 업무의 여지는 남아 있습니다. 컨설팅 기업들은 전문성을 한층 더 심화하고, 사내 팀으로는 재현하기 어려운 성과 연계형 계약을 제안함으로써 이러한 상황에 대응하고 있습니다.
부문별 분석
IT·디지털 컨설팅은 2025년 매출의 37.02%를 차지했으며, 레거시 스택의 폐지, 클라우드 네이티브 아키텍처의 채택, AI 워크로드 도입에 대한 기업의 절박한 요구를 여실히 보여주고 있습니다. 이 부문에서 동남아시아 컨설팅 서비스 시장 규모는 하이퍼스케일 클라우드에 대한 투자와 공공 부문의 디지털화 추진 방침에 따라 꾸준히 확대될 것으로 예측됩니다. 연평균 성장률(CAGR) 17.55%로 성장하고 있는 지속가능성·ESG 컨설팅은 싱가포르의 2025년 ESG 보고 의무화 및 FTSE 러셀 기준에 따라 명칭을 변경한 태국의 SET ESG 등급이 호재로 작용하고 있습니다. 고객사들로부터는 디지털과 ESG를 통합한 로드맵에 대한 수요가 높아지고 있으며, 이에 따라 각 기업은 기술 인력을 대상으로 탄소 회계 프레임워크에 관한 교차 교육을 실시했습니다. 전략·업무 컨설팅은 제조업체의 ‘중국+1’ 전략 전환으로 혜택을 보고 있는 반면, 리스크 및 컴플라이언스 자문사는 도입 아키텍처를 분할하는 국가별로 상이한 데이터 현지화 법을 활용하고 있습니다. 인사 컨설팅은 기술 관련 직종의 30-70%가 공석 상태인 점에 힘입어 견조한 성장세를 유지하고 있으며, 인재 분석 및 인력 계획 관련 프로젝트를 주도하고 있습니다.
컨설팅 기업들은 현재 AI 코파일럿을 서비스 제공에 통합하여 문서 검토 및 시나리오 모델링을 자동화함으로써, 스프린트 주기를 단축하고 자문 사업의 수익성을 높이고 있습니다. Tact Social Consulting과 같은 기업은 하이퍼스케일러와 제휴하여 클라우드 크레딧을 ESG 자문 서비스와 결합함으로써 태국 전역에서 기업용 파일럿 프로젝트를 수주하고 있습니다. 성과 기반 보수가 시간 단위 과금 모델을 대체하는 가운데, 서비스 제공업체들은 비용 절감, 위험 완화 또는 탄소 감축 지표를 통해 가치를 정량화하고 있으며, 이러한 접근 방식은 투명성을 추구하는 CFO들의 공감을 얻고 있습니다. 동남아시아 컨설팅 서비스 시장에서 디지털 자문 매출이 차지하는 비중은 지속가능성 관련 업무의 급증에도 불구하고 2031년까지 35% 이상을 유지할 것으로 예상되며, 이는 기술과 ESG 요구를 융합한 지속적인 이중 성장 패턴을 보여줍니다.
금융 서비스는 종합적인 디지털 뱅킹 로드맵, 오픈 API 준수, 엄격한 자금 세탁 방지 규제의 뒷받침을 받아 2025년 지출의 27.05%를 차지했습니다. KBank의 KBTG 부문과 베트남의 MSB와 Backbase의 제휴는 옴니채널 플랫폼 및 AI를 활용한 신용 평가 엔진에 투자하는 금융 기관의 대표적인 사례입니다. 에너지·유틸리티 부문은 14.06%의 연평균 성장률(CAGR)로 가장 빠른 확장을 보이고 있으며, 그 원동력은 송전망 현대화, 태국의 PLEXOS 도입, 인도네시아 동자바주의 국내 최초 디지털 변전소 등 재생에너지 통합 프로젝트입니다. 전자 및 자동차 제조업체들이 공급망 재구성을 추진함에 따라 제조업용 컨설팅 수요가 급증하고 있는 반면, 통신 사업자들은 5G 및 데이터센터 구축에 막대한 설비 투자를 쏟아붓고 있어 인프라 자문 수요가 높아지고 있습니다.
인도네시아의 9개 슈퍼앱 통합에 따라 정부 및 공공 부문 프로젝트가 급증하고 있으며, 프로그램 관리 사무소, 사이버 보안, 서비스 설계에 대한 전문 지식에 대한 수요가 높아지고 있습니다. 소매 및 전자상거래 부문의 프로젝트에서는 2025년까지 모바일 지갑 계정 수가 4억 4,000만 건에 달한 것으로 평가된 가운데, 고객 경험 재설계와 부정 분석에 초점이 맞추어지고 있습니다. 의료 서비스 제공업체들은 보험 청구 처리 시간 단축 및 환자 분류 개선을 목적으로 클라우드 전환을 추진하고 있으며, 이에 따라 HIPAA 준수 및 레거시 시스템 폐지에 관한 컨설팅 수요가 발생하고 있습니다. 이러한 각 산업이 어우러져 견실한 프로젝트 파이프라인을 유지하고 있으며, 이는 동남아시아 컨설팅 서비스 시장이 아시아 신흥 경제권 내 자문 업무의 핫스팟임을 다시 한번 입증하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 인사이트
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the south-East Asia consulting services market size in 2026 is estimated at USD 12.05 billion, growing from 2025 value of USD 11.26 billion with 2031 projections showing USD 16.92 billion, growing at 7.01% CAGR over 2026-2031.
This report is Segmented by Service Type (HR Consulting, Financial Consulting, and More), End-User Industry (Financial Services, Life Sciences and Healthcare, IT and Telecommunications, and More), Consulting Model (Project-Based Advisory, Retainer-Based Advisory, and More), Firm Size (SMEs, and Large Enterprises), and Country. The Market Forecasts are Provided in Terms of Value (USD).
South-East Asia Consulting Services Market Trends and Insights
Digital-first Transformation Programmes
Government programmes such as Singapore's Smart Nation initiative and Malaysia's Digital Investment Office are collectively injecting USD 48 billion into regional transformation projects . Indonesia's plan to merge 27,000 public-sector apps into nine super-apps exemplifies the complexity of change management, cybersecurity, and cloud migration tasks that demand specialized advice. Singapore's Analytics.gov platform, now supporting more than 1,600 public-sector users, highlights the consultative work required to govern data, build AI models, and align multi-agency processes. Thailand's electricity authority chose PLEXOS for grid optimization, signaling rising need for resource-planning advisory across energy utilities. Together these initiatives demonstrate why multi-year engagements around enterprise architecture, governance, and talent upskilling form a resilient revenue stream for the South-East Asia consulting services market.
SME and Start-up Boom Demanding Scalable Advice
Ninety-seven percent of ASEAN businesses are MSMEs, and they face a USD 300 billion funding deficit, prompting governments and donors to subsidize advisory access [HSBC.COM]. Subscription models priced well below the traditional USD 350-1,500 daily rate are gaining ground, enabling founders to secure on-call guidance using independent experts billing USD 250-1,600 per day. Vietnam's venture ecosystem, supported by InnoVen Capital's 190 loans, illustrates the appetite for fundraising, unit economics, and go-to-market consulting among high-growth startups. Institutional programs such as the ASEAN Social Enterprise Development Programme 4.0 supply training and seed grants up to USD 40,000, further widening the advisory client base. As founders prioritize sustainable profitability, demand rises for consultants versed in capital efficiency and ESG integration, reinforcing long-term momentum for the Southeast Asia consulting services market.
Corporate In-house Consulting Build-outs
Financial institutions such as DBS have cultivated internal digital-transformation squads, reducing dependence on third-party advisors for day-to-day analytics, cybersecurity, and DevOps mandates. These captive units accumulate institutional knowledge and align tightly with corporate culture, often matching or outpacing external consultants on speed of execution. As more enterprises replicate the model, a portion of routine advisory spend migrates in-house, trimming revenue growth for commoditized services. However, complex multi-market transformations, unfamiliar regulatory changes, and independent board-mandated reviews still require external objectivity, preserving scope for high-value engagements. Consulting firms are responding by deepening specialization and offering outcome-based contracts that internal teams struggle to replicate.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of AI, Analytics and Cloud Platforms
- Government Digital-Economy Road-maps and FDI Inflows
- Price Erosion from Commoditized Offerings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
IT and Digital Consulting contributes 37.02% of 2025 revenue, underscoring enterprise urgency to decommission legacy stacks, adopt cloud-native architectures, and deploy AI workloads. The Southeast Asia consulting services market size for this segment is forecast to expand steadily alongside hyperscale cloud investments and public-sector digital mandates. Sustainability and ESG Consulting, growing at an 17.55% CAGR, gains momentum from Singapore's 2025 compulsory ESG reporting and Thailand's re-branded SET ESG Ratings that align with FTSE Russell standards . Clients increasingly demand integrated digital-plus-ESG roadmaps, prompting firms to cross-train technologists in carbon-accounting frameworks. Strategy and Operations Consulting benefits from manufacturers' China+1 shifts, while Risk and Compliance advisors capitalize on divergent data-localization laws that fragment deployment architectures. HR Consulting remains resilient as 30-70% of tech roles sit vacant, driving projects in talent analytics and workforce planning.
Consultancies now embed AI copilots into delivery, automating document review and scenario modeling, thus shortening sprint cycles and elevating advisory margins. Firms like Tact Social Consulting partner with hyperscalers to bundle cloud credits with ESG advisory, winning enterprise pilots across Thailand. As output-based fees displace billable-hour models, providers quantify value via cost savings, risk mitigation, or carbon-reduction metrics, an approach that resonates with CFOs seeking transparency. The South-East Asia consulting services market share of digital advisory revenue is projected to hold above 35% through 2031 despite the surge in sustainability work, indicating a durable dual-track growth pattern that fuses technology and ESG imperatives.
Financial Services represented 27.05% of 2025 spending, anchored by exhaustive digital banking roadmaps, open-API compliance, and stringent anti-money-laundering rules. KBank's KBTG unit and Vietnam's MSB-Backbase partnership are emblematic of institutions investing in omnichannel platforms and AI-enabled credit engines. Energy and Utilities produces the fastest expansion at 14.06% CAGR, fueled by grid modernization and renewable-integration projects such as Thailand's PLEXOS deployment and Indonesia's first digital substation in East Java. Manufacturing consulting demand swells as electronics and automotive firms replot supply chains, while telecom operators channel big-ticket capex into 5G and data-center buildouts, attracting infrastructure advisory.
Government and Public Sector engagements escalate with Indonesia's nine-super-app consolidation, pushing requirements for program management offices, cybersecurity, and service-design expertise. Retail and E-commerce assignments focus on customer-journey redesign and fraud analytics as mobile wallets multiply to an expected 440 million accounts by 2025. Healthcare providers pursue cloud migrations to compress claims-processing times and improve patient triage, opening avenues for HIPAA-analog compliance and legacy-system decommissioning consulting. Collectively, these verticals sustain a robust pipeline, reaffirming the South-East Asia consulting services market as the advisory hotspot within emerging Asian economies.
Complete Report Scope:
- By Service Type
- HR Consulting
- Financial Consulting
- IT and Digital Consulting
- Strategy and Operations Consulting
- Risk and Compliance Consulting
- Sustainability and ESG Consulting
- By End-user Industry
- Financial Services
- Life Sciences and Healthcare
- IT and Telecommunications
- Government and Public Sector
- Energy and Utilities
- Manufacturing
- Retail and E-commerce
- By Consulting Model
- Project-based Advisory
- Retainer-based Advisory
- Managed Services / Outsourcing
- Advisory-as-a-Service (Subscription)
- By Firm Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By Country
- Singapore
- Indonesia
- Thailand
- Vietnam
- Philippines
- Malaysia
- Rest of Southeast Asia
List of Companies Covered in this Report:
- Accenture plc
- Deloitte Touche Tohmatsu Limited
- PricewaterhouseCoopers International Limited (PwC)
- Ernst and Young Global Limited
- KPMG International Limited
- McKinsey & Company, Inc.
- Boston Consulting Group, Inc.
- Bain & Company, Inc.
- Cognizant Technology Solutions Corporation
- Tata Consultancy Services Limited
- Wipro Limited
- Mercer LLC
- Aon plc
- Protiviti Inc.
- A.T. Kearney, Inc.
- Roland Berger Holding GmbH
- L.E.K. Consulting LLC
- Frost & Sullivan, Inc.
- RSM International Limited
- YCP Holdings Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET INSIGHTS
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Digital-first transformation programmes
- 4.2.2 SME and start-up boom demanding scalable advice
- 4.2.3 Adoption of AI, analytics and cloud platforms
- 4.2.4 Government digital-economy road-maps and FDI inflows
- 4.2.5 Mandatory ESG-reporting fuelling sustainability advisory
- 4.2.6 China+1 supply-chain realignment into ASEAN
- 4.3 Market Restraints
- 4.3.1 Corporate in-house consulting build-outs
- 4.3.2 Price erosion from commoditised offerings
- 4.3.3 Shortage of bilingual domain experts
- 4.3.4 Data-sovereignty and residency barriers
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Industry Ecosystem Analysis
- 4.9 Key Use Cases and Case Studies
- 4.10 Assessment of Macroeconomic Trends
- 4.11 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 HR Consulting
- 5.1.2 Financial Consulting
- 5.1.3 IT and Digital Consulting
- 5.1.4 Strategy and Operations Consulting
- 5.1.5 Risk and Compliance Consulting
- 5.1.6 Sustainability and ESG Consulting
- 5.2 By End-user Industry
- 5.2.1 Financial Services
- 5.2.2 Life Sciences and Healthcare
- 5.2.3 IT and Telecommunications
- 5.2.4 Government and Public Sector
- 5.2.5 Energy and Utilities
- 5.2.6 Manufacturing
- 5.2.7 Retail and E-commerce
- 5.3 By Consulting Model
- 5.3.1 Project-based Advisory
- 5.3.2 Retainer-based Advisory
- 5.3.3 Managed Services / Outsourcing
- 5.3.4 Advisory-as-a-Service (Subscription)
- 5.4 By Firm Size
- 5.4.1 Small and Medium Enterprises (SMEs)
- 5.4.2 Large Enterprises
- 5.5 By Country
- 5.5.1 Singapore
- 5.5.2 Indonesia
- 5.5.3 Thailand
- 5.5.4 Vietnam
- 5.5.5 Philippines
- 5.5.6 Malaysia
- 5.5.7 Rest of Southeast Asia
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 Deloitte Touche Tohmatsu Limited
- 6.4.3 PricewaterhouseCoopers International Limited (PwC)
- 6.4.4 Ernst and Young Global Limited
- 6.4.5 KPMG International Limited
- 6.4.6 McKinsey & Company, Inc.
- 6.4.7 Boston Consulting Group, Inc.
- 6.4.8 Bain & Company, Inc.
- 6.4.9 Cognizant Technology Solutions Corporation
- 6.4.10 Tata Consultancy Services Limited
- 6.4.11 Wipro Limited
- 6.4.12 Mercer LLC
- 6.4.13 Aon plc
- 6.4.14 Protiviti Inc.
- 6.4.15 A.T. Kearney, Inc.
- 6.4.16 Roland Berger Holding GmbH
- 6.4.17 L.E.K. Consulting LLC
- 6.4.18 Frost & Sullivan, Inc.
- 6.4.19 RSM International Limited
- 6.4.20 YCP Holdings Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment